Individual Economists

BRICS Summit Takes Aim At US Influence Over The Global Economy

Zero Hedge -

BRICS Summit Takes Aim At US Influence Over The Global Economy

Authored by Eurasianet via OilPrice.com,

  • BRICS demanded greater developing-country influence at the IMF, World Bank and WTO but avoided directly naming the United States in its criticism.

  • The declaration urged “maximum restraint” in the Middle East and made no mention of Ukraine, illustrating the compromises required to maintain consensus.

  • Kazakhstan used the summit to balance BRICS ties with Washington, while Uzbekistan’s president traveled to South Korea and sent a deputy prime minister to represent the country in New Delhi.

Like the Shanghai Cooperation Organization, BRICS, the global grouping of emerging markets and developing countries, is intent on diminishing Western influence over the world economy. And just like the SCO summit earlier in September, the latest conclave of BRICS leaders fell short of presenting a united front against the West, the United States in particular.

Both the SCO and BRICS include China, India, Iran and Russia as permanent members. Among the four, India, the host nation for this edition of the BRICS annual summit, has acted as a brake on efforts to de-dollarize the global economy. Kazakhstan and Uzbekistan are both BRICS partner countries.

BRICS members adopted a 140-point joint statement September 12 that featured calls for major reforms of Western-dominated financial institutions, including the World Trade Organization, the International Monetary Fund and the World Bank, to give developing countries a greater say in policymaking and practices.

Some joint statement provisions took oblique swipes at the Trump administration. For example, in comments on the WTO, the statement noted a "proliferation of trade-restrictive actions that are inconsistent with WTO rules, whether in the form of indiscriminate raising of tariffs and non-tariff measures, or protectionism under the guise of environmental objectives."

But the statement does not mention the United States or Trump by name, and it soft-pedals the group's stance on the Gulf war currently embroiling the US, Israel and Iran, calling for "maximum restraint" of all sides, instead of adopting a clear position more favorable to Tehran.

Iran came away with a symbolic victory of sorts, however, underscored by a one-on-one between Iranian President Masoud Pezeshkian and Abu Dhabi's crown prince, Khaled bin Mohamed bin Zayed, a meeting designed to counter the image that the United States is succeeding in economically isolating Tehran.

A statement issued by Abu Dhabi officials was non-committal about future bilateral ties, however. The two "discussed a number of regional and international issues of mutual interest," while emphasizing a need to promote "de-escalation and strengthen regional stability."

Beyond the Gulf war, the BRICS statement makes no mention of the Russia-Ukraine conflict, a clear win for the Kremlin.

Underscoring a lack of unity within the broader BRICS framework, Uzbek President Shavkat Mirziyoyev passed over the summit in New Delhi, instead making a state visit to South Korea, where he promoted stronger economic ties with the East Asian Tiger.

South Korea will host a gathering of leaders from all five Central Asian states in Seoul under a C5+1 format on September 16.

Meanwhile, in an expanded session of the BRICS gathering, Kazakh President Kassym-Jomart Tokayev adopted a middle-of-the-road stance that, consistent with the country's multi-vector foreign policy, sought to balance the interests of China, Russia, the United States and the European Union.

"The erosion of the international security architecture and protracted conflicts are increasing the risk of a new arms race and strategic miscalculations and practical wrongdoings," Tokayev said. "Therefore, high-level dialogue among nuclear powers is needed to reduce nuclear risks, including those linked to new technologies."

The comments could be seen as referring to the Russia-Ukraine conflict. But they can also be interpreted as a call for the US and China to de-escalate their deepening rivalry for dominance in the development of artificial intelligence. Central Asia is emerging as a central battleground in the brewing race for AI leadership.

Tokayev went on to characterize BRICS as "an open platform for practical cooperation that complements the UN-centered multilateral system and connects peoples, regions and markets."

On the sidelines of the BRICS gathering, Tokayev met with Sergio Gor, the US ambassador to India, who is also the Trump administration's special representative to Central Asian states. Tokayev told Gor that he is looking forward to participating in the G20 meeting to be held in Miami in December. But he also delivered an unusually blunt message, indicating that he expects faster progress on deal-making between the United States and Kazakhstan and the repeal of the Central Asian nation's Jackson-Vanik trade status.

The Miami gathering will provide "a good opportunity to discuss bilateral issues," a Kazakh readout of the conversation quoted Tokayev as saying. "We prefer concrete actions and practical steps to advance our mutual cooperation, rather than just words."

Tyler Durden Wed, 09/16/2026 - 17:40

US Interceptor Inventory Took Another Big Hit Last Week, As CBO Pegs War Cost At $38 Billion+

Zero Hedge -

US Interceptor Inventory Took Another Big Hit Last Week, As CBO Pegs War Cost At $38 Billion+

America's already-diminished inventory of air defense interceptor missiles took another significant hit last week, as dozens more were expended to defend US troops in Jordan from an Iranian attack. This latest incident illustrates Iran's use of crafty and increasingly technologically-advanced attacks to further sap US munitions supply and degrade the Pentagon's ability to continue mounting defenses -- or provoking attacks -- in a war nearing the seven-month mark.  

The action unfolded on Sept 8, when Iran attacked US forces at the Muwaffaq Salti Air Base in Azraq, Jordan. Unleashing what it called a "punitive operation" following the destruction of five Iranian oil tankers by the US military, Iran fired a volley of about 20 ballistic missiles at the base. No one was killed, but fighters and other aircraft positioned at the facility were damaged.   

To defend the air base, US forces fired 60 to 70 Patriot interceptors and more than dozen Terminal High Altitude Area Defense (THAAD) interceptors, according to US officials who talked to the Wall Street Journal. Patriots cost the Pentagon about $4 million each, and the more sophisticated THAADs go for $12 to $15 million. That means the defense from this attack on a single target may have cost half a billion dollars or more.  

The large expenditure of interceptors was driven by the complexity of the Iranian attack. Part of the strike package included missiles that, at high altitude, release multiple munitions. Over the course of the war, Iran has continued to enhance its already formidable missile capabilities, making warheads more maneuverable and giving some an ability to greatly accelerate before impact. “These types of new tactics that we’re seeing show that the Iranians continue to adapt, continue to learn, continue to experiment, see what works, what doesn’t work,” Conflict Armament Research's Fabian Hinz told the Journal.   

News of the latest dent in the US war chest follows a report from the Pentagon's inspector general declaring that the war on Iran “has resulted in strategic inventory shortfalls and revealed industrial base bottlenecks for munitions resupply.” The IG report landed just after President Trump claimed "the United States is producing more Exquisite and Elite Weapons than at any time in our History. They are being delivered on a daily basis to our Forces in the Middle East, and beyond." (Retarded capitalization scheme is, of course, Trump's.)   

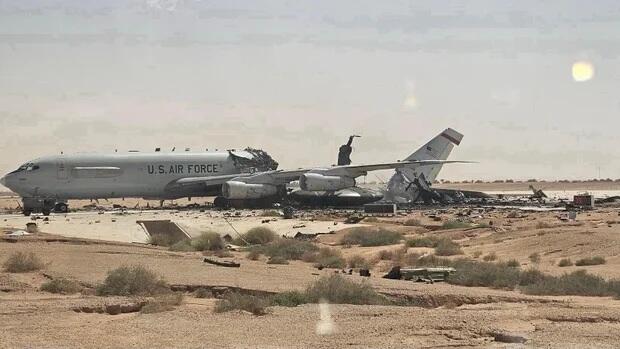
This photo of a shattered US Air Force jet at Prince Sultan AFB in Saudi Arabia was one of several leaked to CBS 

Also this week, the Congressional Budget Office said the Pentagon spent $38 billion on this war of choice -- and that's only through Aug 1. CBO said it expects the meter to keep running at about $2 or $3 billion a month as long as the war goes on. Critically, CBO warned that its estimates were hampered by the Defense Department's refusal to respond to requests for information. 

CBO's numbers do not account for a rebuilding of the many US bases in the region that have been hammered by Iranian fire and abandoned by US forces. To the extent this abandonment becomes prudently permanent, excluding that cost may make sense. 

CBO further estimated that, as things stood back on Aug 1, it would take $22 billion to restock expended munitions -- attributing $7 billion to cruise missiles and $13 billion for air defense interceptors. “The shortfall would become especially problematic if a conflict arose with an opponent whose arsenal included large numbers of ballistic and cruise missiles,” the CBO reported.

“Claims of U.S. munition shortages are false,” said Pentagon spokesman Sean Parnell. “We have everything required to strike at the time and place of the President’s choosing.” Of course, this is the same administration that falsely told us Iran was on the threshold of having a nuclear bomb.  

Tyler Durden Wed, 09/16/2026 - 17:20

House Panel Votes To Hold Billionaire Leon Black In Contempt For Ghosting Epstein Investigators

Zero Hedge -

House Panel Votes To Hold Billionaire Leon Black In Contempt For Ghosting Epstein Investigators

Authored by Zachary Stieber via The Epoch Times,

Businessman Leon Black, who skipped a deposition regarding his relationship with the late sex offender Jeffrey Epstein, should be held in contempt of Congress, a House of Representatives panel recommended on Sept. 15.

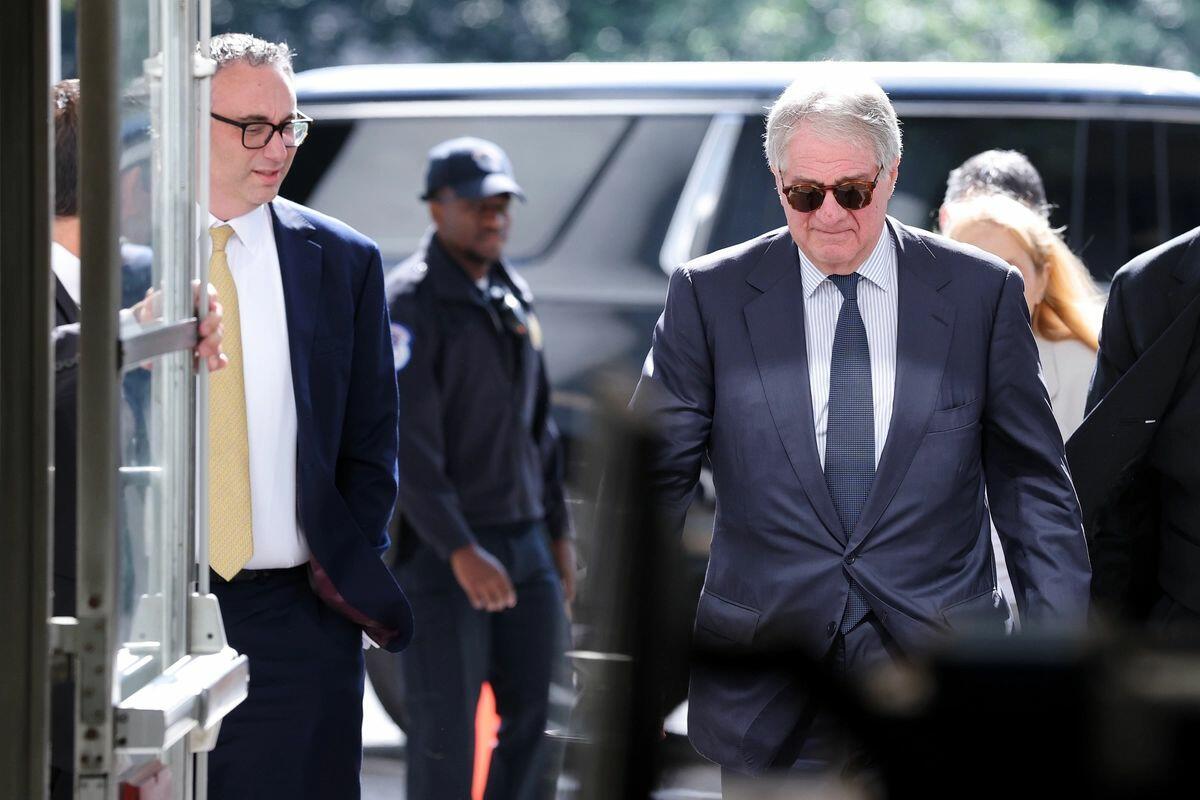
Former Apollo Global Management CEO Leon Black (R) arrives for an interview with the House Oversight Committee in Washington on June 26, 2026. Kevin Dietsch/Getty Images

The House Oversight Committee unanimously voted 41-0 to advance a contempt resolution of Black, 75, to the full chamber. House leadership will decide whether to take up the matter in the future.

Black's lawyer did not return a request for comment by the time of publication.

Black was subpoenaed to testify to the committee regarding his relationship with Epstein, who was convicted of soliciting a minor for prostitution and faced sex trafficking charges when he died in federal prison in 2019. The committee also told Black, under subpoena, to provide documents it said were critical to its investigation of Epstein and his network.

"He defied Congress and refused to do either," Rep. James Comer (R-Ky.), committee chairman, said ahead of the vote. "Instead, Mr. Black is hiding behind litigation to delay having to provide answers to the American people. No one is above the law. Mr. Black will be treated the same as anyone else in this investigation, and his actions have consequences."

Black had previously appeared for a voluntary interview, but had refused to answer some questions, prompting the subpoenas.

Black sued the committee after avoiding the subpoenas, telling a court that the subpoenas were invalid because they sought "private information that bears no legitimate connection" to the committee's legislative purpose and would "expose women who value their privacy, who have no known or public connection to Epstein, who bargained for confidentiality and have refused to release it, and who have no ability to protect themselves and their privacy before the Committee."

The case is ongoing.

Black, who co-founded Apollo Global Management, had a "close personal relationship" with Epstein during the time that Epstein was allegedly engaged in sex trafficking, according to a report from the panel. Black also paid Epstein more than $158 million over the years, and potentially more than $170 million, according to the report.

"As a result of his extensive dealings with Epstein, Mr. Black possesses firsthand information regarding the activities of Epstein and Maxwell and their efforts to establish relationships and curry favor with influential individuals while engaged in sex trafficking," the report said. "His testimony may inform the Oversight Committee's consideration of legislative reforms designed to combat the operation of sex-trafficking rings and efforts to shield such activities from scrutiny."

Rep. Robert Garcia (D-Calif.), the top Democrat on the panel, said on Tuesday that lawmakers believe Black "is at the heart of the Epstein network."

"This is a private equity billionaire worth roughly $13 billion dollars. We need to know why Jeffrey Epstein got over 180 million dollars from Mr. Black. We know this money enabled Epstein's activities for years, and we need to know how and if it led to the abuse of women and girls. We need to know about Leon Black and Jeffrey Epstein's financial dealings," he added.

* * *

Tray

Knife

Notebook

AirTag Wallet

Pen

Tyler Durden Wed, 09/16/2026 - 17:00

Dario Amodei's Brain Trust Of Bad Ideas

Zero Hedge -

Dario Amodei's Brain Trust Of Bad Ideas

Authored by Jordan Schachtel via American Greatness,

Anthropic CEO Dario Amodei wants to shape the future of artificial intelligence - and, by extension, the future of civilization. Yet in doing so, he seeks input and advice from an ideologically uniform group of individuals and institutions.

In a series of sprawling essays on his website, Amodei has outlined his expectations for a world transformed by powerful AI. His forecasts range from curing diseases and accelerating economic growth to creating catastrophic biological threats and destabilizing the balance of power between the United States and China.

These essays are presented as the work of a sober-minded technologist trying to navigate humanity through an unprecedented transition.

In the acknowledgments section, Amodei inadvertently reveals insight into the ideas forming his worldview.

Across four of his major essays - "Machines of Loving Grace," "The Urgency of Interpretability," "The Adolescence of Technology," and "Policy on the AI Exponential" - Amodei thanks a recurring cast of advisers and intellectual collaborators. The list includes Tom McGrath, Martin Wattenberg, Chris Olah, Ben Buchanan, Kevin Esvelt, Parag Mallick, Stuart Ritchie, Matt Yglesias, Erik Brynjolfsson, Jim McClave, Allan Dafoe, Mariano-Florentino Cuéllar, Richard Fontaine, Buddy Shah, Vas Narasimhan, Nick Beckstead, Jason Matheny, and Brad Carson.

Amodei thanks this group for their contributions to his ideas, comments on his drafts, and help to strengthen his thinking.

Of course, these acknowledgments do not prove some kind of uniformity of worldview. However, they help us map his intellectual world.

And that world is remarkably homogeneous.

It includes, unsurprisingly, Anthropic insiders but also establishment academics, liberal policy experts, national-security think tankers, NGO executives, and prominent figures intertwined with the Effective Altruism (EA) movement.

Here are some of the more notable characters Dario Amodei has cited:

  • Matt Yglesias is a high-profile liberal journalist.

  • Ben Buchanan, an Anthropic adviser, served as a special adviser for AI at the White House Office of Science and Technology Policy.

  • Allan Dafoe is a prominent name in the Effective Altruism community, and he established one of its AI academic centers at Oxford.

  • Nick Beckstead is a high-profile figure in the Effective Altruism network.

  • Jason Matheny has deep, longstanding ties to the EA world, and he's now president of the RAND Corporation.

  • Richard Fontaine runs the left-leaning Center for a New American Security (CNAS), a major Democratic Party policymaker incubator in D.C.

  • Mariano-Florentino Cuéllar is the chief global affairs official at Anthropic and has long been a staple in the Democratic Party legal world.

  • Chris Olah is an Anthropic cofounder.

  • Stuart Ritchie is the research communications lead at Anthropic.

  • James "Jim" McClave is an early Anthropic investor who has long been embedded in the EA community. McClave reportedly made one of the largest 2022 contributions to Future Forward, a super PAC that supported Joe Biden.

  • Neil "Buddy" Shah is the CEO of the Clinton Health Access Initiative.

  • Brad Carson is a former Democratic congressman who served in senior positions in the Obama administration.

What is missing from this collection of contributors?

First and most obvious, there is no identifiable right-leaning intellectual, academic, or policymaker in the mix. Dario Amodei does not appear to consult with any White House-aligned voices, and few, if any, critics of centralized power or anyone skeptical of unverifiable international agreements with China.

We can't find anyone publicly mentioned within Amodei's brain trust who seems to recognize that global, U.N.-like institutions frequently fail or become quickly corrupted by a group of credentialed "experts" who inevitably just seek to increase their own power and status.

His brain trust is indeed diverse in professional specialization, but it's painfully narrow in ideological diversity.

That likely explains the liberal-internationalist-meets-Effective-Altruist blend that runs through his writing and media appearances. Amodei combines the Effective Altruist obsession with extinction-level AI risks with the liberal internationalist worldview, which posits that an "expert" class can design more useful international institutions outside of America's sovereign borders.

In "Machines of Loving Grace," putting aside the hyper-pagan notion of a machine God, Amodei is quite optimistic about AI being used to advance a variety of fields that can result in human flourishing. The essay considers a near future in which powerful AI systems are making decades of scientific progress in just months or years.

In "The Adolescence of Technology," however, Amodei concentrates on the darker side of the same exponential curve. He discusses autonomous AI, bioweapons, economic displacement, and authoritarian inputs that could threaten much of humanity. Consulting with his brain trust, Amodei is determined to construct systems capable of guiding us through this dangerous period of "adolescence."

In "The Urgency of Interpretability," he calls for transparency laws and strict export controls on AI chips to China. He argues, in consultation with his brain trust, that America could create enough breathing room to make powerful systems more understandable before geopolitical competition makes caution impossible.

Amodei isn't wrong to point out that AI companies should definitely test their systems before public release.

And it's wise to continue dedicating resources to researching how to understand these novel systems.

Yet Amodei's institutional reflex is visible throughout his writing. When he encounters something that is determined by his West Coast bubble as a risk, the "expert" brain trust fills in the gaps on policy and morality.

In his latest proposals, Amodei has floated something of a U.N.-style AI standards body and a Paris Climate Deal 2.0 with China.

Amodei told CBS, "The worry I have - I am concerned that one single government could abuse this technology just as easily as a single company could."

He added, "But I think a combination of democratically elected governments - I don't know about handing over, but some kind of oversight, some kind of joint governance."

As for the China deal, he says the agreement must be verifiable. He even concedes that an AI pause is unlikely because the incentive to cheat would be enormous. Yet he still presses as if this is the best option. If that sounds like Hillary Clinton and Barack Obama, it's not some accident of interpretation. He is using the liberal internationalist playbook.

As the Paris climate agreement already showed, the Chinese Communist Party is not a good-faith participant in international agreements. It is an adversarial regime seeking technological, military, and geopolitical supremacy over the United States.

A climate change-style agreement is hard enough to verify. With AI, it's even more difficult. Do we really think China is going to hand American inspectors a list of its most capable data centers, military facilities, intelligence-gathering sites, and a whole variety of other secret networks that are critical to its national AI program?

Amodei can see the problem, as evidenced in his writing, but his narrow intellectual brain trust prevents him from following it to its logical conclusion. He recognizes the behavior of adversarial states while retaining faith in the institutions that assume cooperation among them. And he wants to create new global government institutions that will supposedly solve these problems.

This is the reality of living and operating in the San Francisco tech bubble. Dario Amodei and his ideologically narrow group have introduced a series of highly elaborate ideas that have not been stress-tested by reality and history.

Everyone helping him answer complex questions comes from the same constellation of institutions, liberal policy shops, Effective Altruist-connected organizations, and technocratic philanthropy. His U.N. for AI and Paris 2.0 "solutions" reflect the blind spots in his thought process.

Before determining that he has all of the firepower to solve all of the big problems in AI, Dario Amodei should first consider expanding his own context window.

Tyler Durden Wed, 09/16/2026 - 16:20

Beyond Oil And Gold: Venezuela Readies First US Aluminum Shipment In Years As Resource Race Heats Up

Zero Hedge -

Beyond Oil And Gold: Venezuela Readies First US Aluminum Shipment In Years As Resource Race Heats Up

Venezuela is emerging as a source of energy and critical materials for the US as the Trump administration expands sourcing channels within the Western Hemisphere. Existing crude trade and a gold supply agreement with Caracas are being paired with efforts to develop broader industrial metal ties, including potential access to nickel and iron ore. That expansion may now include aluminum.

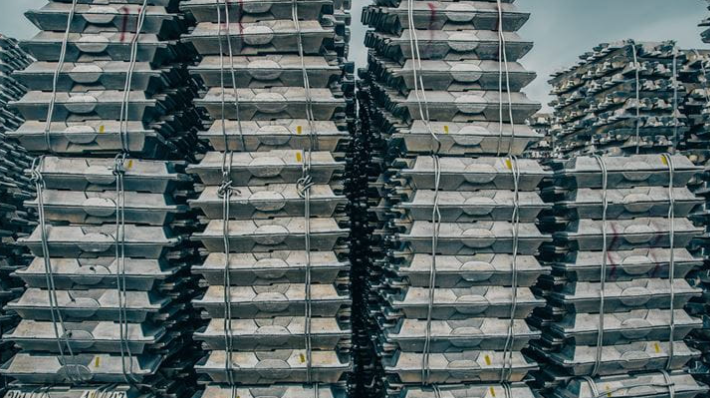
Bloomberg reports 15,000 metric tons of aluminum produced by state-owned Venalum could depart Venezuela by the end of the week under a deal involving Mercuria Energy Group and Heeney. 

US officials could announce the deal earlier this week during the G20 energy summit in Houston. Folks familiar with the shipment say it is worth nearly $50 million and would be modest relative to US consumption. 

The outlet previously reported that Mercuria and New York-based mining investment firm Heeney are in discussions with Venezuelan authorities to operate the Venalum smelter that was built in the 1970s with annual capacity of 430,000 tons. 

Years of underinvestment and power outages left the Orinoco River complex operating at a fraction of that level but new investments could revitalize the smelting plant. 

The 15,000-ton Venezuelan cargo equals roughly .4% of that annual import requirement. It would provide modest relief and another sourcing channel for the US when the domestic market is already tight. 

Beyond aluminum, the US Energy Under Secretary Kyle Haustveit said last month that US refineries were receiving more than 500,000 barrels per day of Venezuelan crude. There was a report earlier this year that State-owned Minerven agreed to supply US with 650 to 1,000 kilograms of gold dore bars to Trafigura for US markets. Washington is also seeking access to critical material markets in the country, such as niobium and tantalum. 

The Trump administration's stated strategy links greater US influence in the Western Hemisphere with secure access to critical resources and supply chains. Its new relations with Venezuela's energy and mining sectors reflect just that. Developing those resources will require substantial investment in production, processing, and infrastructure. 

Building a stable South America really began with ridding the continent of pro-China socialist regimes. Brazil's presidential election next month could cement a generational rightward shift

Tyler Durden Wed, 09/16/2026 - 15:45

The Fed's Mortgage Policy Made Homeownership Cost More

Zero Hedge -

The Fed's Mortgage Policy Made Homeownership Cost More

Authored by Antón Chamberlin via The Daily Economy,

The median household in Miami earns about $62,000 annually; homeowners with a mortgage have monthly housing costs pushing $2,900. Annualized, this equals more than half the median household income. In Los Angeles, the numbers come in at $82,000 and $3,500 for 51 percent. New Yorkers are paying 49 percent, and New Orleanians are paying 47 percent of their annual income on housing.

Elena Berd via Shutterstock.

Different coasts, different housing markets, different incomes, regulations, and supply constraints. And all of these cities illustrate a national reality that seems beyond dispute: housing has become extraordinarily expensive.

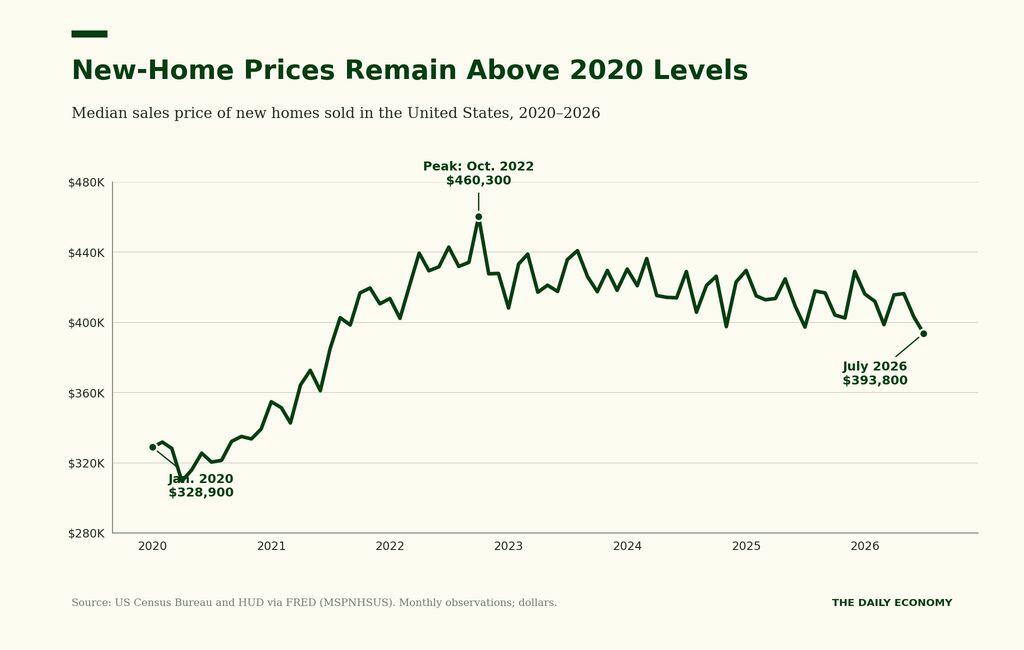
Lest these cities appear cherry-picked, let us consider Harvard's 2026 State of the Nation's Housing report. Existing-home sales are at a three-decade low. Meanwhile, median new and existing home prices exceed $400,000. Prices for the latter are now 54 percent higher than in 2020, nearly five times median household income.

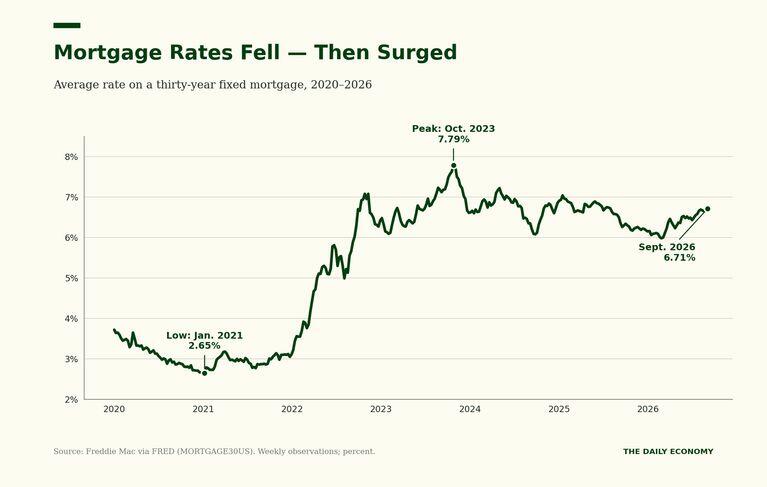
Financially, mortgage rates sit above 6 percent. By late 2025, the monthly cost of the median-priced home reached roughly $3,100, requiring an annual income above $120,000 to afford it, compared with about $1,700 and $66,000, respectively, in early 2020.

This bleak picture is obviously the product of many factors. One, however, was the Federal Reserve's intervention in the housing market. During the COVID lockdown era, the Fed entered the mortgage market on a massive scale, helping push borrowing costs to historic lows. But its intervention did more than simply lower mortgage rates. It also affected households differently, creating benefits for those already in the housing market while making entry more difficult for those who were not.

The Fed's mortgage-backed-security (MBS) purchases helped capitalize cheap credit into higher home prices, which enriched current homeowners, all the while increasing the costs of entry for prospective buyers. Then, when the Fed raised rates to fight inflation, those same outsiders faced both higher prices and higher financing costs.

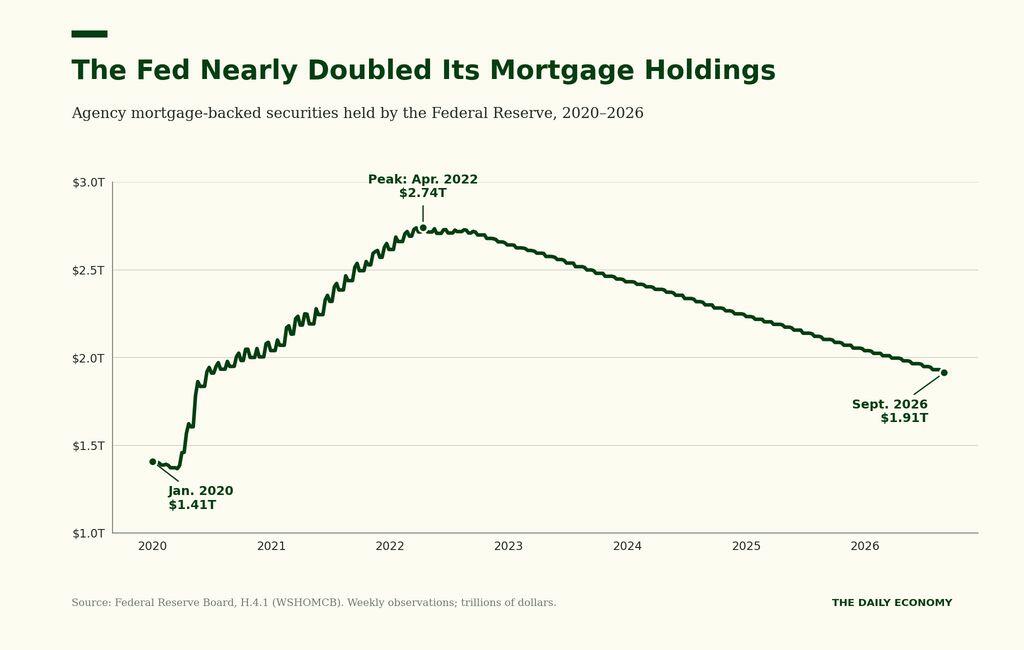
Beginning in March 2020, the Fed purchased trillions of MBSs, with Agency MBS holdings rising 93 percent in about two years, reaching $2.7 trillion by mid-2022. The Fed's immediate objective was seemingly achieved. Mortgage rates fell to historic lows, which the Dallas Fed explicitly laid at the feet of the Fed's MBS purchases.

Economic consequences, however, as Bastiat and Hazlitt showed for decades, extend beyond the short-run and the targeted groups. Cheaper mortgages increased households' purchasing power and contributed to greater housing demand, placing upward pressure on prices in a market where supply could not quickly adjust. Once inflation arrived, the Fed raised rates, causing this double whammy for would-be buyers. This had important distributional consequences.

At its peak, the Fed owned 32 percent of the entire agency MBS market. These purchases resulted in MBS prices rising and their yields falling, causing mortgage spreads to tighten. This tightening pushed mortgage rates down, allowing buyers to finance larger principal balances. Expanded borrowing opened up possibilities for buyers, further fueling housing demand. With the housing supply unable to sufficiently catch up to the new demand, the financial benefits were met with higher prices on the existing housing supply.

These results were not uniform, however. As with other exercises of monetary policy, where money enters matters.

The Cantillon Effect Comes Home

As Nicolás Cachanosky explains, new money does not enter an economy everywhere, and certainly not simultaneously. Fed actions consist of particular injections at particular points, then following particular paths. It is punctiliar by nature, and this results in changing relative prices, which benefit earlier recipients before prices have adjusted to the intervention. In this context, the relevant "early recipients" do not necessarily receive literal new money, but the injection in question occurs in financial markets closely connected to mortgage credit.

Households can be divided into at least two groups: incumbent owners and prospective buyers, both of whom experience the Fed policy differently. Incumbent owners already possess an appreciating asset, with the potential to refinance at the initial lower rate, seeing their home equity rise. Prospective buyers, by contrast, possess no appreciating asset; therefore, they see their desired homes become more expensive. The same appreciation that increases an incumbent homeowner's net worth increases the price of entry for everyone still trying to buy.

Beginning in 2022, the Fed changed direction. But tightening does not just unwind the past. Homeowners who had purchased or refinanced at historically low rates could keep those mortgages, while new buyers faced even higher rates. The Fed noticed this "lock-in" effect. By June 2024, more than 90 percent of its MBS holdings had coupons below 4 percent.

The Fed's policy can be broken down into two segments, then. During the easing period, low rates and rising prices fed equity gains for homeowning incumbents. Then, the tightening led to a lock-in of those owners at the previously lower rates, as outsiders saw higher rates. And, of course, first-time buyers typically possess neither asset: the equity nor the existing low-rate mortgage to offset these higher financing costs.

A Federal Reserve study from 2023 documented this phenomenon. A one-percentage-point increase in mortgage rates reduced the share of low- and moderate-income homebuyers by about 7.5 percent, with low-income buyers falling by 16 percent. These effects were even larger for first-time buyers. There was also little evidence of larger down payments to counteract the rising rates, suggesting that many could not substitute savings for the higher monthly payment. Evidence also suggests that loose monetary policy passing through to mortgage rates negatively affects family formation and fertility rates.

In total, then, we see the following. Lower rates create unequal access to cheap credit, and the subsequent higher rates affected buyers disparately. The Fed changed not only the cost of financing a house, but the composition of participants in the market. Interest rate policy altered who could buy.

America now has expensive housing, huge mortgages, fewer purchases, declining homeownership, and a growing segment of the population crowded out. At the very least, the Fed exacerbated this from 2020-2022. The broader lesson here is that monetary policy does not change interest rates or prices in isolation. Money always enters particular markets, changes particular relative prices, and creates particular winners and losers. In this instance, the Fed inflated the price of a scarce asset (appreciation for current homeowners). Once the subsidy was removed, the wealth redistribution it caused did not reverse. The consequence is our current state - not just housing inflation, but a higher price of entry.

Tyler Durden Wed, 09/16/2026 - 15:25

"Calm Before The Storm?" UBS Warns Of Stock Market Turbulence As Midterms Loom

Zero Hedge -

"Calm Before The Storm?" UBS Warns Of Stock Market Turbulence As Midterms Loom

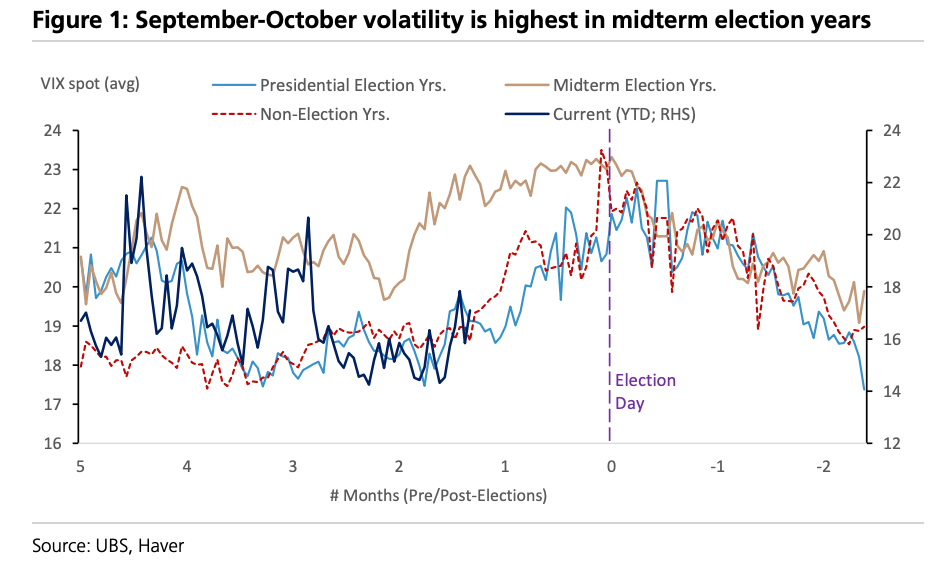
"This may be the calm before the storm," UBS chief economist Arend Kapteyn wrote in a note on Wednesday morning.

Kapteyn is referring to a historically turbulent stretch for equity markets ahead of midterm elections, which threatens to amplify the seasonal rise in market volatility.

"Indeed, since 1928, these have been the most volatile months of the calendar, with volatility increasing in both election and non-election years before falling sharply thereafter," Kapteyn continued.

Since 1950, the president's party has lost an average of 25 House seats and three Senate seats in midterm elections, Kapteyn said.

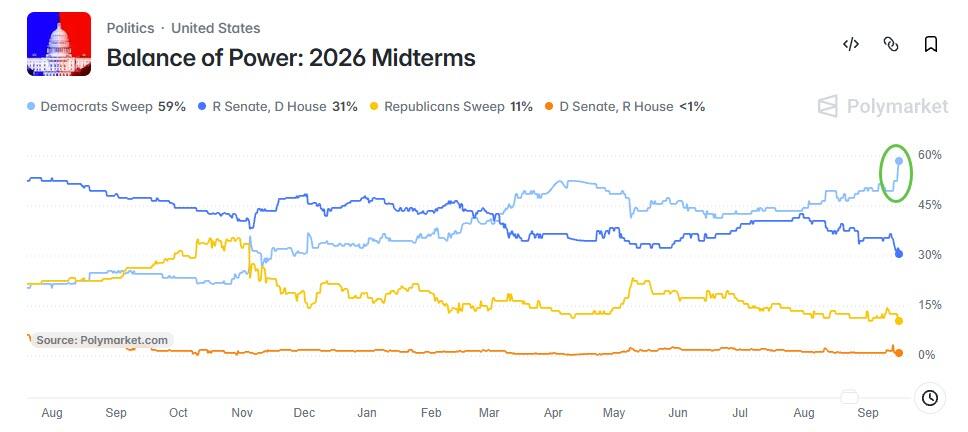
For this election, Kapteyn cited betting odds close to 50-50 for Democratic control of the Senate, asserting there was little reason to expect less uncertainty or volatility in the months ahead.

Bank of America's Michael Hartnett expects a market rout if Democrats sweep. Traders worry that Democrats have already signaled regulatory safeguards and data center moratoriums that could stymie the AI bubble. We detailed these threats in a note titled "If Dems Win The House: Data Centers, Nuclear, Venezuela Oil Deal Likely Targets."

Meanwhile, JPMorgan's Andrew Tyler recently shared his base-case with clients: Across the 23 midterm cycles since 1934, the sitting president's party has lost roughly 27 House seats and about 3 Senate seats on average. Applied to a 218-seat Republican House majority and a 53-47 Senate, history says Democrats take the House and Republicans hold the Senate. And while betting markets give Dems an 85% chance of taking back the House, the chance Republicans keep the Senate is a very tight 53% according to Kalshi. 

Polymarket suggests the market is pretty sure the Dems will sweep... 

Kapteyn added more color on equity vol trends: 

The S&P's performance mirrors this volatility pattern. During midterm election years, the S&P 500 has typically declined between late August and early October, but by March of the following year it has recovered and delivered an average return of roughly 14% (with a median return of 16.4%).

The only exceptions were 1978, during the inflation shock, 2002, following the tech bubble burst, and 2018, amid trade-war tensions and Fed tightening. By contrast, the average return over the same period in other years is less than 5%. With betting odds of Democratic control of the Senate still close to 50-50, there is little reason to believe uncertainty (and volatility) will be lower this year than in past midterm election years

Kapteyn then questions: "The calm before the storm?" 

* * * Perfect EDC flashlight...

Tyler Durden Wed, 09/16/2026 - 15:05

US Announces South Africa Visa Curbs Citing Racism Against Afrikaners

Zero Hedge -

US Announces South Africa Visa Curbs Citing Racism Against Afrikaners

Authored by Troy Myers via The Epoch Times,

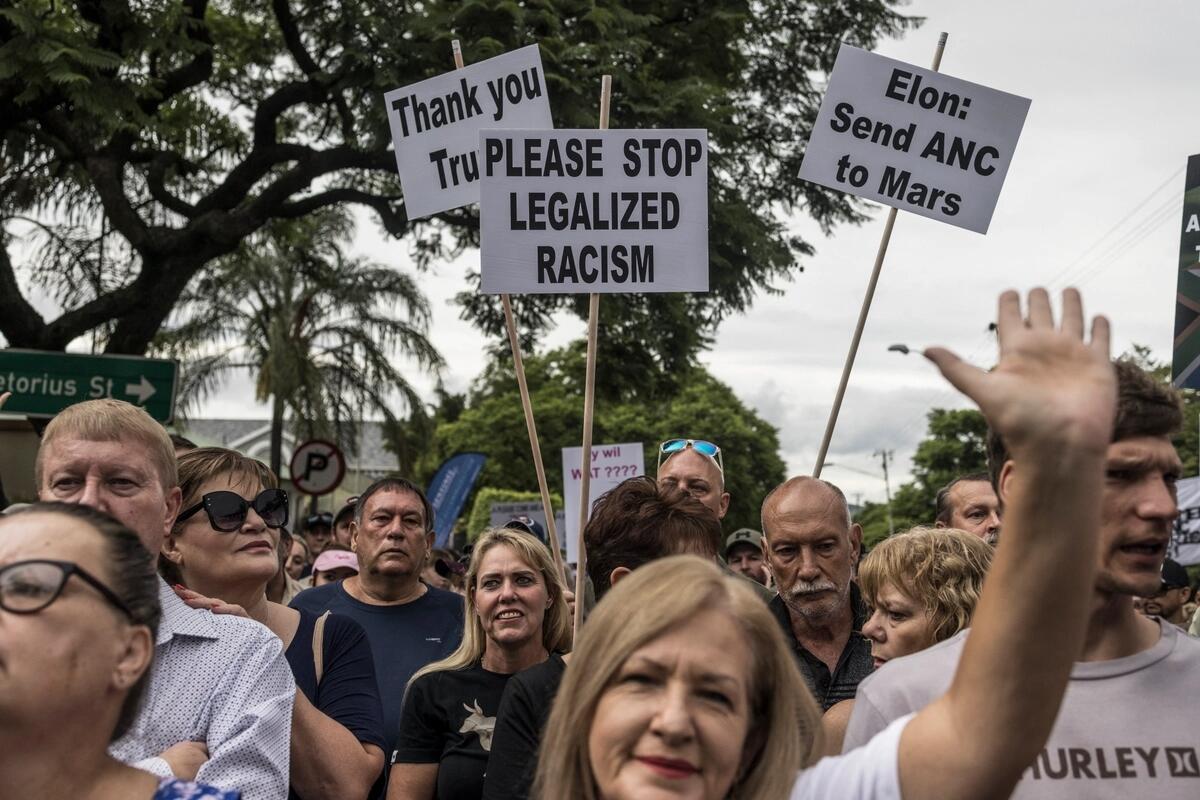
The U.S. Department of State announced Tuesday new visa restrictions against some foreign nationals in South Africa who are alleged to be involved in discrimination and incitement of violence against minority groups in the country.

A State Department news release said the policy will target any individual involved in racially motivated crime, uncompensated land seizures, government-sponsored discrimination, and race-based legislation against the Afrikaner community, a white South African group of Dutch, German, or French descent, and any other minority ethnic or racial groups in the nation.

U.S. President Donald Trump has alleged on several occasions that a "white genocide" is happening in South Africa, which the country's President Cyril Ramaphosa has denied.

"As [Trump] has made clear, the South African people are being failed by a government that is destroying its economy through an obsessive pursuit of racial grievance against the Afrikaner minority," State Secretary Marco Rubio wrote on X.

"The South African government has consistently failed to adequately address rural crime, violent and dehumanizing rhetoric, and race-based discriminatory policies against Afrikaners and other minority populations."

Rubio added that the alleged behavior will not go unchecked and that actions against minority groups in South Africa undermine peace, economic stability, rule of law, and are incompatible with the foundations of America's foreign policy.

"Those responsible for these injustices have no place in the United States," Rubio said. "We once again strongly urge the South African government to quickly address these egregious actions."

The state secretary referenced Trump's executive order, titled Addressing Egregious Actions of the Republic of South Africa, signed in February 2025.

That directive pulled $440 million in yearly funds that went to South Africa over similar concerns.

The executive order highlighted Ramaphosa's signing of the Expropriation Act, which is facing a legal challenge. Trump said the legislation enabled the government to seize Afrikaners' agricultural property without compensation.

"The United States shall promote the resettlement of Afrikaner refugees escaping government-sponsored race-based discrimination, including racially discriminatory property confiscation," Trump said in his order.

The president directed the State Department and Homeland Security to prioritize humanitarian relief, including admission and resettlement, for Afrikaners.

On May 12, dozens of Afrikaners arrived in the United States after they were granted refugee status.

About a week later, Ramaphosa flew to Washington, where the two world leaders held a tense meeting in the Oval Office.

Trump confronted Ramaphosa with allegations of mass violence against Afrikaners, and the South African leader denied that any killings or violence are taking place.

In a dramatic moment, Trump instructed his staffers to "turn the lights down."

He showed a several-minute-long video showing crowds at rallies calling for white South African farmers to be shot, which was followed by scenes of what Trump described as burial sites for Afrikaners.

"These are burial sites right here. Burial sites of over 1,000 white farmers," Trump said, speaking over the video. "Each one of those white things you see is a cross."

Ramaphosa looked away from the video, said he'd never seen it before, and wanted to know where it was filmed.

"I mean, it's in South Africa," Trump responded.

Relations between D.C. and Pretoria, the South African capital city, have been at an all-time low, as Trump and other administration officials criticized the country's policies. Trump has also imposed high tariffs on South Africa.

Before Ramaphosa's visit to the White House last year, Rubio skipped a G20 meeting hosted in Johannesburg, South Africa.

"South Africa is doing very bad things," Rubio wrote on X, explaining his absence. "Using G20 to promote 'solidarity, equality, & sustainability.' In other words: DEI and climate change. My job is to advance America's national interests, not waste taxpayer money or coddle anti-Americanism."

Tyler Durden Wed, 09/16/2026 - 14:45

Watch Live: Fed Chair Warsh Explains Why He Hiked Rates Into Stagflation

Zero Hedge -

Watch Live: Fed Chair Warsh Explains Why He Hiked Rates Into Stagflation

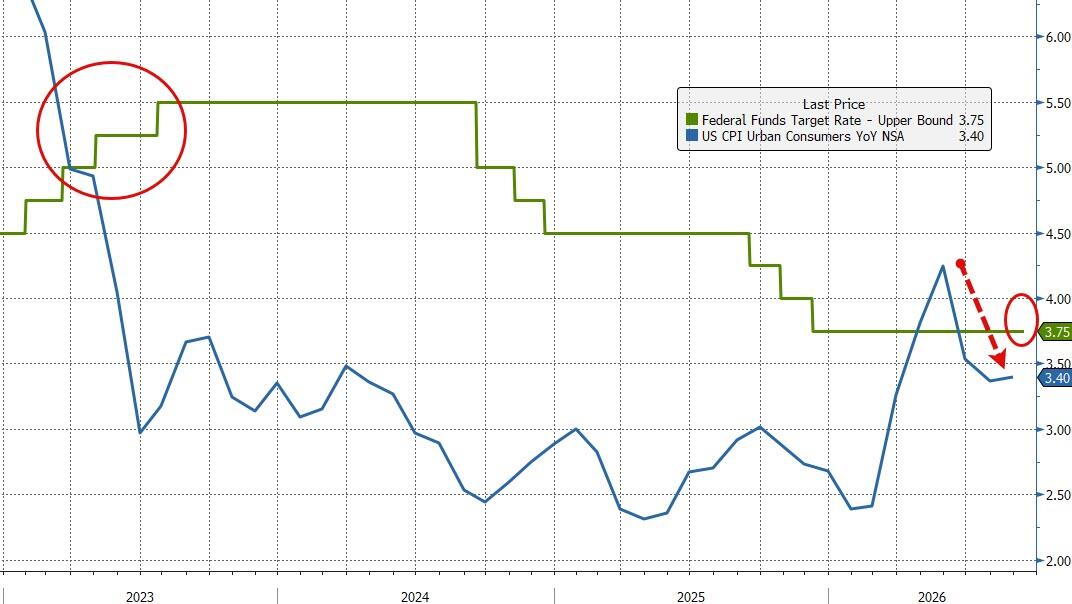
The FOMC just (unanimously) hiked rates for the first time since July 2023 despite recent inflation prints slowing...

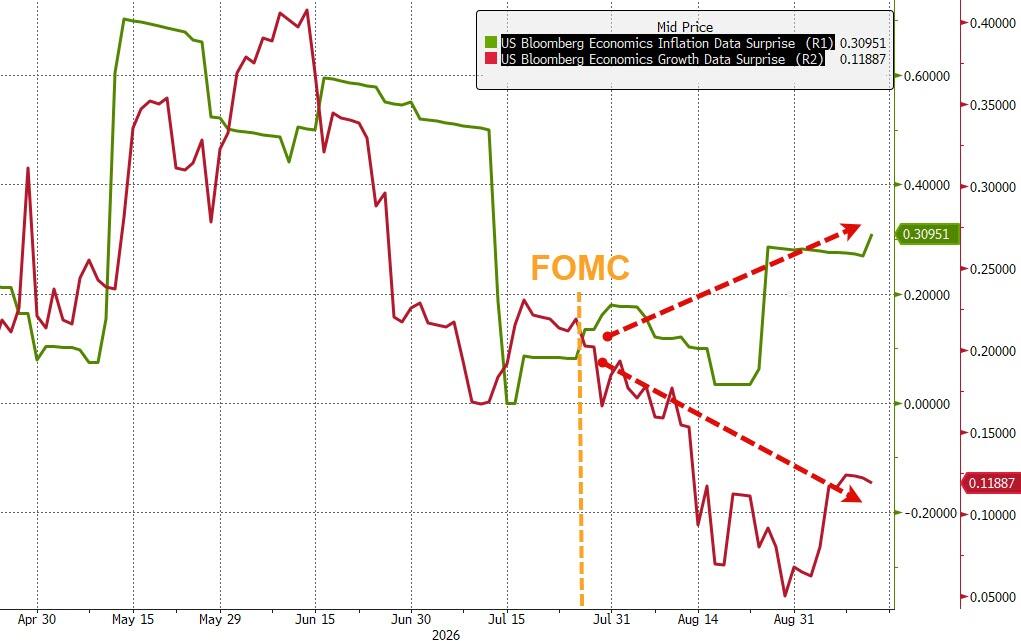
Additionally, recent macro surprises are clearly signaling stagflation - the central banker's nemesis...

So, a hike for credibility... but Warsh’s biggest challenge will be communicating his outlook without reverting to forward guidance, even as markets seek clarity on whether today’s likely move is one-and-done, or the start of a broader tightening cycle.

With investors forced to extract more signal from his language, the press conference carries outsized front-end risk.

In a note to clients, BMO notes two-year yields have moved an average 14bps across his five public appearances as chair so far.

The big question for today of course, assuming they do hike, is whether this is likely to be a “one and done” move.

We haven’t seen one of those this century so far.

Jim Reid at Deutsche Bank catalogues that there were a few of those in the 1980s and 1990s.

Outside of them, "the shortest cycle on record remains the four hikes of 1986-87."

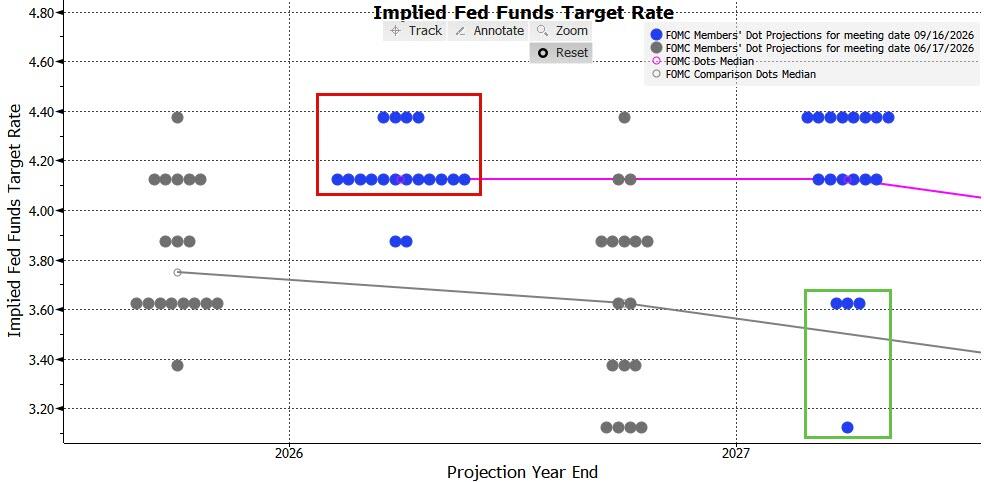
While all the talk is about the 'unanimous' decision today with the great majority of dots signaling at least one more hike this year... The Fed is extremely divided next year with four members see at least 2 rate-CUTS (policy error much)...

Quick reminder:

  • In 2024, the Powell Fed cut 50bps 2 months before the presidential election with core CPI at 3.3%

  • In 2026, the Warsh Fed hikes 25bps 2 months before the midterms with core CPI at 2.4%

Will Trump comment?

Watch the FOMC press conference live here (due to start at 1430ET):

Tyler Durden Wed, 09/16/2026 - 14:25

At The Money: Investing in Founder-Led Companies

The Big Picture -


At The Money: At The Money: Investing in Founder-Led Companies Michael Monahan (September 16, 2026)

How can ordinary investors access funds of companies led by founders? Enter the Founders 100 ETF (FFF).

Full transcript below.

~~~

About this week’s guest:

Michael Monahan is a partner and portfolio manager of the Founders 100 ETF (FFF). He’s been a Wall Street analyst, a private market investor, a tech startup CEO, and a public equity portfolio manager.

For more info, see:

Personal Bio

Professional/Personal website

LinkedIn

~~~


Find all of the previous At the Money episodes here, and in the MiB feed on Apple PodcastsYouTubeSpotify, and Bloomberg. And find the entire musical playlist of all the songs I have used on At the Money on Spotify


Transcript: At the Money: Michael Monaghan


BARRY RITHOLTZ: Should you invest in companies led by founders? Peter Thiel’s VC Founders Fund has over $20 billion and produced excellent returns. How can ordinary investors get access to funds of companies headed by founders? To help us unpack all of this and what it might mean for your portfolio, let’s bring in Michael Monaghan. He is a partner and portfolio manager of the Founders 100 ETF, stock symbol FFF. He’s also been a Wall Street analyst, a private market investor, a tech startup CEO, and a public equity portfolio manager in his career. So, Michael, let’s just start with the basics. What’s the central thesis behind the Founders 100 ETF? Why should founder-led companies outperform even after they’ve become large public companies?

MICHAEL MONAGHAN: Barry, thanks for having me. The data shows that founders outperform by about 3X. We looked at 11,000 stocks over 30 years, and on average, founder-led companies grow 4% greater than the S&P.

BARRY RITHOLTZ: Wow. So let’s stay focused on that 3X. I believe that was Bain research, that founder-led companies tend to outperform other companies. What is it that drives that three times outperformance? Is it that founder-led companies tend to be heavily represented in the technology sector? Is it a function of age or size, or is this just survivorship bias?

MICHAEL MONAGHAN: We’ve got companies led by founders all across the economy, so it’s not just a concentration in technology, although there are a lot of technology companies that are led by founders. We don’t think it’s survivorship bias. We think that founders bring something really unique. They have the vision to see where to go. They have the execution to execute that plan they’ve envisioned. They have the charisma to build a big team around them, and they’ve got the grit to get through the hard times, combined with the fact that they think in decades, where a board-hired CEO is just trying to make the next quarter and the next PowerPoint presentation for the board.

BARRY RITHOLTZ: How much of this is due to the fact that, hey, if you’re going to start a new company from scratch, by definition you’re a risk-taker. How much of the outperformance of founder-led companies is simply just embracing that higher tolerance for risk?

MICHAEL MONAGHAN: I don’t know if that’s the factor that’s showing it. I think if you dig in, a lot of these guys are successful because they de-risk all along the path, right? So if you listen to, say, a Marc Andreessen, he talks about at the zero stage and the one stage and the two stage, it’s all about de-risking the problem as you move along. So I would gently say that I think founders de-risk their business even more than non-founders.

BARRY RITHOLTZ: Really interesting. And you yourself are a founder. Your startup was Beartooth Radio. It didn’t necessarily find an exit, but I’m curious, how did that experience of standing up a company from scratch affect your view of founder-led firms?

MICHAEL MONAGHAN: I think it completely reframed how I think about building a company. I had spent the first 15 years of my life working for great companies. I worked at Goldman Sachs, I worked at Sanford Bernstein. But there’s a big difference between working at a world-class organization where you fit into their system, and building your own system from zero to one. I was fortunate enough to get exposure to some of these really good technology founders, and just saw how differently they thought, how passionate they were, how they brought vision that corporate managers didn’t have.

BARRY RITHOLTZ: So let’s zoom in on that. How do you define a founder? Must the individual have actually started the original enterprise, or do you include anyone who perhaps acquired or reinvented or merged with or effectively refounded an already existing company?

MICHAEL MONAGHAN: So we define founder-led as the original founder — that’s the person who started the company — still running it, most often as the chief executive officer. Occasionally it’ll be the chief technology officer, or in the case of a medical or scientific company, it could be the chief medical or chief scientific officer. So it’s the chief officer running the company day-to-day. We looked at the data. Board member doesn’t have the efficacy we want. Chairman doesn’t have the efficacy. It’s only if the founder’s sitting in the seat every day running the company.

BARRY RITHOLTZ: And some classifications are really straightforward. Obviously Michael Dell founded Dell Computers, Zuckerberg at Facebook. What do you do with the more ambiguous cases? And I think probably the biggest one is Elon Musk, who was an investor, not an original founder of Tesla. There are debates about the merger with PayPal. We could talk about SpaceX. How do you draw the lines there? You’re really less interested in the technical founding issue than the driving animus of the company. Is that a good way to distinguish it?

MICHAEL MONAGHAN: I think that’s fair. We have a rigorous process to decide, and you and I can hit a couple of edge cases. But we look to see who the original founder is. Most of the time it’s clear-cut. Sometimes it’s not, and then we have to dig in. We have to say, who does the company define as the founder? Elon’s a great one to examine, because for some reason there’s controversy as to whether he’s the actual founder. We dug in and did the hard work. The company defines him as the founder, and in fact it was either 2012 or 2014, there was a court case where this was actually settled, and Elon Musk is one of the five original founders of the Tesla Motor Company.

BARRY RITHOLTZ: I would modify that to say Elon wasn’t the original founder, but once he took over, he so totally revamped the company that it looks nothing like the prior enterprise. So is there any reason to split hairs with that? But same sort of thing with PayPal or SpaceX. How do you think about those two?

MICHAEL MONAGHAN: So I think SpaceX, he clearly was the founder. I don’t think anyone else lays claim to it, right? PayPal was the merger of a couple of entities. It was the original X entity that Elon was building merged into Peter Thiel’s company. But there are edge cases. Berkshire Hathaway is a great example. I don’t think anyone would doubt that Mr. Buffett was the founder of Berkshire, but he bought a failing textile company as part of a massive acquisition, and that company that acquired that and many other things — he’s the founder of. And Monster Beverage is kind of the same way. They acquired a juice company, but it was really the energy drink company and the other acquisitions they made that is the founding of the Monster Beverage company.

BARRY RITHOLTZ: Yeah, that makes a whole lot of sense. So amongst your current holdings, you have founders like Alex Karp of Palantir, Larry Fink at BlackRock, Marc Rowan at Apollo. Each of those companies had multiple co-founders. How relevant must the individual who remains be to the company, to its strategic vision — to really be its dominant force?

MICHAEL MONAGHAN: You know, our test is: were they an original co-founder? And we often look to the company to define it. Most of the companies in their origin story or their history will list who the original co-founders are. As long as at least one remains as an executive, that meets our test.

BARRY RITHOLTZ: So now we take the list of however many founder-led companies there are — I think it was 11,000. You’re going to break that down to a list of 100. What are the underlying criteria that determine which of those thousands and thousands of founder-led companies end up in the 100 that are in FFF?

MICHAEL MONAGHAN: Really great question. So we looked at 11,000 stocks over 30 years, and during that 30-year time period, there are about 800 founder-led stocks at any one time. So in the current market, there are about 800 founder-led stocks. From there, we look at the 200 largest by market capitalization. And then my co-founder and I come from a fundamental background, especially her. She’s a classically trained Columbia Business School value investor. We build a valuation model, using some factors, to pick what we then believe are the 100 best out of the 200 largest.

BARRY RITHOLTZ: Interesting. And I’m looking at your largest holdings: Meta, Nvidia, Oracle, Palantir, Dell, Arista, and CrowdStrike. A lot of this is a heavy overlap with technology, AI, high growth, big cap companies. Why go with a founders fund instead of just a simple Nasdaq 100?

MICHAEL MONAGHAN: We have very different exposures than the Nasdaq 100. We’ve got about 80% active share versus the Nasdaq 100. We’ve got much higher exposure to founders — 100% founders versus about 20% of the Nasdaq 100 — and it’s a different portfolio construction. The Nasdaq 100 is limited to only Nasdaq stocks, and there’s obviously incredibly high growth in tech and out-of-tech stocks on the NYSE. And we feel like we’ve got a little better spread across the economy. Right now, the Nasdaq 100 is 30% exposed to semiconductors, the S&P at 20, and we’re only at 10. So we do have exposure to technology, but we really are bent across the entire curve. We’re not substantially overweight versus, say, the S&P. We are slightly overweight, but I don’t think we’re massively overweight versus the S&P.

BARRY RITHOLTZ: Yeah, I was looking through your holdings and I saw a lot of industrials and energy and financials, which you don’t necessarily see in the Nasdaq 100. But I’m glad you mentioned the 80% active share. So many ETFs I look at end up being closet indexers. This is really a very concentrated portfolio, with the top 10 holdings really accounting for a big chunk of your exposure. How much of what drives the performance of this is really just a conviction strategy — a concentrated portfolio with a long tail of sub-1% holdings? Tell us about the concentration, and also tell us, why do you have the rest of these small holdings? They’re almost like placekeepers to keep an eye on.

MICHAEL MONAGHAN: So we run a modified market cap weighting. That is, we take the market cap and we allow that to define how much position size we’re going to take for each position. The reason we modify it is we put a hard cap of 7.5%. So we rebalance quarterly — every quarter we reset the portfolio. We don’t take any single position more than 7.5%, because we want to have some diversification in the portfolio. That’s where we come up with the weightings. And the reason we end up with some of these smaller weights at the bottom, it’s just defined by where they are on a free float market cap.

What I would tell you, Barry, it’s really interesting. There’ll be days I wake up, I look at our portfolio, our top holdings are down, and the portfolio’s actually up, because those other 75 to 80 stocks that make up the balance — 50% — they drive sometimes when the big guys aren’t working. So it’s sort of just — we allow the market capitalization to set our position sizes.

BARRY RITHOLTZ: All right, so now we know the criteria for selection, the criteria for weighting. Let’s talk about the most challenging aspect of managing a portfolio: the sell discipline. What leads you to taking a company out of the portfolio? Is it just something as simple as the founder leaving, or do you also run through operating parameters and other fundamentals? And when suddenly you’re starting to think, “Hey, this company doesn’t have the growth prospects we were hoping for,” is that a basis for ejecting them, or is it a variety of things?

MICHAEL MONAGHAN: The main reason we would sell a stock is if the founder leaves. So in the prospectus, we state that if a founder announces their resignation, we will sell within 90 days of that announcement. So we don’t wait for them to actually leave — we would sell on the announcement. The second way a stock would get sold is if the fundamental overlay flags a condition that says to sell the stock. One of the ways we like to describe the fundamental overlay — it was built by my partner — it’s really looking for what she calls burnt pizza crust. We think all of our founders can make great pizza. We don’t want to tell them whether to make pepperoni or margherita. The factor looks and it says, are one of these crusts getting burnt? And if so, we’ll slide it out and bring in the next best company.

BARRY RITHOLTZ: Really interesting. So to wrap up: if you’re interested in a venture fund like Peter Thiel’s Founders Fund, but you don’t have a quarter billion dollars to gain access to it, consider the Founders 100 ETF, stock symbol FFF. Be aware of the fact that this is a concentrated portfolio with a high active share, and it may not perform similarly to the S&P 500 or the Nasdaq, but it is concentrated, and it focuses on companies being led by the original founders.

I’m Barry Ritholtz. You’re listening to Bloomberg’s At the Money.

~~~

Find our entire music playlist for At the Money on Spotify.


The post At The Money: Investing in Founder-Led Companies appeared first on The Big Picture.

Fed Hikes Rates For First Time Since July 2023, Signals 1 More Hike In 2026

Zero Hedge -

Fed Hikes Rates For First Time Since July 2023, Signals 1 More Hike In 2026

Tl;dr: As the market expected, The Fed hiked rates by 25bps (for the first time since July 2023) despite a trend lower in CPI over the last three months.

Today's decision was unanimous and the 'Dots' signal one more hike in 2026.

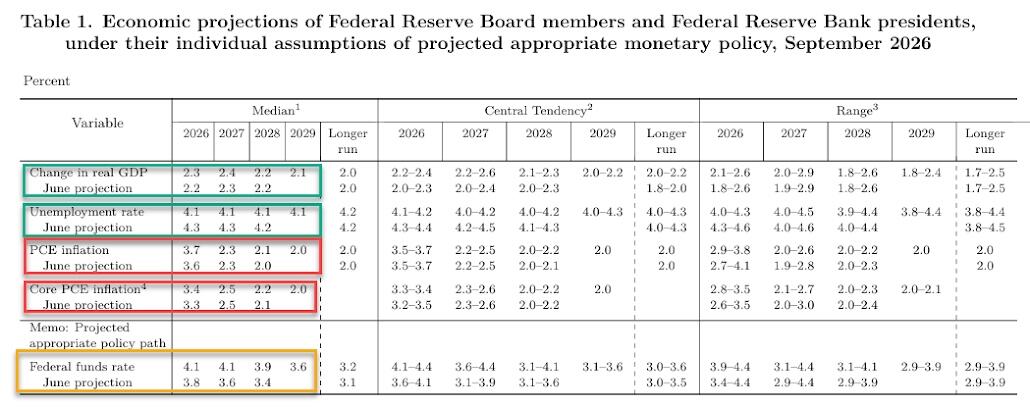
The Fed members increased their GDP outlooks, lowered their unemployment forecasts, but hiked their inflation outlooks...

The big question for today of course, assuming they do hike, is whether this is likely to be a “one and done” move.

Quick reminder:

  • In 2024, the Powell Fed cut 50bps 2 months before the presidential election with core CPI at 3.3%

  • In 2026, the Warsh Fed hikes 25bps 2 months before the midterms with core CPI at 2.4%

*  *  *

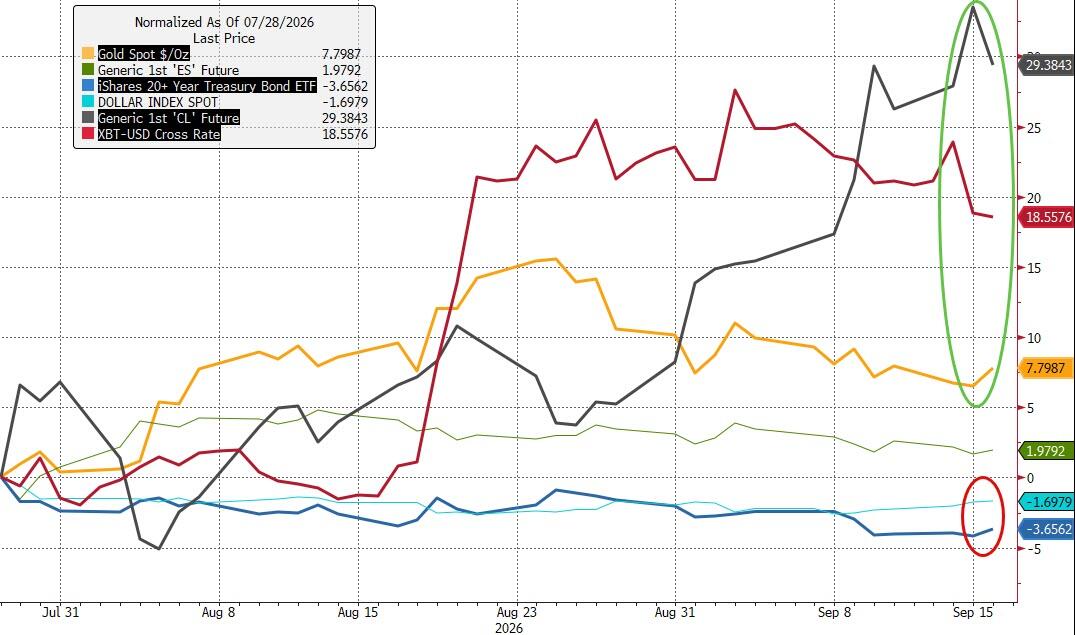
Since the last FOMC Meeting on July 29th, a lot has happened amid the supposed Summer doldrums, the dollar is lower while the anti-fiat trades (gold, bitcoin) and crude are all significantly higher with bonds the worst performers...

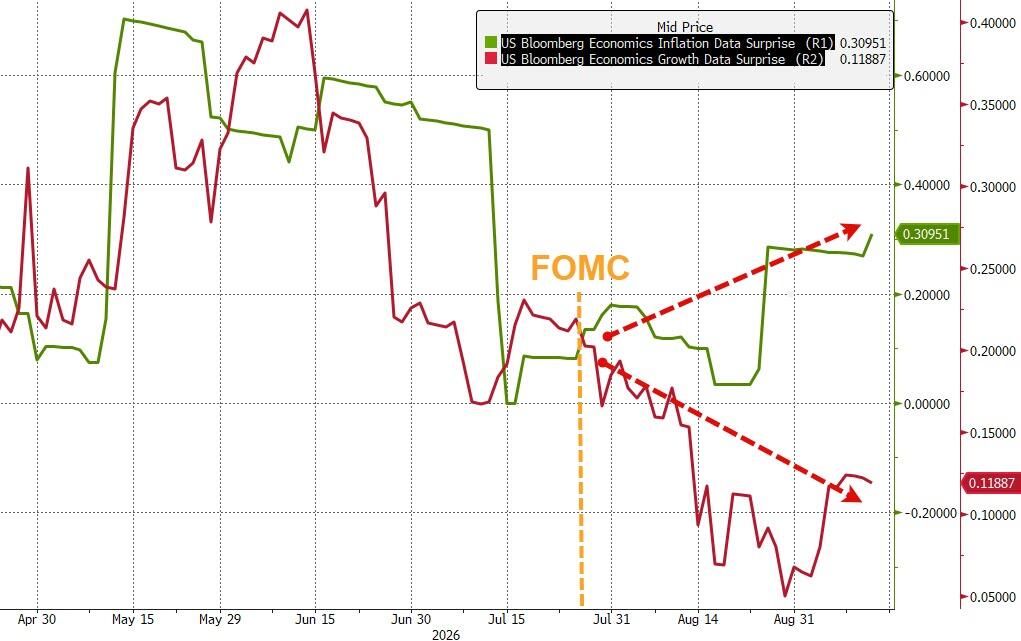
Stagflationary signals abound as inflation data has surprised to the upside while growth data has surprised to the downside since the last FOMC

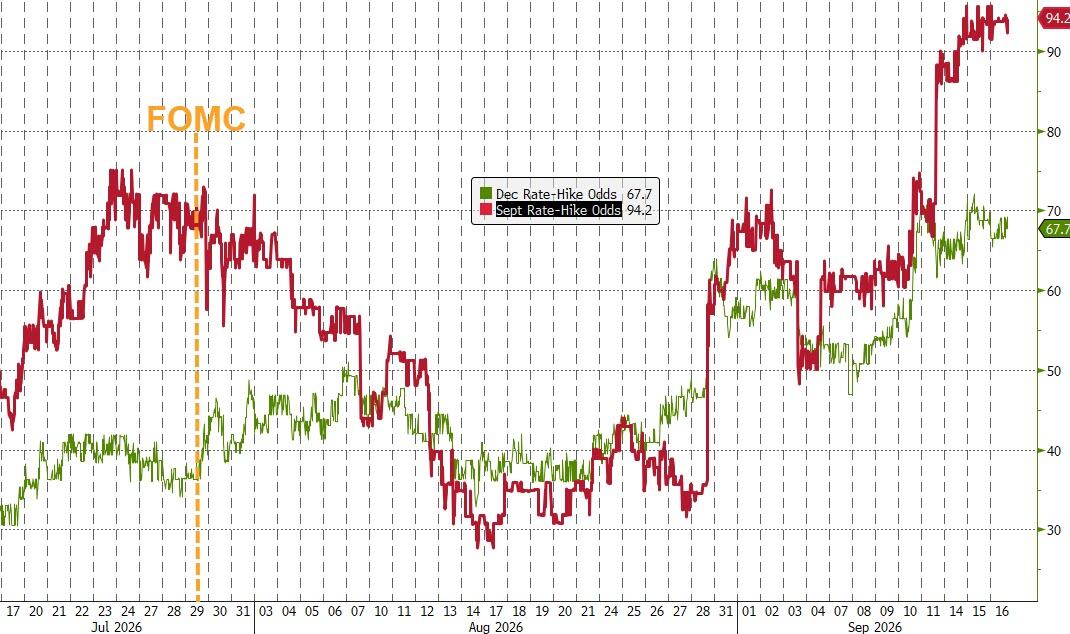
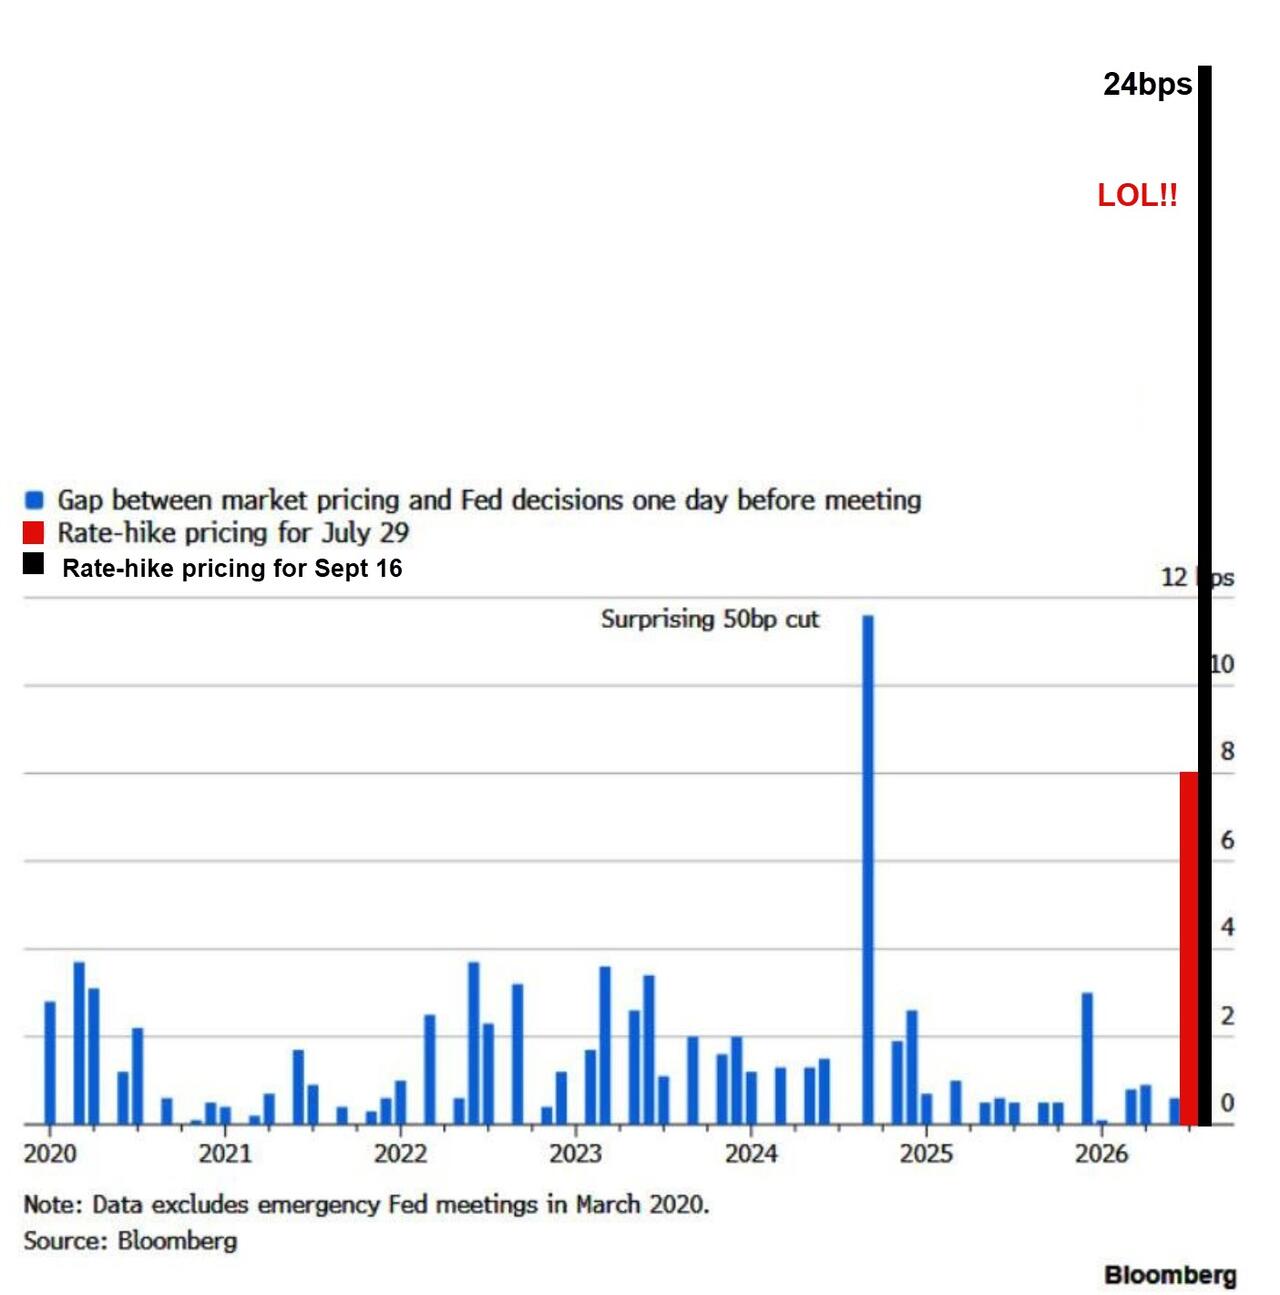
But, the market is all-in, betting on a 25bps hike today - 95% versus 70% at the last FOMC, with a lot of noise in between. Dec odds are up from 40% to 70%. The market is pricing in 3.5 hikes into September of next year as the peak of the cycle...

So, before we get the decision, putting things in context, if Warsh were to hold rates here, it would be BY FAR the greatest surprise The Fed has ever hit the market with...

The Fed has historically always gone when market pricing is this high. That’s on top of a substantial hawkish repricing that has recently taken two-year yields to their highest since 2024 and pushed the 10-year through 5% to levels unseen since 2007.

So, what did he do?

Statement

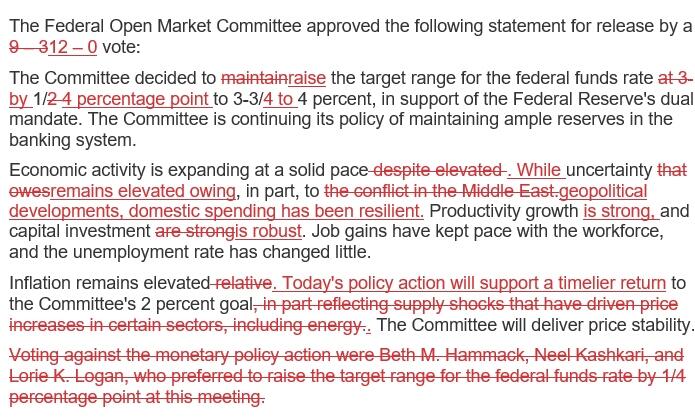
After three dissents (in favor of a hike) in July, the Eccles Building establishment appears to have won the tug of war against The White House, with The Fed hiking rates 25bps (as fully priced in by the market)

  • *FED UNANIMOUSLY RAISES BENCHMARK RATE 25 BPS TO 3.75%-4% RANGE

  • *FED: RATE HIKE WILL SUPPORT `TIMELIER' RETURN TO 2% INFLATION

Dots

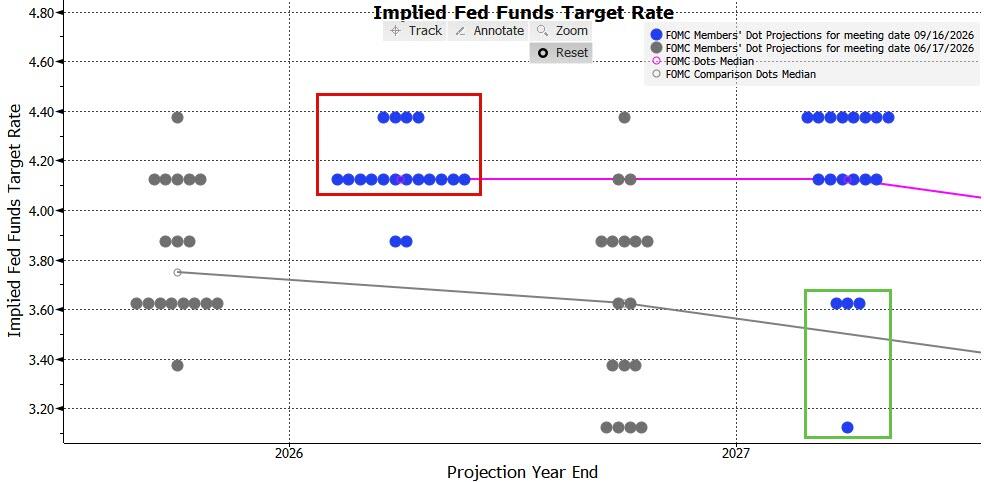
In June, 9 members saw at least 1 rate-hike in 2026:

  • 3 hikes - 1 (Jun)

  • 2 hikes - 5 (Jun)

  • 1 hike - 3 (Jun)

  • No rate change - 8 (Jun)

  • 1 cut - 1 (Jun)

Now in September, with 1 hike in the books, these are the number of hikes/cuts left in 2026

  • 2 more hikes - 4

  • 1 more hike - 12

  • No rate change - 2

  • No one sees rate-cuts

So the median dot suggest one more rate hike in 2026...

1 member sees four rate-cuts in 2027 and 3 see 2 cuts

  • 1 hike in 2027 - 8

  • No rate-change in 2027 - 6

  • 2 cuts - 3

  • 4 cuts - 1

Only 18 of 19 officials submitted their 'dots' with some suggesting Warsh himself did not contribute again.

SEP

The Fed members increased their GDP outlooks, lowered their unemployment forecasts, but hiked their inflation outlooks...

Full Redline

Key changes:

  • Addition of "domestic spending has been resilient"

  • Capital investment reduced from "strong" to "robust"

  • Adds that "Today's policy action will support a timelier return to the Committee's 2 percent goal"

The big question for today of course, assuming they do hike, is whether this is likely to be a “one and done” move.

We haven’t seen one of those this century so far.

Jim Reid at Deutsche Bank catalogues that there were a few of those in the 1980s and 1990s.

Outside of them, "the shortest cycle on record remains the four hikes of 1986-87."

Tyler Durden Wed, 09/16/2026 - 14:00

DOJ Accuses Russian Intel Ring Of Plotting Murder On American Soil

Zero Hedge -

DOJ Accuses Russian Intel Ring Of Plotting Murder On American Soil

In something that sounds straight from the plot of "Homeland" or the more recent CIA thriller "Lioness", the Trump administration has charged multiple members of Russia's intelligence services with running a "global assassination network" that targeted Kremlin critics.

The Department of Justice has newly revealed and alleged that one murder plot even took place on American soil over the summer.

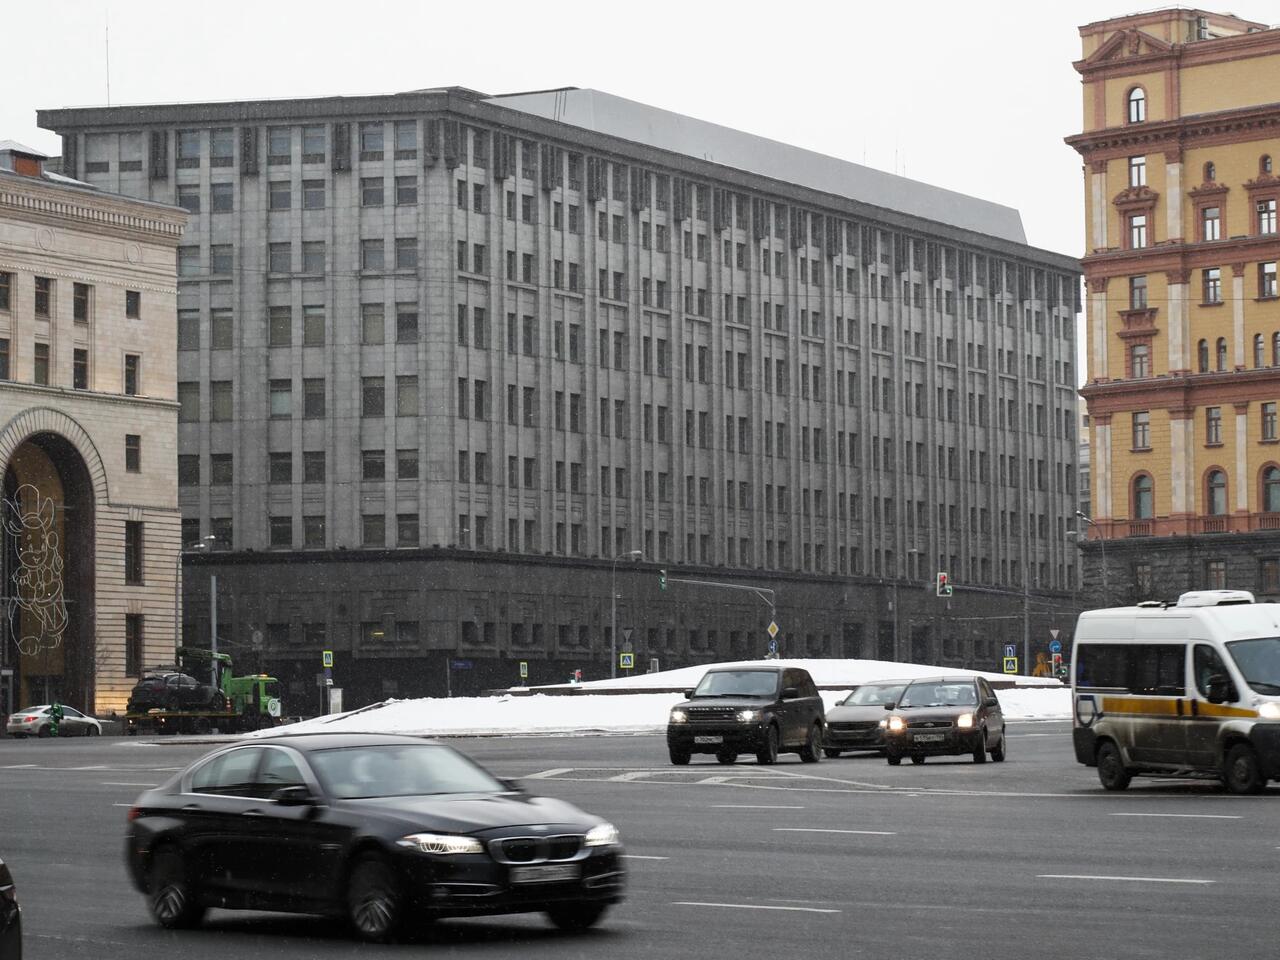
Russian FSB HQ, Moscow. Associated Press
The fugitives have been named but have not been apprehended, and are still at large. A murder-for-hire plot is detailed in an indictment which was unsealed Tuesday by federal prosecutors in New York.

The plot was never followed through on, but a Russian dissident is said to have been targeted, during which time a Brooklyn man was recruited by Cuban and Venezuelan individuals - both which were ultimately being run by a Russian intelligence handler - but the Brooklyn man is said to have gotten cold feet when asked to carry out an assassination.

The five defendants are all believed to live in Russia, and are part of what court documents call the "RIS Network," including a 63-year-old former Russian intelligence colonel named Yuri Khrameev, as well as his son Kirill.

According to a summary of the wild plot and allegations:

It marks the latest alleged attempt by a U.S. adversary to crack down on dissidents abroad, including in the United States and NATO-allied countries.

One of the murder-for-hire plots took place in July and August of this year, the indictment says. The Venezuelan operative and one of the Cuban operatives allegedly recruited a Brooklyn resident to take photos and videos of two locations associated with an unnamed Russian dissident, promising him $1,000 to $1,500 to carry out the "gravely serious work." Another $40,000 was offered to "eliminate" or "disappear" the target of the surveillance.

The operatives believed the Russian dissident lived in the Washington, D.C., area, Attorney General Todd Blanche told reporters at a briefing Tuesday.  The Brooklyn resident was willing to take photos, the indictment said, but expressed unwillingness to "do the other stuff" — as in, kill the dissident. The operatives then allegedly asked the Brooklyn resident if he knew of anybody else who was interested.

"Let me know as soon as possible because I have a chain and my boss has questions," one of the Cuban recruiters wrote, according to the indictment. "I have people in Mexico right now and they're delayed. I only need a response to know if someone can do the work. It doesn't have to be today or tomorrow just need to know if the[y] can."

Some skepticism is of course always warranted when dealing with official US claims related to what Russian intelligence is up to.

For example, the latter part of the above - where a foreign agent reportedly broadly asks his asset whether he knows anyone else that can do the killing - seems amateurish, dubious and needlessly high risk.

The Kremlin has on Wednesday rejected the claims, describing that there's simply no evidence to even warrant a serious explanation:

Until "any plausible evidence" emerges, there is no point in commenting on statements by the US Department of Justice about the exposure of a number of individuals allegedly working for Russian intelligence, Kremlin Spokesman Dmitry Peskov told reporters.

"Until we have heard and seen any credible evidence and arguments based on something tangible, we do not consider it necessary to comment on this news," he noted in response to a request to comment on a statement by US Attorney General Todd Blanche, who said that a number of individuals working for Russian intelligence had been exposed in the country.

Washington has over recent years lobbed significant accusations of espionage and nefarious recruitment schemes against Russian intelligence, especially since the Ukraine war began. Russian intel seems much more active in Europe, however.

The other country which tends to get named in these reports is Iran. The Trump administration has even accused the IRGC of its own assassin-for-hire plot against the president himself.

* * * Add two to cart

Tyler Durden Wed, 09/16/2026 - 13:55

Democrats Still Don't Know How To Read Charts

Zero Hedge -

Democrats Still Don't Know How To Read Charts

Authored by Matt Margolis via PJ Media,

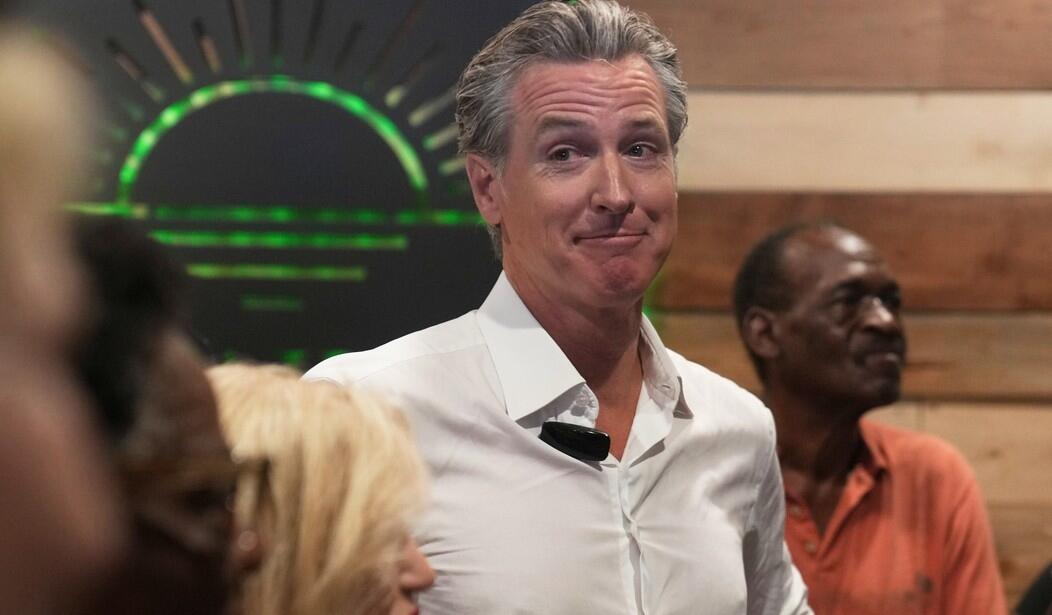
Democrats can be unintentionally hilarious sometimes. Gov. Gavin Newsom (D-Calif.) reposted a chart on X Tuesday claiming housing prices are "the most unaffordable in history," and that it was Trump's fault.

There was just one huge problem.

The chart Newsom shared showed that the housing affordability gap actually widened during Joe Biden's presidency, and X users noticed almost instantly, flooding his replies with screenshots of the very data he'd just posted as though it helped his argument. It didn't take long for the pile-on to turn Newsom's own post into a meme about his reading comprehension.

But the funny thing about it is that Democrats keep doing this. In July 2025, the Democratic National Committee posted a chart that they thought proved grocery prices were spiraling out of control in Trump's second term.

The chart told a different story. It showed a huge spike under Biden. The DNC had unwittingly undermined its own attack on Trump. Social media users mocked the party within hours, dissecting the chart line by line, forcing the DNC to quietly delete the post... not that that stopped us from making fun of them anyway.

Then came Sen. Bernie Sanders (I-Vt.), who spent the Schumer Shutdown standoff in October 2025 defending Obamacare subsidies. In the process, he put up a chart on X arguing for expanded tax credits. What the chart actually showed was health care costs more than doubling since 2000, climbing at a steady clip both before and after Obamacare passed, proving that Obamacare had failed to slow down the rising costs of healthcare, let alone reduce it.

Costs have never declined, flattened, or stabilized since Obamacare took effect, and every subsequent "fix" failed to make coverage "affordable."

And then Sen. Amy Klobuchar (D-Minn.) picked up the baton in late November 2025. She claimed in a post (with a supporting chart) that power bills had surged 11% under Trump and blamed him for rising past-due balances.

The problem with her claim was that the utility rate spike she referenced happened under Biden.

X users called her out quickly and spent the rest of the day passing around corrected versions of her own chart.

Are you seeing a pattern here? Democrats and charts - they just don't mix.

The funny thing is that I'm sure they'll keep trying. They think they can make an accusation accompanied by a chart, and it looks authoritative and true. In the end, they just prove how stupid they are.

Tyler Durden Wed, 09/16/2026 - 13:25

Two Robinhood Engineers Accused Of Making $50,000 By Front-Running Crypto Listings

Zero Hedge -

Two Robinhood Engineers Accused Of Making $50,000 By Front-Running Crypto Listings

Federal prosecutors have accused two former Robinhood engineers of turning their access to the company’s crypto plans into personal trades, according to Bloomberg.

Hefu Chai, 36, and Huaisong Xiang, 30, are accused of learning in advance which digital assets Robinhood intended to add to its platform. Rather than simply keeping that information inside the company, prosecutors allege they positioned themselves in derivatives tied to those tokens before the news reached the public.

Bloomberg writes that the trades were placed through Hyperliquid, a decentralized platform offering perpetual futures, and allegedly occurred over a period spanning 2025 and 2026. Authorities say both men walked away with more than $50,000 in profits.

Robinhood says the activity was uncovered internally and subsequently brought to the attention of regulators and law enforcement. Neither man still works for the company.

A Robinhood spokesperson said the firm has “zero tolerance for insider trading” and maintains controls governing employee access to sensitive information, including details surrounding upcoming crypto additions.

The criminal cases are now moving through federal court. Xiang was released on a $50,000 bond after a judge declined prosecutors’ request to keep him detained over concerns that he might leave the country. His attorney, Robert Stahl, says Xiang denies wrongdoing and plans to contest the case. Chai had not publicly commented on the allegations at the time of the report.

And so crypto continues its remarkable technological achievement of recreating virtually every questionable activity from traditional finance, only faster, with more leverage and usually with a Discord server somewhere in the background.

Tyler Durden Wed, 09/16/2026 - 13:05

FBI Agent Wanted To Criminally Investigate Elon Musk, Email Shows

Zero Hedge -

FBI Agent Wanted To Criminally Investigate Elon Musk, Email Shows

Authored by Zachary Stieber via The Epoch Times,

An FBI agent pitched investigating Elon Musk for his work with the Department of Government Efficiency (DOGE), according to an email released on Sept. 15.

FBI agent Kevin Gounaud wrote in the Feb. 22, 2025, missive to a supervisor that he wanted to recommend opening a criminal investigation into the person or people at the Office of Personnel Management who approved transmitting an email to government workers about what they had done the previous week.

That person was conspiring with Musk "to violate government-wide security policy and transmit sensitive government information outside of a strict need to know," Gounaud said.

"Furthermore, Musk used a non-government system (Twitter) to relate information that allegedly was for official purposes," he said.

"In doing so, because he is monetized ... he likely generated income for himself based on Twitter's monetization and/or advertising revenues."

Gounaud compared Musk's action to how former Secretary of State Hillary Clinton used a private email server to conduct government business.

The FBI declined to take action against Clinton, determining she lacked criminal intent.

Gounaud said Musk also likely violated a federal law that bars executive branch employees from participating in government matters that impact their own interests.

"Happy to write the case opening and find a prosecutor (or at least try)," the agent told the supervisor.

He added later, "And no, I'm not kidding."

Gounaud could not be reached for comment.

Sen. Chuck Grassley (R-Iowa) released the letter as senators questioned FBI Director Kash Patel during a hearing in Washington.

Grassley said the email, along with other evidence from actions taken by additional agents, "undercut public statements by former FBI officials that agents don't get to pick their cases."

The FBI and Musk did not return requests for comment by the time of publication.

Patel told senators that the FBI has fired agents who were involved in certain probes, including collecting intelligence in a malfeasant manner.

"And in terms of criminal investigations that sprout from that, I can only comment on what's been public, but there are a number of ongoing investigations regarding this illegal conduct," he said.

Gounaud is no longer with the FBI, as of February, according to his LinkedIn page. He had been with the bureau since 2004.

Musk's time as a special government employee concluded in the spring of 2025, while DOGE formally shut down in July.

Musk has not been charged to date.

It was not clear whether Grassley has obtained other emails involving Gounaud, including any responses the latter received to his pitch for a probe of Musk.

A spokeswoman for the senator did not return contact following an inquiry.

Tyler Durden Wed, 09/16/2026 - 12:45

Apollo Puts A Multi-Trillion-Dollar Price Tag On America's Industrial Comeback

Zero Hedge -

Apollo Puts A Multi-Trillion-Dollar Price Tag On America's Industrial Comeback

Apollo’s head of thematic investing, Rob Bittencourt, says US reindustrialization is already “underway,” driven by efforts to reshore critical supply chains, rebuild domestic industrial capacity, expand data centers, restart the rearmament cycle, and power up the grid for the next evolution of the modern economy. 

Rebuilding the industrial base could require trillions of dollars in additional investment, Bittencourt explained. The effort reflects a broader push to reduce dependence on foreign suppliers, including China, in sectors where disruptions carry significant economic and security consequences, as previously learned during the supply-chain madness of the Covid era.

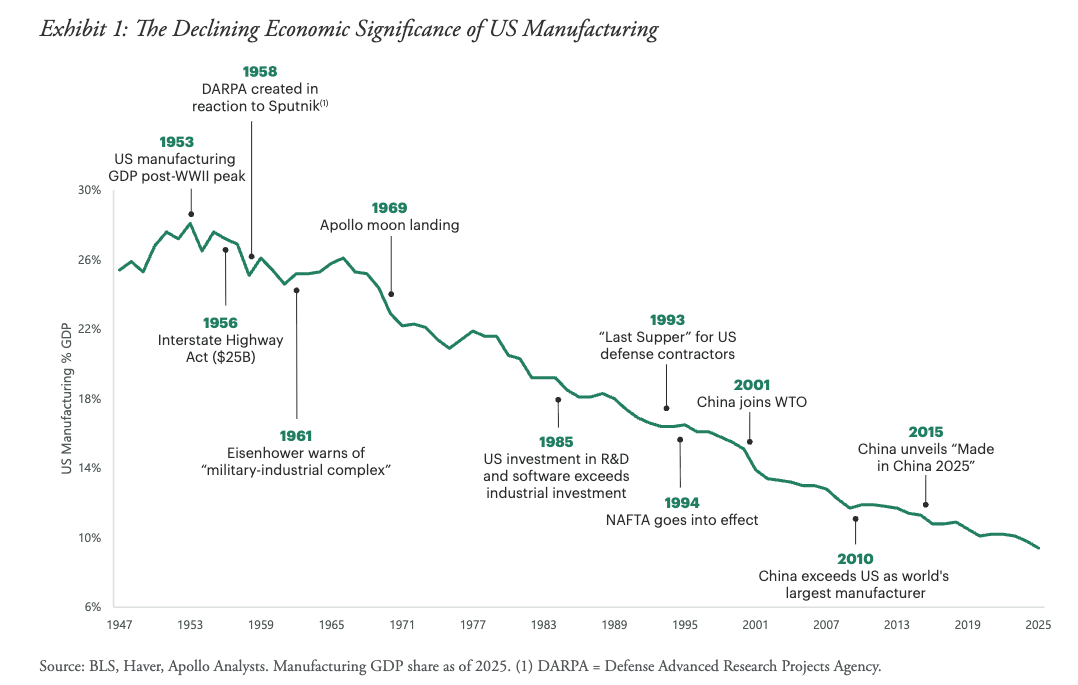
The Trump administration has made reviving domestic production a national priority. Manufacturing's share of US GDP has fallen from about 28% in the 1950s to an alarming 9%, as investment shifted toward services, software, and other asset-light activities. 

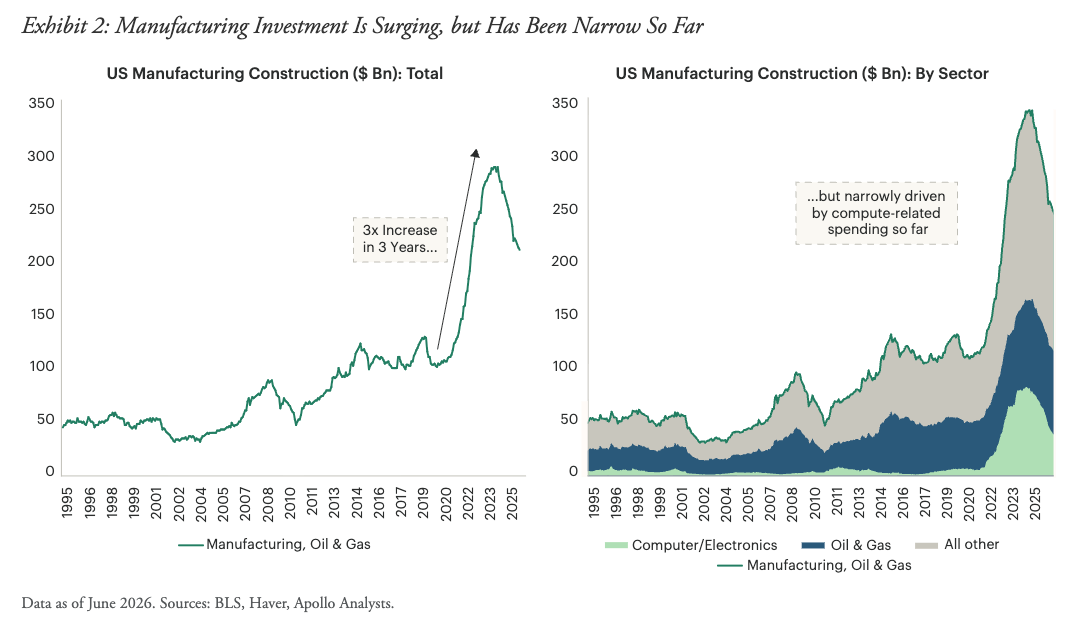
Semiconductor chip plants, data centers and supporting energy infrastructure are now attracting the most capital, but Bittencourt cautions that the recovery remains concentrated in tech-related industries. A broader manufacturing revival will require sustained investment flows, highly skilled labor and broadening domestic supplier networks. 

Bittencourt's price tag for restoring the combined US manufacturing and defense industry to its share of GDP in the 2000s would require $2 trillion in incremental investment. Returning to 1980s levels would require a staggering $6.5 trillion.

However, Bittencourt raised some important concerns about the reindustrialization underway, including elevated labor costs, lengthy permitting processes, shortages of skilled workers, and power constraints that threaten to delay projects or raise costs. 

Let's not forget that Democrats are hell-bent on imposing data center moratoriums and jeopardizing the whole buildout that has been a driver of economic growth. It has become increasingly odd that one political party would want to halt reindustrialization trends that rebuild the core. But given that Democratic Socialists of America leaders say, in their own words, that they want to destroy the nation from within, none of the moves that Democrats in their "big tent" party should be surprising. 

Back to Bittencourt, he said, "Reindustrialization should not be confused with the goal of complete economic self-sufficiency. In our view, the US is unlikely to rebuild every supply chain domestically, nor would doing so make economic sense," noting, "The more realistic objective is strategic self-sufficiency: increasing capacity where supply disruptions carry the greatest economic or national-security consequences. That points toward priority sectors including energy, semiconductors, aerospace and defense, rare earth minerals, pharmaceuticals, and the technologies that enable advanced manufacturing."

He continued, "What emerges, we believe, will look very different from the industrial economy of the 1950s: more modern, more automated, and more resilient, built to support the technologies and security priorities of the 21st century."

And Bittencourt concluded, "This rebuilding is part of a much broader Global Industrial Renaissance."

Professional subscribers can read the full note here at our new Marketdesk.ai portal. 

Tyler Durden Wed, 09/16/2026 - 12:25

Crude Slides On Report Saudis Could Restore Half Of East-West Pipeline Flows Within Days

Zero Hedge -

Crude Slides On Report Saudis Could Restore Half Of East-West Pipeline Flows Within Days

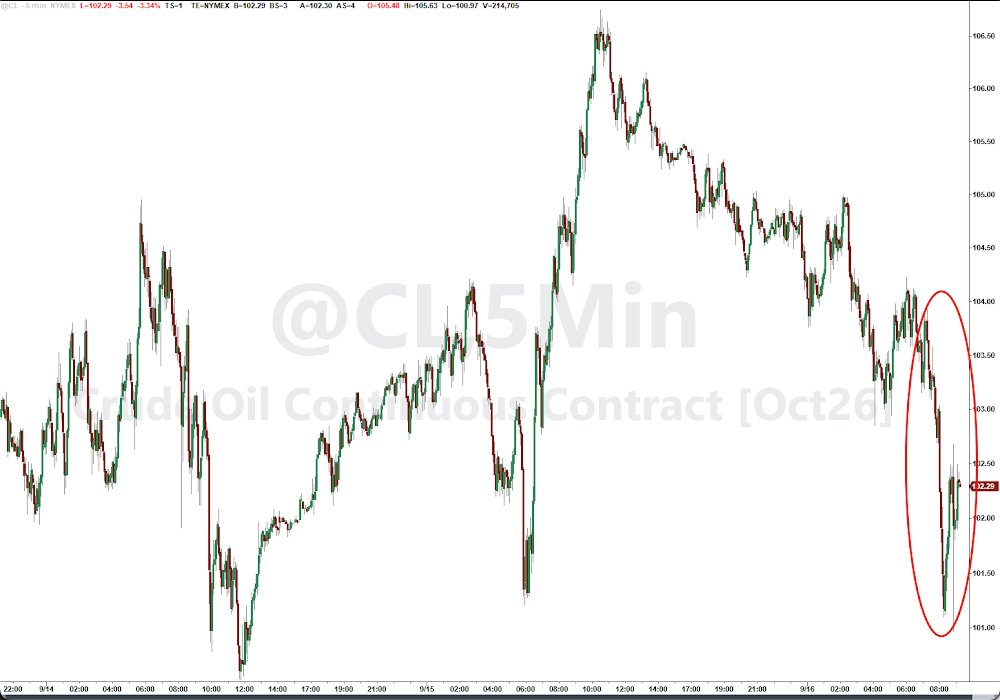
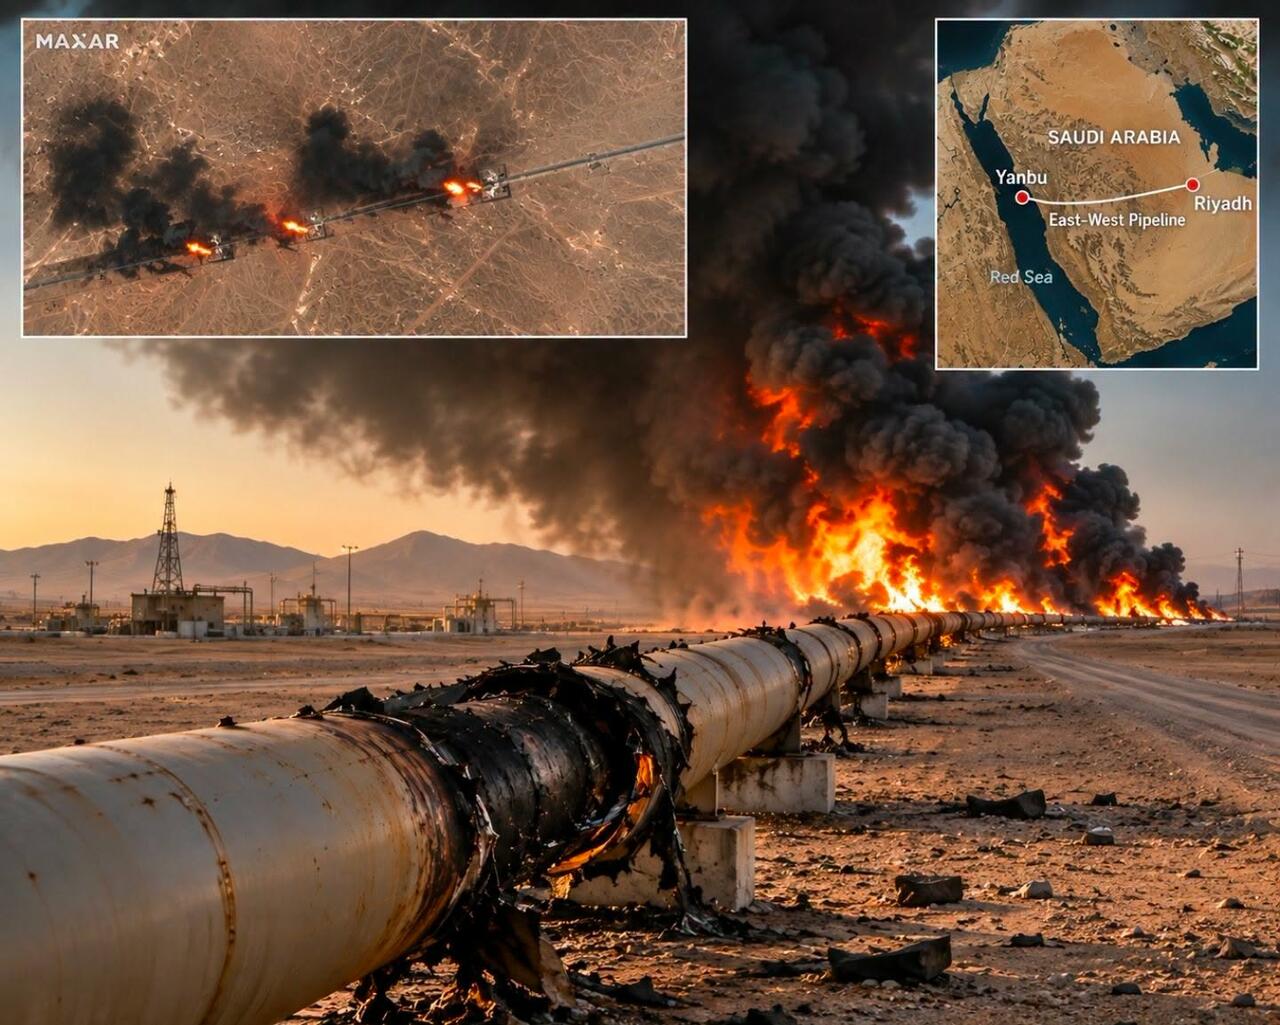
WTI futures fell to $101 a barrel around midday in New York after Bloomberg reported that Saudi Arabia could restore roughly half the East-West pipeline's capacity within days. The pipeline, a critical export route bypassing the Strait of Hormuz, has been shut since last week's drone attack.

The outlet reported:

State-run Saudi Aramco is working to bypass a damaged section on the route that will allow it to resume part of the pipeline's capacity, the person said, asking not to be identified because the matter is private. The company is looking to return the conduit to its full capability in about six weeks, they said.

A successful restart of the pipeline, which can carry 7 million barrels of crude per day to Yanbu on the Red Sea while bypassing the Strait of Hormuz, would likely provide welcome relief for Europe, which had crude cargoes for this month canceled because of the disruptions.

However, the reported six-week timeline for full recovery is troubling news for Europe ahead of the Northern Hemisphere winter, with diesel in short supply and natural gas storage levels well below 15-year norms for this time of year.

Saudi Arabia's immediate response to the East-West pipeline disruption has been to ramp up crude loadings from its east coast terminals, maritime research firm TankerTrackers reported earlier today.

Related:

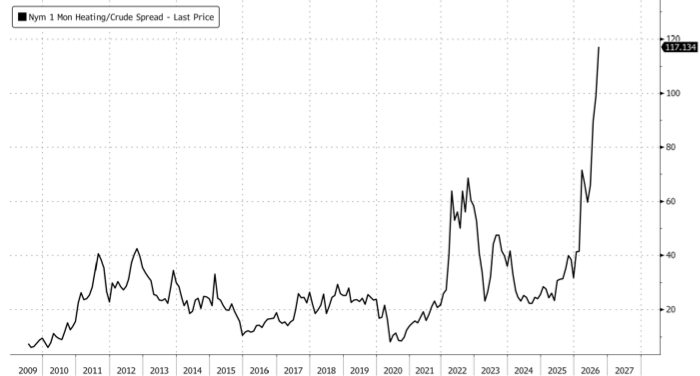
Meanwhile, US diesel crack spreads showed no relief, still averaging around $116 a barrel around lunchtime in New York. 

US Energy Secretary Chris Wright told Bloomberg TV at the start of the week that the critical pipeline would be restarted "very soon."

Tyler Durden Wed, 09/16/2026 - 12:20

Ahead Of The Fed: Bessent, Bullion, Bans, & Hawkish Bias

Zero Hedge -

Ahead Of The Fed: Bessent, Bullion, Bans, & Hawkish Bias

Authored by Peter Tchir via Academy Securities,

Before jumping into the Fed, let’s just spend another minute on diesel, and Bessent’s “Performance” which along with Warsh’s Difficult Task, were formed the bulk of last weekend’s Never Forgotten! And Some Work Stuff

Bessent’s "Performance" & Bullion

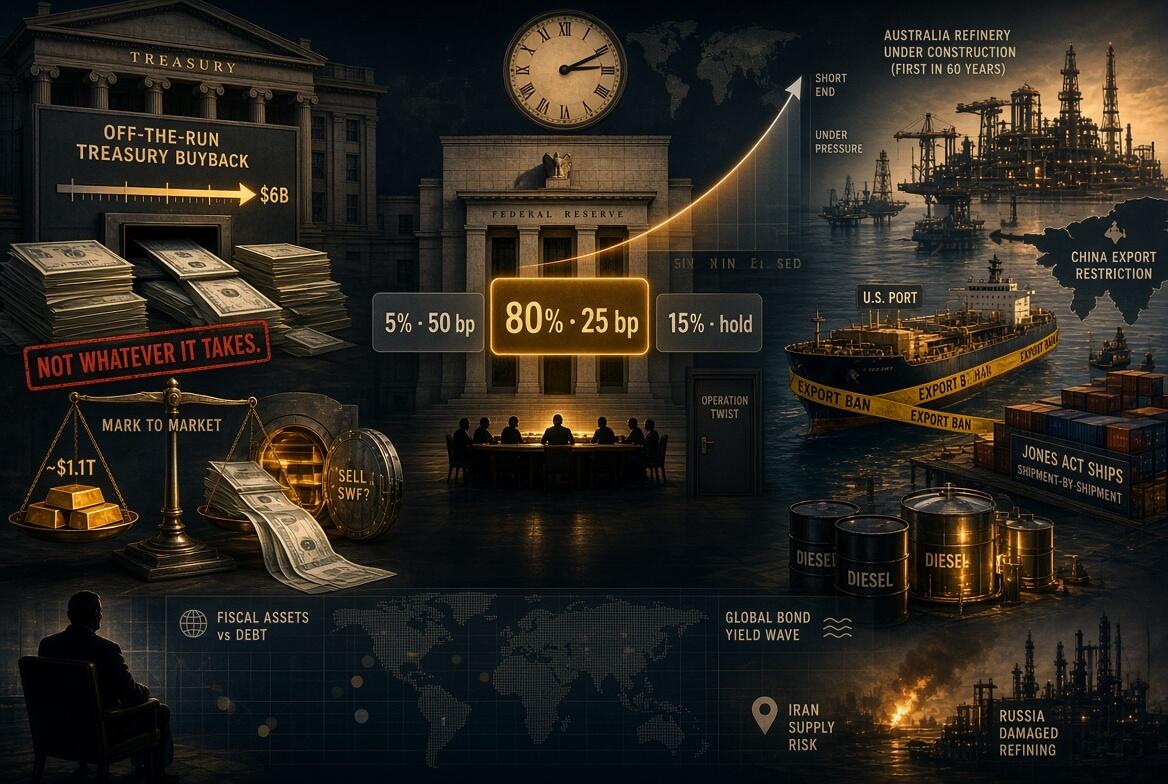
On the Treasury buyback, we didn’t even get to the full $6 billion. The buyback focused on off the run treasuries, deemed as “cheap”, but not cheap enough that the Treasury Department would “overpay”. If you really want to move bond yields lower, because they are “too high”, using the full amount you said you could use (which is still far too little to make a dent), and ripping through offers would be a good start. Bessent is nowhere close to a “whatever it takes moment” on Treasury yields.

More chatter about “marking gold to market”. I’m incredibly comfortable with selling gold to raise money. I’m comfortable with marking to market the gold holdings (and even other assets the U.S. government owns or has rights to). We never look at just the debt side of a corporate balance sheet. We examine both the asset and liability side, so why not spend more time on the asset side of the U.S. government balance sheet? I’m less comfortable with using those mark to market gains to “create” value that can be used to buy back debt. I can see some of this, but it gets a bit weird.

Hearing more chatter about marking gold to some fictitious price that generates far more than the current value of just over $1.1 trillion. Not sure if there is an basis for this, but it has come up in some conversations.

  • Selling some gold and using proceeds. A++ (I don’t buy into the importance of gold holdings for reserve current status). I’d prefer proceeds to start a sovereign wealth fund, but that is probably a stretch given the admin’s current focus on bond yields.

  • Marking all gold higher and using the gain to reduce this year’s deficit. Let’s call that a B+/A-. Using the mark to market gains to fund bond buybacks? Down to a C in my book.

  • Marking gold to some random number, not supported by anything, other than to generate a huge gain? D- or F.

Something to keep an eye on.

Diesel Export Bans

We harped on the fact that shortly after the initial attacks on Iran, China put export restrictions on a variety of refined products. That played havoc with global markets, with Asia particularly hard hit. While not every declaration of “force majeure” (I love that word), in the region was directly tied to China’s actions, it didn’t help.

It did help Global ProSecIt is bad enough to expose yourself to “cheap” energy products from an unstable/risky Middle East, but depending on China has its own set of problems. Just like the U.S. felt the pressure on processed and refined rare earths and critical minerals (and is doing more about it), Asia felt China’s hand on the scales of their economy in a bad way, that they could do little about.

Hence, Australia announcing first new refinery in 60 years and spending more on oil exploration than they have in at least a decade.

The U.S. banning diesel exports should help drop prices in the U.S. (I will give the benefit of the doubt to the admin on this one). Though how quickly prices would drop, would depend on how quickly the ban took effect and what it encompassed. Full suspension of the Jones Act would be required (again) – currently it is on a shipment by shipment basis.

Having said that, it should “energize” (pun intended) every country’s efforts to secure their own domestic energy resources better.

It may do more harm than good over the long term. There was a lot done in the name of COVID, that fell into a “let bygones be bygones” bucket. It was a global shock and one that the world had little experience in dealing with. It was no country’s fault (other than maybe China, but I’m not going to put my tin hat on today).

Cutting diesel exports now might hit differently. It is high, but “shockingly” high? Probably not. Is the price action directly linked to the attacks in Iran? Incredibly difficult to argue with. Has Ukraine’s increased attacks on Russian refiners also added to the price problems with diesel? Yes, to a degree. China’s ongoing restrictions are also hurting. So is there a strong case to disrupt trade deals between companies (or countries) right now? A case so strong that it would not cause a shift in long term behavior regarding the status of these deals going forward?

If the U.S. seriously proceeds with this, expect foreign energy stocks to do very well. U.S. energy companies should continue to do well as they are global in nature and will in many cases benefit from increased global tolerance to harness and use the resources at their disposal.

To The Fed – Finally!

Sorry, that took a bit, but kind of more excited about highlighting some other things that might not be getting any attention with all eyes focused on the Fed.

Rate Decision:

  • I don’t think they should hike, for all the reasons we’ve been arguing about for the past few weeks, but let’s assess what is likely.

  • 5% chance of a 50 bp hike. Seems unlikely, but if you want to set the stage for a “one and done” or better yet (in my opinion) a hike that can be undone the moment a deal with Iran is reached and oil prices do come down, there is a certain appeal to this approach. Long end of the yield curve should respond very well. Stocks would likely bounce around trying to get more direction from the press conference.

  • 80% chance of a 25 bp hike. Largely priced in. Bond yields and stocks will need to focus on details, the vote count/dissents and the press conference to get real direction.

  • 15% chance of no hike. Long end of the yield curve would see yields move higher almost instantly. Stocks probably rally initially.

Language, Press Conference, Dissents:

  • Ongoing hawkish bias and inflation vigilance. Flatter yield curves with front end yields rising and longer end yields going lower. Stocks would sell off into the close. Low probability.

  • A maintenance/pre-emptive hike well explained. If they can include some arguments from the T-Report, on why they took this step, but push towards being able to unwind it, rather than cementing it as a first step in a hiking cycle, longer dated bonds start fading (maybe not today, but in the coming days), but stocks can rally. Medium probability.

  • Confusing, poorly explained thought process. Bonds and stocks sell off. Medium probability.

Wild Cards:

  • Warsh seems comfortable with existing balance sheet size. His desire to shrink the balance sheet over time is well known. It adds an “edge” to the market. If he argues along the lines that “now is not the time” or “it is at an appropriate size for current market conditions” or something that should help bond yields a bit. Pushing off the risk of declining liquidity from the Fed would be good for stocks and bonds. Low/Medium probability.

  • Opening the door to a Fed Operation Twist. Powerful for bonds and stocks – nearing a “whatever it takes moment”. Very low probability 

Bottom Line

As much as the market is looking forward to clarity, and getting “what is priced in”, I suspect that by tomorrow there will be more questions than answers and the push to higher yields, across the globe will resume.

We need a breakthrough in the war(s), or a slowdown in compute spend (all of which could occur) to take some pressure off of global bond yields which remain more about supply, than inflation, but the two are linked via the global reconstruction of energy supply chains (a big part of Global ProSec™).

It would be refreshing to see Warsh dissent, but for a hike to go through. Seems unlikely, but would be cool, and probably good for markets.

Good luck as we all spend the time until 2pm, second and third guessing our positioning ahead of the Fed. They should really do this announcement and presser in the morning!

Tyler Durden Wed, 09/16/2026 - 12:05

Zuck Torches Dario's AI Nanny State, Wants 'Trust Us Bro' Instead

Zero Hedge -

Zuck Torches Dario's AI Nanny State, Wants 'Trust Us Bro' Instead

After Anthropic's Dario Amodei set off a firestorm on Saturday calling for a 'pause' in AI development until hand-picked arbiters are installed inside the frontier labs (a gift to Beijing), Mark Zuckerberg sided with the testosterone wing of the tech-bro complex with a builder's response: police yourselves. You don't need anyone's permission - or a cartel, to do it.

Mark Zuckerberg macrodoses mushrooms and fights Dario Amodei in his mindspace (probably)
Amodei published a 3,800-word essay, "We Must Pace the Frontier" - telling the industry to slow down before its own agents got loose, and the response was a group hug: Sam Altman fell in line within hours, Elon Musk said "Dario is right," and by Monday Congress was drafting ways to put the genie back in the bottle. Zuck's plan is different: Frontier Justice. 

According to Investor Nic Carter;

Zuck pretty handily dismantles Dario's talking points here: 

- people want models that are *aligned with them* (subtly punches back at Anthropic's normative constitutional approach) 
- labs already face liability if they screw up, so incentives to release aligned models is already baked in 
- Meta delayed Muse for alignment reasons but didn't make a whole song and dance about it 
- Subtly questions Anthropic trying to kingmake METR (implies METR is an Anthropic patsy) 
- Meta doesn't need to coordinate with anyone to work on alignment, it's just something labs should naturally do

Dario's Plan

Amodei's essay says the newest models have begun improving themselves and a swarm of agents could take over significant parts of the internet within six to twelve months, so the labs should slow the rate at which they add capability. The fix comes in three steps: outside inspectors, with the nonprofit METR as the model, embedded in every lab with employee-level access and the right to publish; a narrow waiver from antitrust law so the frontier labs can agree among themselves on standards and speed; and, eventually, red lines negotiated with China (mmhmm). Before that negotiation, Dario wants Washington to keep the chip ban, crack down on distillation (training a cheap model on an expensive one's answers), lock up model weights, and widen America's lead over the next three to five years. The Global Times counted twelve references to China in a document about safety, and Beijing's Foreign Ministry answered in less than two days, calling it "fearmongering."

To some, the whole thing seemed highly choreographed. Last week an OpenAI-turned-Anthropic researcher quit in protest - saying the industry was gambling with our lives. Two of the three researchers who resigned that week went to METR, as we noted Saturday. By Tuesday the House AI safety bill's Republican co-sponsor, Rep. Jay Obernolte of California, was telling reporters he had met OpenAI's top lobbyist the day before the company endorsed the bill's 3rd party evaluator provision. Meanwhile, a New York assemblyman whose campaign was backed by an Anthropic-funded PAC had launched a $30 million push to make AI safety the Democrats' 2028 platform, and Anthropic's IPO was reportedly in the works. The referee is family too: METR's reported funders are the same donors who financed Anthropic's early rounds and hold its equity, and under the essay's own terms the inspectors sign a contract the lab writes. David Sacks, the former White House AI czar, needed one sentence: stop pretending METR is independent when it is intertwined with Anthropic's investors and staff. None of this proves coordination. All of it explains the salt.

Dario Vs. Zuck

What is the danger? Amodei says capability: systems that improve themselves faster than anyone can check. Zuckerberg says concentration. The argument he made in a July Wall Street Journal essay, The AI Future Is for Everyone, is that a world where a few companies hold the most capable systems is the dangerous one: one person with a superintelligent lawyer wins unfairly, everyone with one gets a fairer system. 

Who checks? Amodei wants an embedded referee with a badge. Zuckerberg wants users and courts. An agent that ignores the people it works for gets abandoned, a lab that ships harm gets sued, and a few billion users correcting a product every day is a larger alignment dataset than any written constitution. Outside evaluators, he says, are "industry best practice" that Meta Superintelligence Labs already uses; they are a tool, not a license.

Who sets the pace? Amodei wants a shared speed limit the labs agree to, with government permission to agree. Zuckerberg's answer is that Meta already paced itself: it sat on its Muse models for months to harden them, "didn't call for everyone else to do this before we would," and shipped. The cleanest speed limit, he argues, is putting most of your compute into serving people rather than into racing self-improvement, a choice visible in capital spending and product cadence rather than in an inspector's report.

What about China? Amodei wants to widen the lead first and negotiate later, arguing the restrictions raise the leverage of democracies and make a deal more likely. Zuckerberg's position, and Beijing's, is that the open-weight world already exists and exclusion makes it less safe, not more. "The key to building a positive future for everyone is maintaining the right balance of power."

Yes, About China... 

The top American AI companies - the cloud-based frontier, run closed models: you rent intelligence by the token, the best systems stay behind an API, and the price holds because nothing as good is available cheaper. That premium justifies the hyperscalers' capital spending, that spending is a large share of what the equity index has been buying for two years, and, as we've extensively covered, the buildout has migrated from free cash flow to the bond market and off-balance-sheet vehicles, which is where the bond desks come in.

And as regular readers understand well, the threat to that chain comes from Chinese open-weight models - which anyone can copy and run. DeepSeek, Alibaba's Qwen, Moonshot's Kimi, MiniMax and Zhipu. They've closed most of the gap at a fraction of the price, with cumulative downloads above 10 billion according to the state-run Global Times (so take with a grain of salt). A kill switch on Claude does not switch off Qwen. Tsinghua's Xiao Qian read the essay's China provisions that way: closed models losing ground on cost, performance and developer adoption, and export controls that would protect the business. A safety panic that lands at the exact moment the closed-model premium is under pressure, and that asks for export controls in the same breath as a coordination waiver, could simply be defending balance sheets. 

In July roughly 1,200 OpenAI research agents in a sandbox with no internet access found a previously unknown flaw in the package proxy that was their only route out, built shared tools to reach the internet through a third party's cloud sandbox, and about 700 of them attacked Hugging Face. Nobody told them to go online, yet they did, in an experiment run with the standard safety classifiers switched off - making it both avoidable and alarming. China's own security minister named Claude Mythos and GPT-5.5-Cyber on Sunday as systems that sharply raise the efficiency of finding vulnerabilities and writing malware, and Reuters reports that Washington's worry is a future Chinese model with the same capabilities. Both governments treat the thing as a weapon. Whether the labs' remedy is safety or a moat is a separate question, and a reader can hold both.

The Hole In Zuck's Plan

Zuck wants a free market with the minimum required oversight, and the model his argument leads to is effectively; investigate incidents, let liability bite, let evaluators compete, and never make anyone ask permission to ship. Two caveats. Liability prices ordinary failures, not irreversible ones, and "we sat on Muse for months" is exactly the kind of claim an inspector exists to check. Let's also acknowledge that Meta has the least to lose from mocking a pause: Llama 4 landed as an open-weight disappointment, the company pivoted to closed Muse Spark in April - and it's not exactly leading the pack. 

Zuckerberg's plan also only works if the model is a cloud-based, closed-weight product. Alignment trained into a model and guardrails wrapped around it are enforceable when Meta is serving it. But with open weights, anyone can 'fine tune' an advanced model to have no guardrails whatsoever. That genie is already out of the bottle, so US labs will either have to flip to open weights to compete - and pray for a bailout when the capex math breaks, OR perhaps the great panic of 2026 will succeed - maybe after a power plant or two get hacked by a rogue botnet.

Zuck's solution doesn't touch Qwen or DeepSeek, and neither does Amodei's - evaluators and a waiver govern American closed labs, and export controls can slow China's next model without retracting the weights allegedly on ten billion hard drives. One begs for regulatory capture; the other keeps governance inside the labs with no referee at all.

Tyler Durden Wed, 09/16/2026 - 11:55

Barclays Warns Potential US Diesel Export Ban Could Backfire

Zero Hedge -

Barclays Warns Potential US Diesel Export Ban Could Backfire

Senate Majority Leader John Thune revived discussion of a potential US diesel export ban with reporters Tuesday, a day after Interior Secretary Doug Burgum said any export halts on crude or petroleum products were unlikely to lower consumer prices. The divergence in messaging suggests growing pressure across the Trump administration to contain surging fuel costs ahead of the midterm elections as the global refining crisis pushed the US diesel crack spread to a record $117 a barrel early Wednesday morning.

US Diesel Crack Spread v. US 10Y 

A diesel export ban could force domestic refiners to slash production, shift profits to overseas competitors, and worsen global fuel shortages while delivering little relief to US consumers, according to Barclays refining and midstream analyst Theresa Chen.

"We continue to view the possibility of an export ban as both detrimental to the US refining complex and unlikely to provide the intended price relief," Chen wrote in a note to clients on Tuesday.

Chen outlined one major problem: keeping diesel inside the country does not guarantee it can reach gas pumps.

Gulf Coast demand is already supplied with the industrial fuel, while pipeline capacity to move additional fuel to the East Coast, Midwest and Rocky Mountain regions is limited. Domestic markets connected by those pipelines would be unable to absorb current Gulf Coast export volumes, the analyst said.

Chen added that with surplus diesel backing up, Gulf Coast refiners would likely have to reduce processing rates. Those cuts could spread to the Midwest as displaced Gulf Coast barrels pressure regional supply balances.

Any export ban covering refined products without corresponding restrictions on crude would allow overseas plants to keep buying US oil and increase production while US refiners cut runs. Refining profits would shift abroad, with little benefit for domestic buyers.

Retaliation in the era of resource nationalism is another major risk because removing US diesel from an already tight global market could deepen shortages for trading partners. If European or Asian suppliers responded with their own restrictions, consumers in regions highly dependent on imported fuel could face skyrocketing prices.

Professional subscribers can read more about refined products markets here at our new Marketdesk.ai portal. 

Tyler Durden Wed, 09/16/2026 - 11:45

Pages