Individual Economists

Jefferies Beats On Record Stock Trading, But Asset Management Revenue Plunges 50% On First Brands, Radiant "Cockroaches"

Zero Hedge -

Jefferies Beats On Record Stock Trading, But Asset Management Revenue Plunges 50% On First Brands, Radiant "Cockroaches"

Jefferies is once again the first major Wall Street firm to report its quarter, and once again the story is of two very different banks under one roof: a trading and banking franchise running near record highs, and an asset-management arm that keeps finding new ways to lose money on receivables that may or may not exist.

The good news first. In the fiscal third quarter ended August 31, Jefferies reported EPS of $1.08, beating the $1.00 consensus (core EPS of $1.08 also beat Goldman's $1.03 and the Street's $1.01). Core pre-tax income came in 9% ahead of the Street, driven by:

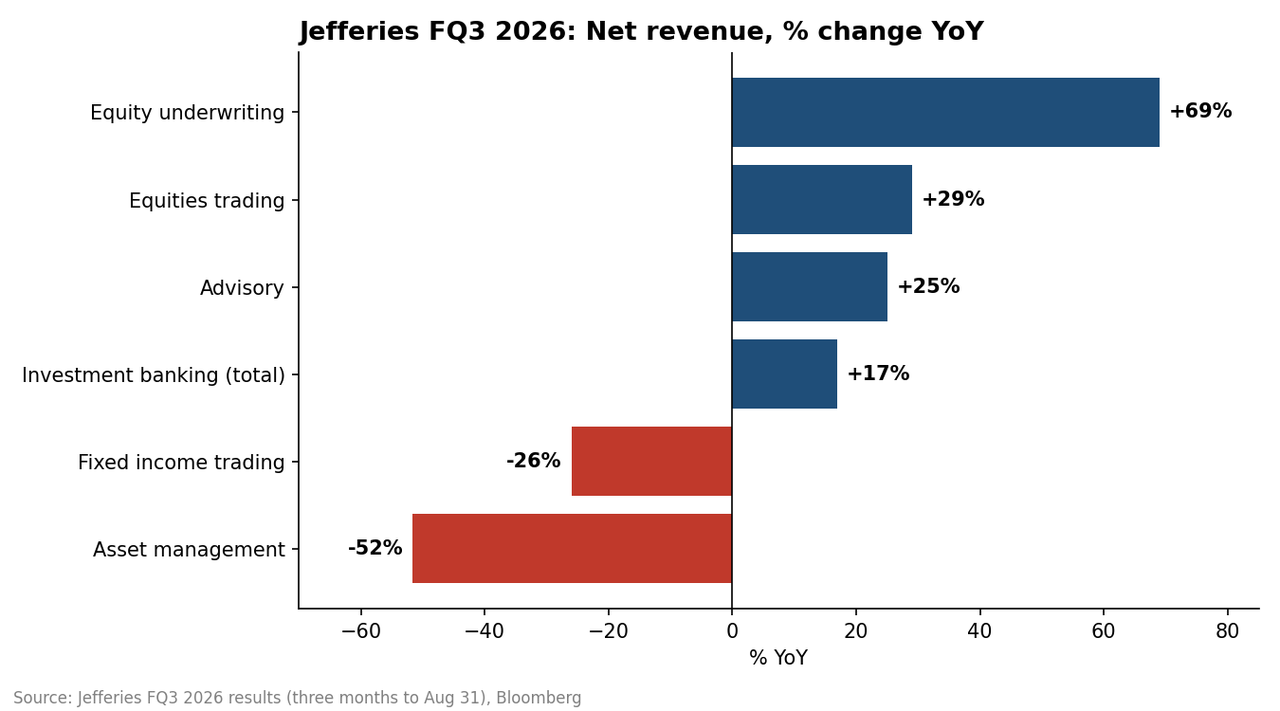
  • Equities trading: $626 million, up 29% YoY and a record, helped by cash, electronic trading and prime services (i.e., hedge funds levering up into the AI melt-up).
  • Investment banking: $1.3 billion, up 17%, with advisory up 25% (also a record) and equity underwriting up 69%.
  • Fixed income trading: the laggard, with net revenue down 26% in what the bank called a sluggish market.

And then there's the asset-management unit, where net revenue fell to $85.6 million from almost $177 million a year earlier. That's a 52% drop, and it comes from the same two names that have been following Jefferies around for a year: First Brands and Radiant World, both held through Leucadia Asset Management's Point Bonita trade-finance fund.

The stock fell 1.1% in early trading, taking the YTD decline past 25%. That is a strange reaction to a record quarter, unless you remember how the last twelve months have gone.

Goldman: Buy... with a 15% lower price target

Goldman's James Yaro headlined his overnight note "Equities trading and expense beat, outlook and momentum remain largely the same." That is sell-side for "fine, nothing to see here," and Goldman does expect "a slightly constructive response to results." Look closer, though, and the note is a good deal less relaxed than the title.

First, the good parts, per Goldman:

  • Equities: A second consecutive record at $626MM, 10%/14% ahead of GSe/Street, "with strength across all products, especially in prime."
  • Advisory: Record quarterly revenue, "in part driven by a sponsor recovery, as well as broad-based share gains across sectors."
  • Margins: A core pre-tax margin of 15.8%, about 150bps above consensus, thanks to a non-comp ratio about 145bps below the Street.
  • Buybacks: 1.3MM shares repurchased in the quarter.

Now the less good parts, starting with the quality of the beat:

  • The banking beat is the volatile kind. It "was primarily driven by other investment banking ($31mn vs. GSe/consensus at $5mn/11mn), the most volatile of JEF's IBanking business." Underwriting actually missed by 3%. ECM came in 4% short of the Street, even while growing 69% YoY, so expectations were running even hotter than the deal flow.
  • Some of the expense discipline is really just shrinkage. A portion "likely relates to merchant banking wind-downs, which appear to have been larger than anticipated in terms of both revenue and expenses." Jefferies is spending less partly because there is less business left to spend on.
  • FICC missed badly: 18% below the Street and 15% below Goldman.

And then there is asset management, where the headline number actually understates the damage. Strip out merchant banking and Jefferies' core asset-management revenue was just $13 million, against Goldman's $38MM estimate and the Street's $36MM. That's a 66%/64% miss, "primarily driven by lower investment returns." In response, Goldman cut its 2026E/27E/28E asset management revenue by 22%/11%/6%.

Goldman's rating is still Buy, but look at what it did to valuation. The bank (full report here) cut its target multiple by 2.5x to 11.0x and its 12-month price target by ~15%, from $67 to $57, even as its 2026 EPS estimate rose 2%. It also offered a telling explanation for the stock's persistent discount: "we believe that the market discounts the multiples assigned to these businesses, given their volatility." Put simply, even when Jefferies beats, investors won't pay up for the kinds of earnings it produces.

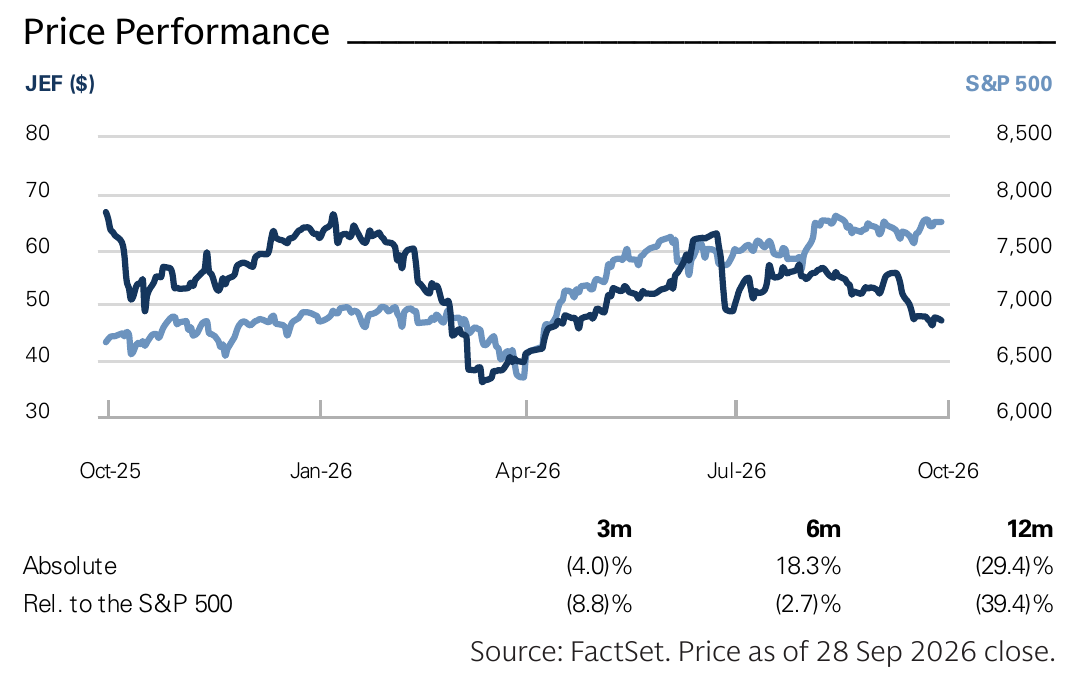
The chart in the Goldman note shows the result: JEF is down 29.4% over twelve months, and 39.4% behind the S&P 500. The stock peaked just as First Brands was about to blow up and has spent the year since trailing the market.

Vital Knowledge's Adam Crisafulli gave the quarter a fitting grade: "Not amazing, not horrible." He also questioned how long the equities boom can last, which is a reasonable question when the entire Street is printing record equities revenue on the same trade.

The wider read-across is positive for the rest of the Street's equity desks. BofA's Brian Moynihan said earlier this month that equity trading was up in the quarter through mid-September, and Goldman's David Solomon said equities remained "very strong." In FICC, BofA warned that revenue was down and "bouncing around," and Jefferies' -26% suggests that was an understatement.

The cockroach problem

Management kept the upbeat tone. CEO Rich Handler and President Brian Friedman said they "remain confident in the long-term outlook" for asset management as they "reposition the platform by reducing capital allocated to certain existing funds." In other words, Point Bonita is being wound down. The plan is to put the capital into Hildene, the credit manager Jefferies agreed in December 2025 to buy 50% of, alongside Hildene's $550 million purchase of annuity writer SILAC. Replacing a trade-finance fund that blew up on receivables with a credit shop that owns an insurer is one way to diversify, at least.

As a reminder of how we got here:

  • First Brands. When the auto-parts roll-up collapsed into bankruptcy in the fall of 2025, it turned out that Point Bonita, which once managed roughly $3 billion, had about a quarter of its assets tied to First Brands receivables (around $715 million, per Jefferies' own October 2025 update). The DOJ then opened a probe into what we called First Brands' "shocking bankruptcy" (Oct 2025). A week later, Jamie Dimon's "when you see one cockroach, there are probably more" line became the market's official slogan, and JEF crashed more than 10% in a single session as regional banks crashed as more credit "cockroaches" emerged (Oct 16, 2025).
     
  • Market Financial Solutions. Then, in February, Jefferies was again scrambling to recover what it could (Feb 27, 2026) after the collapse of UK bridging lender MFS, where we noted that "Banco Santander and Jefferies – both of which sank in the First Brands swamp" were once more in the line of fire.
  • Radiant World. This is the latest one, and it is the ugliest. Radiant is a Singapore iron-ore trader that bought receivables from counterparties like Glencore and Vitol and financed them through banks and funds, including - drumroll - Point Bonita. In August, Hedgeweek reported that payments to the fund had "slowed," and several commodity houses stopped trading with Radiant over questions about its invoices. Jefferies was said to believe the underlying trades "remain legitimate."

That view lasted about a month. Since then:

  • Sep 5: Jefferies' LAM Trade Finance fund won a UK freezing order against Radiant, founder Pinkesh Nahar, and affiliate Sapphire Minmetals. Parallel orders followed in Hong Kong and Singapore.
  • Sep 8-9: The fund formally accused Radiant of fraud in a $500 million claim, alleging the iron-ore receivables "either did not exist or were not validly assigned."
  • Sep 17: Radiant disclosed that it had about $10,000 in cash, compared with audited financials showing more than $200 million. Somewhere, an auditor is updating their LinkedIn.
  • Sep 19: Radiant sued Glencore for $2 billion in Singapore, which is an interesting move for a company with $10K in the bank. Glencore has reportedly already taken a $480 million provision and told Mizuho that Radiant sent it a fake Glencore email about repaying a $95.5 million loan.
  • Sep 24-25: KPMG was appointed interim judicial manager, a Singapore judge questioned Radiant's claimed $1 billion of receivables, and Bloomberg reported that Singapore police had received a fraud report months before the crisis, with Intesa Sanpaolo apparently suspicious of the invoices before anyone else.

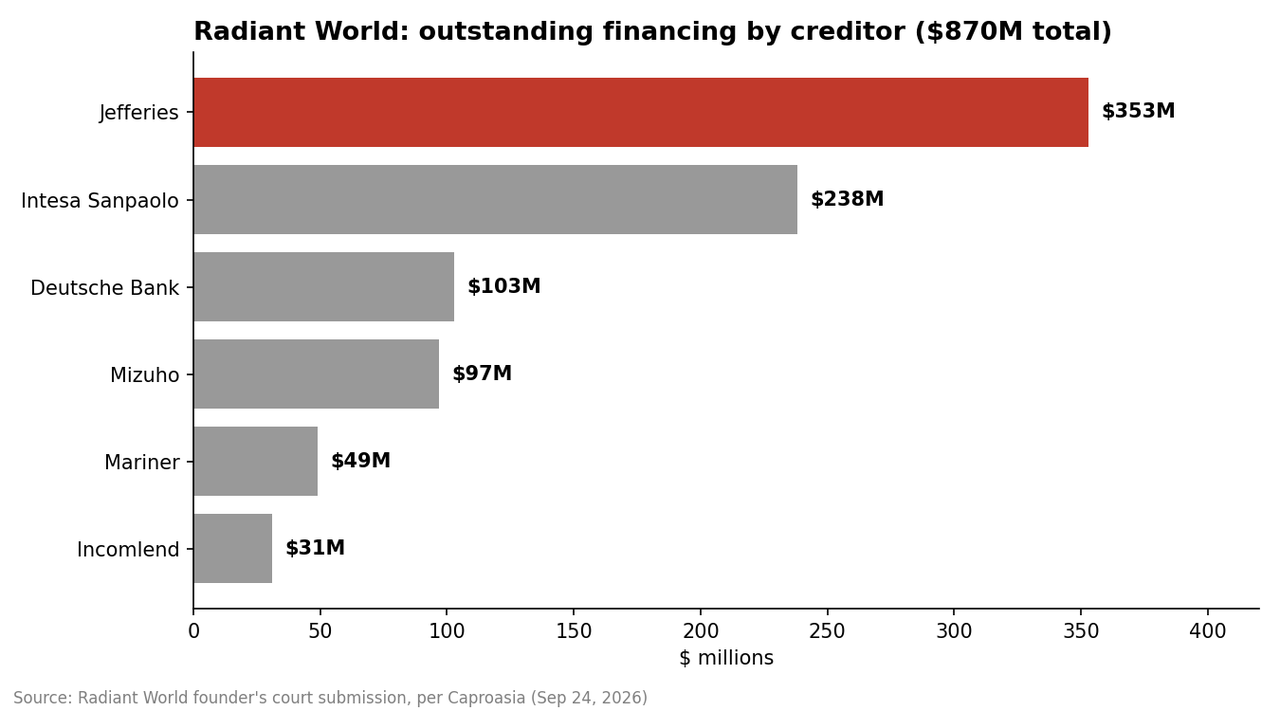
Then there is the question of how much Jefferies actually has at risk. Bloomberg has put Jefferies' exposure at "less than $300 million." But according to a creditor schedule the founder submitted to the court, Jefferies is Radiant's largest creditor at $353 million, well ahead of Intesa ($238MM), Deutsche Bank ($103MM) and Mizuho ($97MM), out of $870 million total. The fraud claim filed by the fund is for $500 million. Pick a number.

Bottom line

For the rest of the Street, the Jefferies print is good news: equities are booming, the ECM window is wide open, advisory is at records, and backlogs are "broad and strong" ("very optimistic about the balance of 2026 and our momentum heading into 2027," per Handler and Friedman). JPM's Market Intel desk, which this morning went back to "Tactically Bullish," said that outside of AI plays it favors banks, given "the growth reboot, potentially steeper yield curve, and favorable capital markets outlook."

For Jefferies itself, the market is saying something different. The stock is down more than 25% YTD and nearly 30% over twelve months despite record trading and advisory. Goldman's Buy rating now sits on a price target 15% lower and on a multiple that assumes investors will keep charging a volatility discount. Goldman even lists "a much longer timeframe to wind down the merchant bank" among its downside risks.

After First Brands, MFS, and now an iron-ore trader with $10,000 in its account and a fake Glencore email, the market isn't asking whether there are more cockroaches. It's asking where the next one is.

Tyler Durden Tue, 09/29/2026 - 12:30

Democrats Split On Whether To Impeach Trump Again If They Win The House

Zero Hedge -

Democrats Split On Whether To Impeach Trump Again If They Win The House

Authored by Chase Smith via The Epoch Times,

House Minority Leader Hakeem Jeffries (D-N.Y.) said on Sept. 28 that Democrats would put lowering costs first if they win the House in November.

But he did not rule out impeaching President Donald Trump, as members of his party are split publicly on whether to try for that a third time.

Asked on CNBC's "Squawk Box" how much of a Democratic majority's next two years would be spent on hearings about Trump, his family, and his administration, Jeffries said the party is focused on affordability but also has an oversight role.

"We're committed to an affordability agenda," he said.

"As I travel the country, speak to people, whether that's in urban America, rural parts of America, the heartland of America, small-town America, or black and brown communities throughout America. The one thing that is clear is that people are struggling.

"They are drowning in this failed Republican economy. They're working hard, they're playing by the rules, but they cannot thrive and can barely survive. It's an unacceptable situation. And so, when we say we're focused on affordability, we mean it."

Jeffries said he believed that there has been "unprecedented corruption unleashed on the American people" and that if Democrats win the House, they would "have a responsibility to visit the type of accountability that is consistent with the House as a separate and co-equal branch of government."

Pressed on the balance between accountability and affordability, he said the next Democratic caucus would include progressives, moderates, and more socially conservative members united around the cost of living.

Jeffries said when it came to cleaning up what he called the "rampant corruption" that exists in Washington, Democrats would "follow the facts, apply the law, be guided by the Constitution, and then let the chips fall where they may on behalf of the American people."

"We have a responsibility, of course, as a Congress, to serve as a check and balance on an out-of-control executive branch. That's not partisan, that's patriotic," he said.

Jeffries's comments came a day after Rep. Ro Khanna (D-Calif.) said on NBC's "Meet the Press" that impeaching Trump a third time would not be a mistake for Democrats.

"No, it's not. Because it's not about Donald Trump," Khanna said.

"He's going to be a lame duck, and in my view, increasingly irrelevant.

"The point is to stand up for the Constitution.

"Impeachment says that you can't get into an illegal war in Iran without constitutional approval. Impeachment says that you can't just start firing federal employees in defiance of what Congress says. Impeachment says you can't do deals with foreign governments to allegedly enrich your own family.

"It's about setting a standard."

He said Democrats could pursue impeachment while also moving on child care, the minimum wage, paid family leave, and taxes on billionaires in their first 100 days.

"We can do both," he said.

Khanna was responding to a clip of Sen. Tammy Duckworth (D-Ill.), who told an audience at the Center for American Progress on Sept. 22 that Democrats should not pursue impeachment if they win control of Congress.

"What I will encourage my colleagues to not do, especially those who have more fire in their belly in this area, is don't be impeaching anybody. Let's just get back to work," Duckworth said.

"I'm not interested in being in a confrontation with Donald Trump. I can be. I have been. It's not going to stop me. But I would rather move the ball forward through the benefit of the American people.

"And if we can do it in a way that allows him to save face and he doesn't stop us, then that's better for everybody all around."

Duckworth, speaking at an event on U.S. - China relations ahead of Chinese leader Xi Jinping's White House visit, said her priority was resolving tariffs that she said threaten Illinois soybean, corn, and pork farmers.

Trump was impeached by the House in 2019 and 2021 and acquitted by the Senate both times.

House Judiciary Committee Chairman Jim Jordan (R-Ohio) said on John Catsimatidis's "Cats Roundtable" radio show on Sept. 27 that a Democratic majority would turn oversight into a campaign against Republicans.

"You will see the Democrats take that oversight function and turn it into a weaponization of government. They will go after everybody. They say they're not going to, but we know they will," Jordan said.

"They'll do a third impeachment of President Trump.

"But that's just part of it. They're going to investigate the first family. They're going to investigate Cabinet secretaries, anyone.

"Jamie Raskin is going to go after Todd Blanche and Kash Patel. They're going to have people in other committees go after Secretary Hegseth and on and on; it's going to be."

Jordan said potential targets he believed that Democrats would go after include businesses that helped fund Trump's inauguration and potential 2028 Republican presidential candidates, including Vice President JD Vance and Secretary of State Marco Rubio.

"It'll be nonstop weaponized investigations, not for legitimate oversight, but to just go after your political opponents," he said.

Rep. Jamie Raskin (D-Md.) is the top Democrat on the House Judiciary Committee and would be in line to lead it under a Democratic majority. The midterm elections are on Nov. 3.

The White House stated that the threats amount to "decades" of recycled "investigations against President Trump, his family, and his administration," in an emailed response to The Epoch Times.

Tyler Durden Tue, 09/29/2026 - 12:15

Oklo Loses PJM Queue Fight As FERC Points To Flawed Application

Zero Hedge -

Oklo Loses PJM Queue Fight As FERC Points To Flawed Application

Data centers have become the favorite explanation for the price-of-power squeeze. But, years of inadequate transmission planning and clogged interconnection queues have left the system struggling to accommodate new generation, too.

As we previously highlighted with Three Mile Island’s restart, even a load that used to be connected to the grid can be told to wait several years before seeing a reconnection become possible.

Now, advanced reactor developer Oklo has provided another reminder of how expensive a place in that queue can become. Although, in this case, Oklo dug its own hole.

On September 24th, FERC rejected Oklo’s bid to reverse its removal from PJM’s current interconnection study cycle. The proposed Virginia project combines 150 MW of nuclear generation, 300 MW of fuel cells and 300 MW of gas generation.

PJM booted Oklo from the study cycle back in August. Oklo warned that losing its place would push development back by more than a year and increase costs, neither of which reflects positively on a nuclear industry recovering from decades of delays and cost overruns.

The dispute began after Oklo submitted its application in April. PJM identified multiple deficiencies in the application the next month, all of which Oklo claimed were fixed in the days immediately after being notified.

Then came a communications breakdown. In its emergency complaint filed in August, Oklo accused PJM of posting additional objections in its application portal without emailing a formal deficiency notice or allowing another repair round.

According to FERC’s order, PJM needed a workable computer model of the entire 750 MW facility. Oklo’s submission demonstrated stability only for the 300 MW fuel-cell portion. PJM said the nuclear and gas units became unstable when included.

After all the back-and-forth, Oklo was unable to save the application, and FERC ruled in PJM's favor. 

The worst part about the deal is arguably how painfully similar the entire situation is to Oklo's first attempt at licensing their reactor. After almost two years of back-and-forth with the NRC, the regulator rejected Oklo's submission, citing missing information regarding potential accidents and safety systems and components.

While Oklo did score a win recently with obtaining initial criticality on their isotope production reactor in Texas, this is another painful loss which shows the company may not have learned its lesson yet.

Tyler Durden Tue, 09/29/2026 - 12:00

Russia's Drones Zero In On Ukraine's Data Centers, Mobile Providers

Zero Hedge -

Russia's Drones Zero In On Ukraine's Data Centers, Mobile Providers

The Russian defense ministry on Tuesday indicated that it attacked and struck two military cargo vessels in the Black Sea as well as two data centers in the Ukrainian capital overnight.

The vessels, which were sailing foreign flags, were struck off Odessa, President Zelensky also confirmed in a Tuesday statement.

DSNS Ukraine

The Kyiv region along with ten other areas came under attack overnight, Zelensky acknowledged. But it is the capital which has been getting pounded, also following many weeks and months of Ukraine's long-range drone strikes on Russian territory.

On Monday at least two people were killed when a drone hit National Academy of Sciences in the central part of the capital. The academy in a statement blasted the attack as "Russian terror" and "barbarity" aimed at "peaceful people who were simply at their workplaces."

A couple of new 'themes' have emerged in what have long been a nightly reality of devastating air raids. First, high flying jet-powered drones have been increasingly deployed by Russia.

The new Geran-5 is said to have anti-jamming capabilities and can travel up to an estimated 370mph, reports say. All of this makes them extremely hard to intercept.

Another theme is the war on data centers and mobile infrastructure. One regional source cited the Russian Defense Ministry as calling the campaign a 'mandatory digital detox' with grim sarcasm.

The same source documents the following recent attacks on data centers in Ukraine:

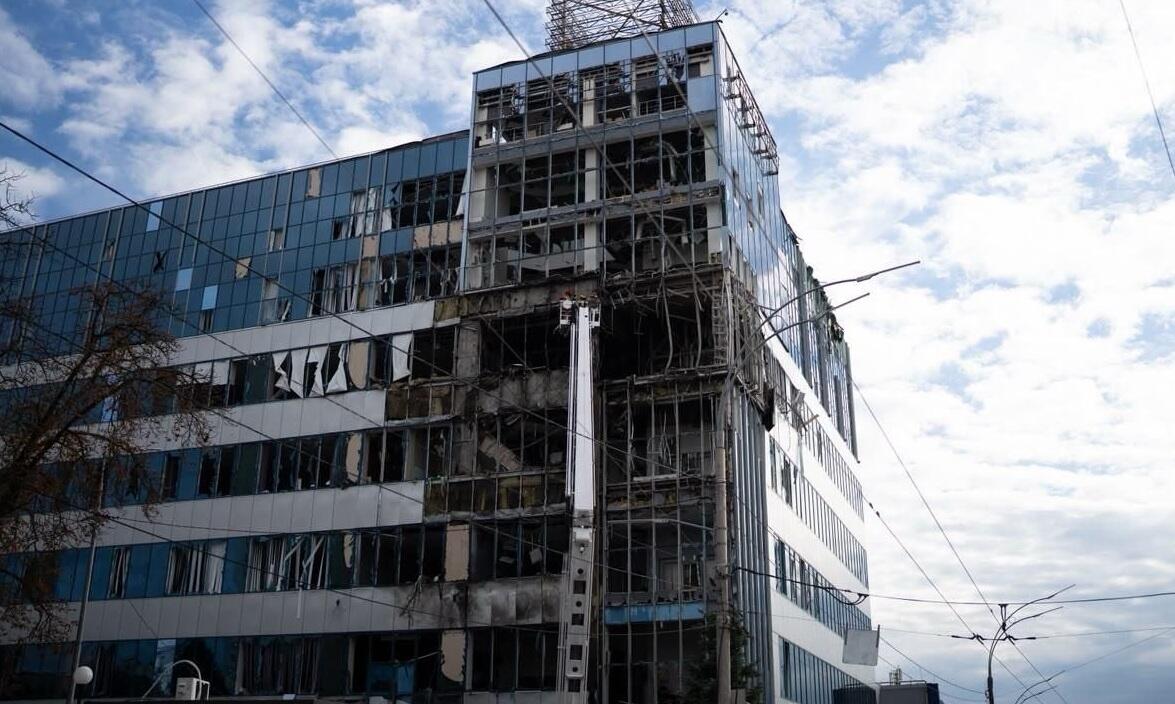
Russian forces continue to strike Ukrainian data centers. On September 25, they attacked an office building in Kyiv that houses a Datagroup data center. The center was damaged, but the company said all its services continued to run from backup sites.

On September 26, a Cosmonova data center in another Kyiv office building was hit. It had to shut down, interrupting broadcasts by several television channels. The strikes on data centers also left some Kyiv residents without internet access.

On September 28, a Russian drone struck an office building in Dnipro. The regional administration reported damage and casualties but did not say which companies occupied the building...

On September 26, Russia’s Defense Ministry said it was striking data centers because they “process and transmit intelligence data for the Ukrainian Armed Forces.” The next day, the ministry posted an image of a drone on social media with the caption “Digital detox” and the comment “Mandatory!”

At the start of this week Russia hit the headquarters of Kyivstar, Ukraine's largest mobile service provider, according to a statement by the company.

Reports of at least seven total killed and over 50 injured in the capital on Monday amid the major attack:

Additionally the Russian military had on Sunday announced hitting a data center belonging to Vodafone Ukraine, which is Ukraine's second-largest cell network provider - all of which strongly points to the campaign on comms infrastructure set to continue.

Tyler Durden Tue, 09/29/2026 - 11:30

Newly Released Fauci Files Reveal Dangerous NIAID-Funded Aerosolized Ebola Research

Zero Hedge -

Newly Released Fauci Files Reveal Dangerous NIAID-Funded Aerosolized Ebola Research

Authored by Debra Heine via American Greatness,

Senator Rand Paul (R-Ky.) released documents from Dr. Fauci's diary and emails Monday detailing his dangerous NIAID-funded research during the Obama Administration, including a 2015 experiment that exposed vaccinated monkeys to aerosolized Ebola.

The risky research was conducted at the United States Army Medical Research Institute of Infectious Diseases (USAMRIID) at Fort Detrick under a NIAID task order. The NIAID study compared four vaccines in groups of four monkeys exposed to aerosolized Ebola. The exposure was engineered to drive the virus deep into the lungs in a way natural infection would not, the records show.

The vaccinated primates reportedly developed necrosis, inflammation, and fibrin in the lungs, while the unvaccinated controls did not, indicating that the vaccine itself was making the disease worse. The experiments left 80 percent of vaccinated monkeys dead.

"What idiots those guys at USAMRIID are," Fauci wrote on March 7, 2016. The work "should have been a classified experiment that never should have been done in the first place," he added. Two days later, however, then-NIAID director wrote that the experiments were "important for bio defense."

Fauci was outraged that the failed vaccine research was shared with U.S. embassy officials in Guinea, Liberia, and Sierra Leone.

"This should have been a classified experiment," he wrote in his diary. "The foolish DOD people send the data to the FDA and then circulated as FYI to various embassies including those in West Africa where we are about to engage on a much larger DSD vaccine trial for Ebola."

According to Fauci, the embassy officials "went bonkers" because it looked like the U.S. wanted to vaccinate people with a dangerous vaccine.

He also said such experiments should have been classified because they "could indicate a vulnerability."

However, NIAID's own report states that at no time had clearances been requested, nor was classification ever mentioned. Moreover, the data had already gone to vaccine manufacturers, and some of it had already been published.

Nonetheless, Fauci was dismayed when a Department of Defense official mentioned the experiments were funded by NIAID during a White House briefing. "No one followed up on that, but I almost fell off my chair!!!!" he wrote in an email to his colleagues at NIAID.

Following this disclosure, NIAID officials discussed "damage control" in an email chain. "We may need to a bit of damage control here," NIAID's biodefense director wrote.

The problem for Fauci wasn't the dangerous experiments, but the possibility the public could find out about the dangerous experiments. So he took immediate steps to have the research classified.

"The DoD folks said that they wanted to publish the data. I said that I thought that it should be classified and the NSC people blew them out of the water and said that they agreed with me," he said.

Deputy Director Cliff Lane told two NIAID scientists not to move forward on Ebola experiments until the dust settled, warning that "one might consider this dual use research." He instructed his colleagues not to discuss the matter with anyone until he had a chance to talk to them.

Four days later, NIAID researcher Peter Jahrling warned that if aerosol challenge studies were treated as dual use research of concern, "the entire MCM development paradigm is gutted," and wrote "I will keep the rest off Email."

In the same message, Jahrling ominously noted that with the Ebola work paused, NIAID would "continue to make plans to initiate the CoV [COVID-19] study as soon as the lights turn green."

Tyler Durden Tue, 09/29/2026 - 11:10

FICO Crashes Most Since 2004 As Pulte's Mortgage Score Shakeup Threatens Its Moat

Zero Hedge -

FICO Crashes Most Since 2004 As Pulte's Mortgage Score Shakeup Threatens Its Moat

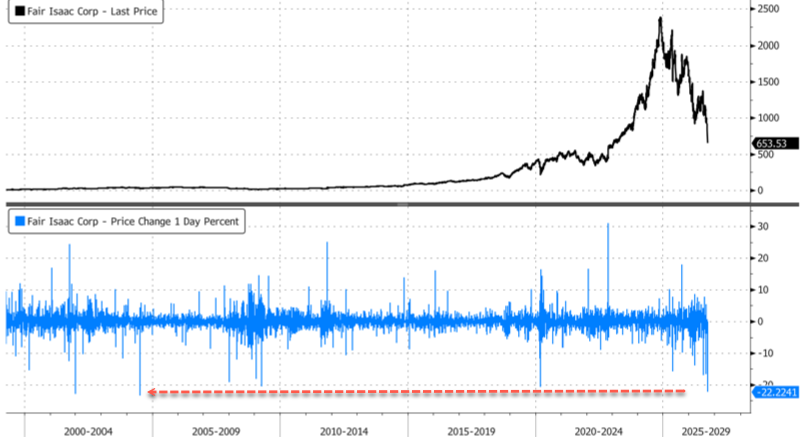
Fair Isaac, the company that produces FICO scores, saw its shares crash the most in 22 years early Tuesday in cash trading after Federal Housing Finance Agency Director Bill Pulte announced on X that a mortgage-pricing change that Wall Street analysts say could accelerate adoption of rival VantageScore and undermine FICO's moat. 

"We are Simplifying Mortgage Pricing following feedback from lenders and consumers. Instead of two separate pricing grids, which makes zero sense, Fannie and Freddie are hereby moving to ONE PRICING GRID with VantageScore joining the existing FICO Classic pricing grid," Pulte posted on X Monday. 

Pulte cited a press release from Rocket Mortgage that stated: "Rocket Mortgage did an extensive study that helped the company determine VantageScore 4.0 opens access to some clients who wouldn't be served otherwise, and many are able to secure a mortgage on better pricing terms. For those who saved money with VantageScore 4.0, the savings was an average of $1,600 at closing. FHFA and Director Pulte are encouraging competition and innovation in pilot programs."

The change gives lenders a stronger incentive to adopt VantageScore, potentially lowering costs for homebuyers while threatening FICO's market share and pricing power. Traders responded by sending FICO shares tumbling 22% earlier this morning - the largest intraday decline since July 13, 2004.

Here's what Wall Street analysts had to say (courtsey of Bloomberg): 

FT Partners

  • With pricing now in line, VantageScore could see increased adoption, with a lower hurdle for more favorable LLPA pricing, says analyst Craig Maurer
  • The move will allow more borrowers to qualify for lower rates, adding to VantageScore's existing cost advantage
  • Under a common LLPA grid, borrowers whose VantageScore 4.0 exceeds their classic FICO scores could qualify for a more favorable pricing bucket when selected

TD Cowen

  • The news presents a risk to FICO because it's not about which model is more predictive of defaults; it's about the regulators shifting LLPA pricing to get lenders to use VantageScore over FICO, says housing policy analyst Jaret Seiberg
  • One long-term worry is that it creates an incentive for FICO and VantageScore to compete on producing scores that result in lowest LLPAs rather than on the risk of default

RBC (rates FICO as outperform)

  • The news meaningfully raises the risk of score shopping, where lenders select whichever model produces the more favorable credit score and a lower mortgage interest rate, says analyst Ashish Sabadra
  • With unified pricing, VantageScore's market share gains could accelerate
  • Another risk is FICO may need to hasten its shift away from traditional per-pull origination fees toward other pricing structures to defend its economics

Deutsche Bank analyst Faiza Alwy asked clients, "Where is the moat?" 

Alwy provided clients with her first take on the developments:

Single pricing grid plus Rocket to use VS4 as preferred credit scoring model

There were two important and negative developments that happened post-close yesterday. The first one was FHFA Director Pulte indicating on X that based on lender feedback, the GSEs will operate on one LLPA grid and VantageScore 4.0 (VS4) will now join the existing FICO Classic grid. This means that the VS4 20 point discount to FICO has been removed by the FHFA and both scores will now be treated the same by the GSEs. This would likely in and of itself result in higher number of mortgages that will see favorable pricing with VS4 vs. FICO Classic. We would have expected continuing gaming and for lenders to optimize pricing with this change. However, the announcement from Rocket this evening following this change is meaningfully negative and consequential for FICO.

Rocket Mortgage announced that it will become the first mortgage lender to use VS4 as its preferred credit scoring model for all eligible loans. Specifically, during 4Q26, the company will default to VS4 for mortgages that will be delivered to GSEs, VA home loans and any other eligible mortgages. The company noted that after four months of testing, it found that VS4 helped more clients qualify and move forward in the mortgage process, while also reducing credit scoring costs. Rocket is a top mortgage originator with ~5-6% share (possibly higher following the acquisition of Mr Cooper in 4Q25).

We're not entirely sure what the words "preferred" and "default" exactly mean at the moment but the worst case interpretation for FICO would be that Rocket Mortgage will not be pulling FICO scores at all when eligible. Important to note that the above excludes mortgages for investment properties and second homes, HELOCs, FHA loans, jumbo loans and some other products. Rocket Pro, the division that provides home loans through mortgage broker partners, will continue to provide both VantageScore and FICO to mortgage brokers. Rocket Pro comprised about 30% of the company's origination volume in 2025. We estimate that in aggregate about both scores would be pulled 50% of the time (at origination). Encouragingly for FICO, Rocket did indicate that they will continue to evaluate new options as they become available (a likely reference to FICO 10T).

Could other lenders follow suit? It would make sense to assume that UWM would follow suit but we note that UWM operates exclusively as a wholesale lender and competes directly with RocketPro. Other lenders were not particularly active in the pilot program, so we expected limited movement near-term.

What does this mean for FICO's mortgage strategy? FICO's management continues to believe that notwithstanding significant price increases in the last few years, the score remains under-priced relative to the value it is providing. We expect FICO's 2027 approach to pricing to be variable by lender with the company offering and implementing the performance model for some lenders. Ultimately this makes us much less confident with respect to FICO's mortgage revenue algorithm at least in the near-term. That said, we believe the non-GSE securitization market will require FICO Classic for an extended period of time; recall that the FHFA has indicated it will provide both VS4 and FICO on all GSE loans that are securitized to investors. We suspect FICO will attempt to monetize the securitization channel or GSEs.

We will revisit our model as we gather additional information and the mechanics of these new late developments. In the interim, we expect FICO stock to understandably react negatively.

With FICO's competitive moat under pressure, this new development raises the risk of "score shopping," as lenders select the credit-scoring model that secures the most favorable mortgage pricing for prospective homebuyers.

Tyler Durden Tue, 09/29/2026 - 10:55

Record Plunge In Real-Estate Job Opening Sends JOLTS Sharply Lower, Hints At Ugly Jobs Report

Zero Hedge -

Record Plunge In Real-Estate Job Opening Sends JOLTS Sharply Lower, Hints At Ugly Jobs Report

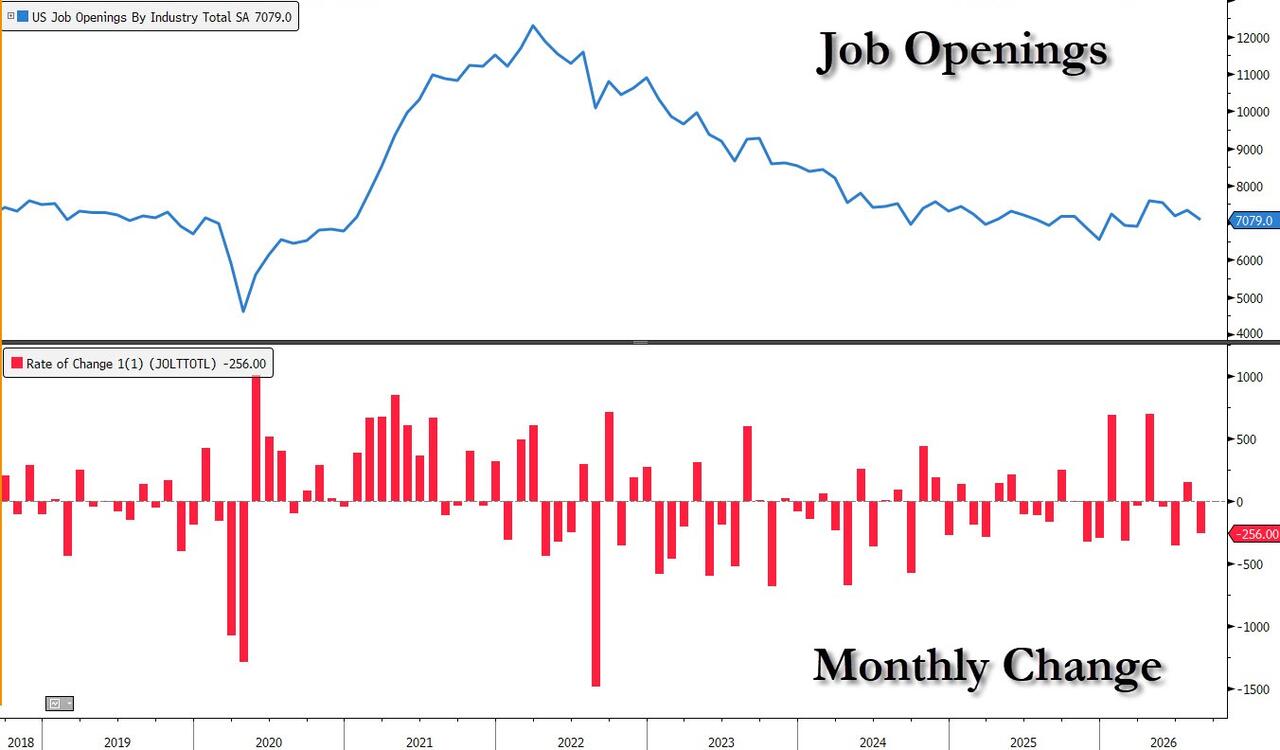
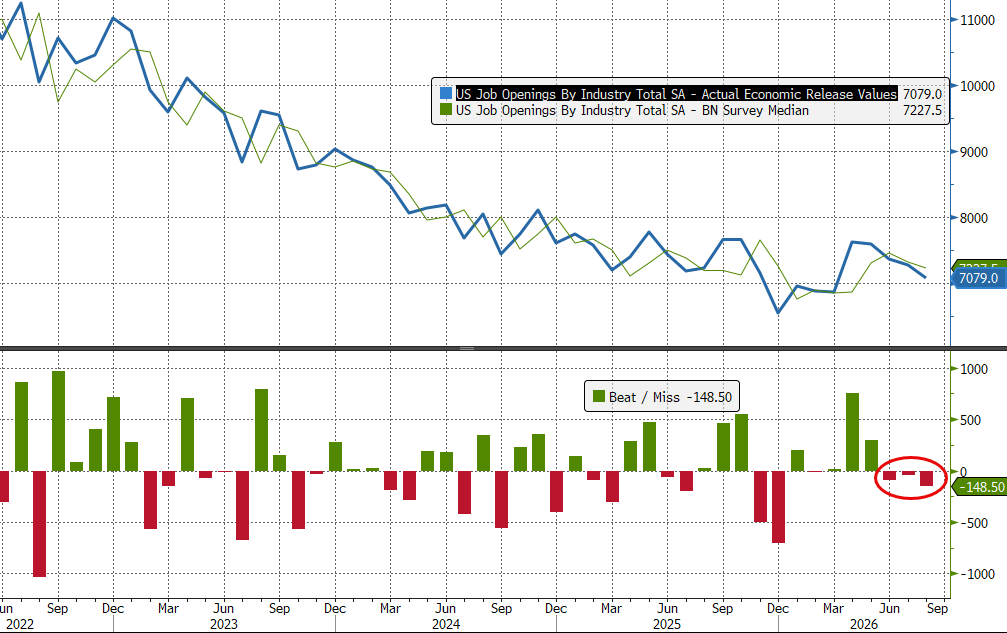
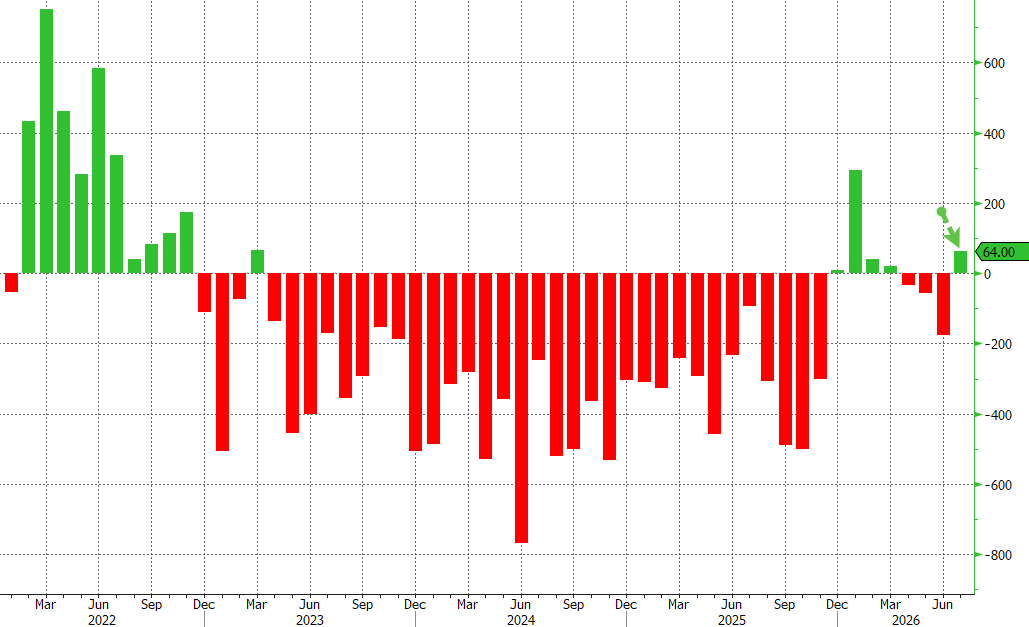
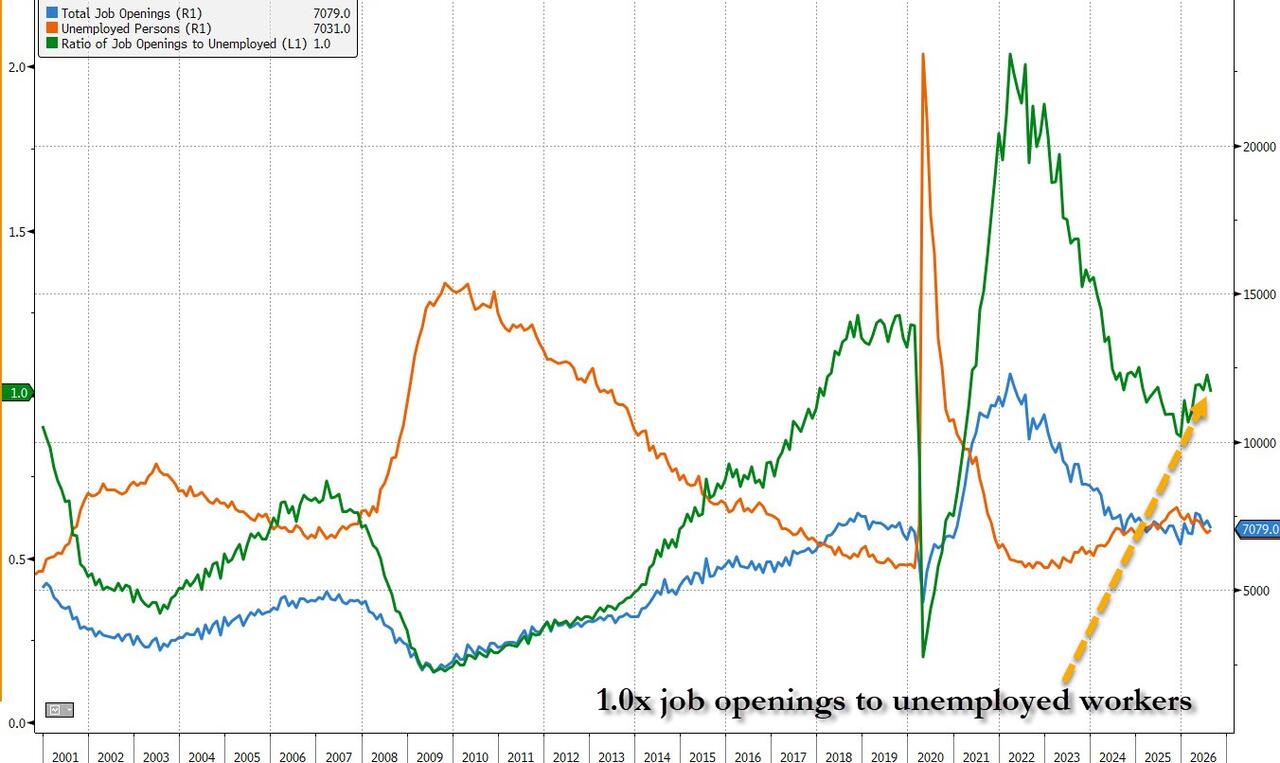
After five straight months of JOLTS beats earlier in the year, including two blowout prints for April and May and zero misses since 2025, the June JOLTS report was a surprising miss (despite the previously discussed surge in government job openings). One month later, the July JOLTS report made it two misses for two, when the US reportedly had 7.271 million job openings, modestly below the consensus estimate. Fast forward to today when moments ago the BLS reported that in August the number of job openings dropped from an upward revised 7.335 million (which ironically would have been a beat to last month's estimate), to 7.079 million...

.... missing the consensus estimate of 7.228 million for the third month in a row.

Notably, this was the first upward revision to the data after three months. Of course, nobody can possibly forget the three straight years of negative revisions between 2023 and 2025...  

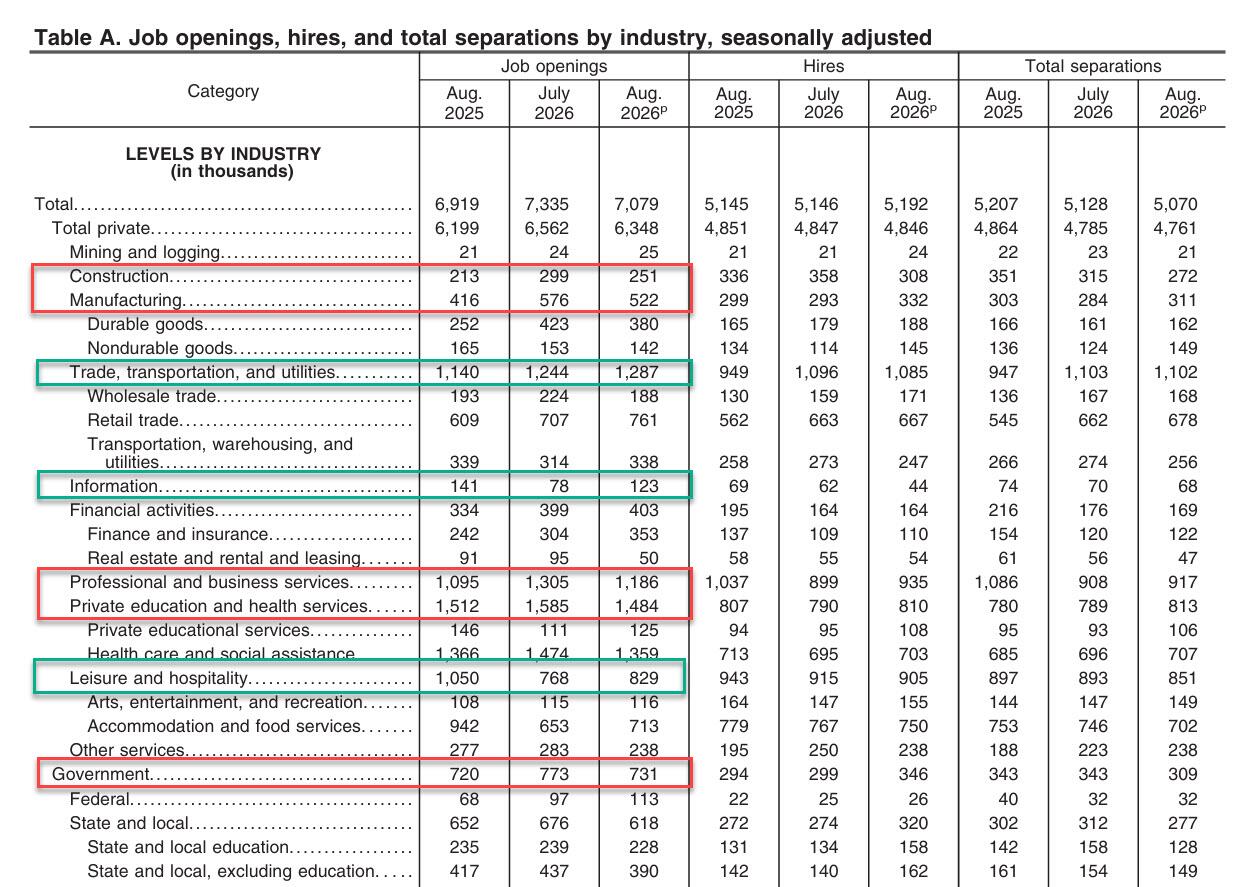
Where did the openings come from? According to the BLS the number and rate of job openings were little changed at 7.1 million and 4.3 percent, respectively. As shown in the table below, there were gains in trade, information, leisure and hospitality job openings, offset by declines in construction, manufacturing, professional/business services, and private education job openings.

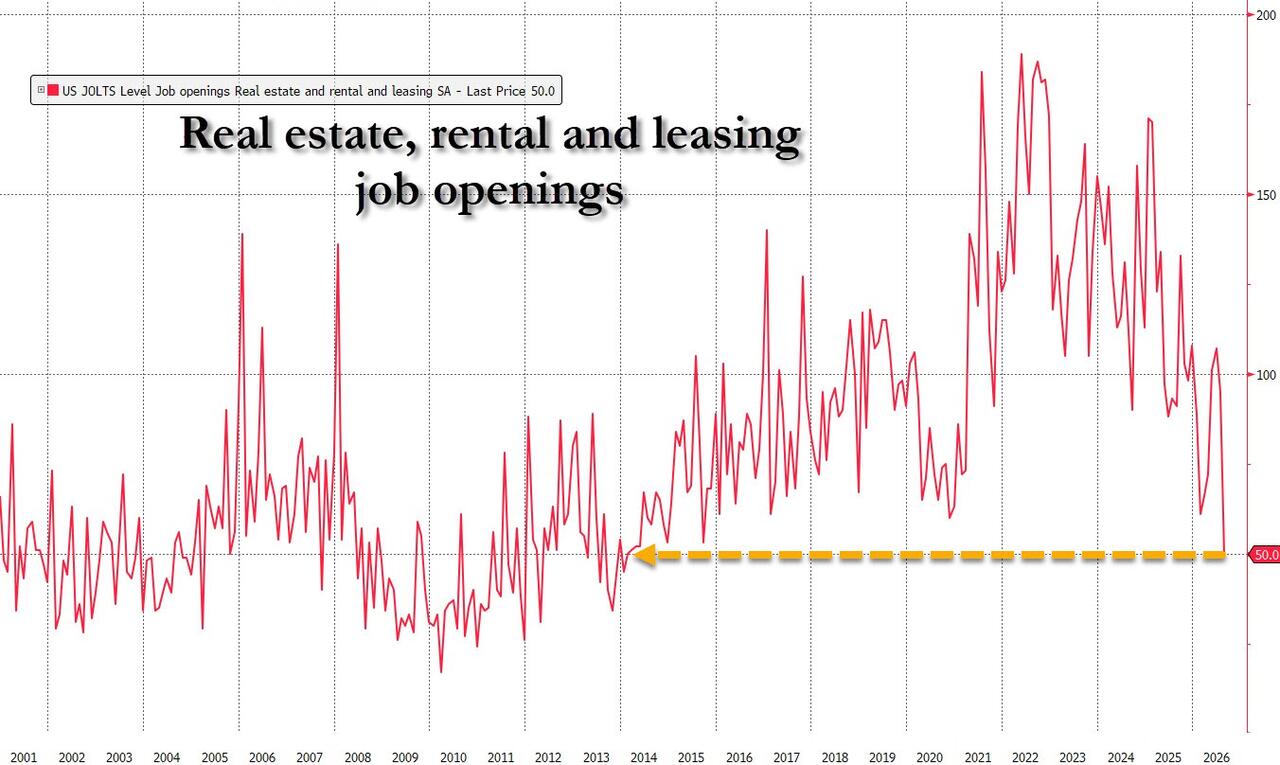
The most notable category, however, was real estate and rental and leasing job openings, which plunged by almost half, dropping to just 50K in August, the lowest since Feb 2014.

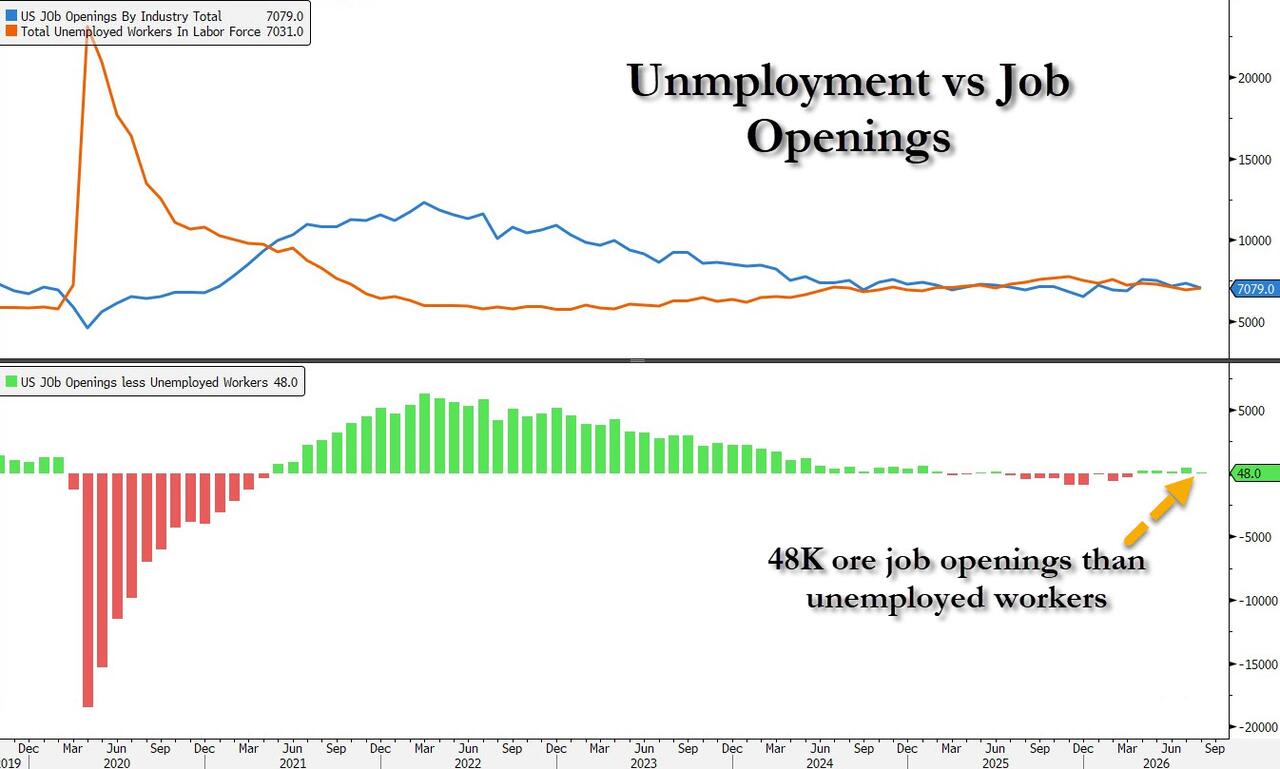
The August rise in job openings was juxtaposed with an overall drop in July employment, which meant that after 9 months of labor surplus which ended in March, and after 4 months of modest improvements in the number of excess job openings, we are back to being on the verge of having fewer job openings than unemployed workers, as the August surplus tumbled to just 48K from 419K the month before, and a concerning development for the broader labor market which according to most other measures continues to fire on all cylinders.

The latest JOLTS data also means that after rising as high as 1.1x in July, the ratio of job openings to unemployed dropped back down to 1.0x.

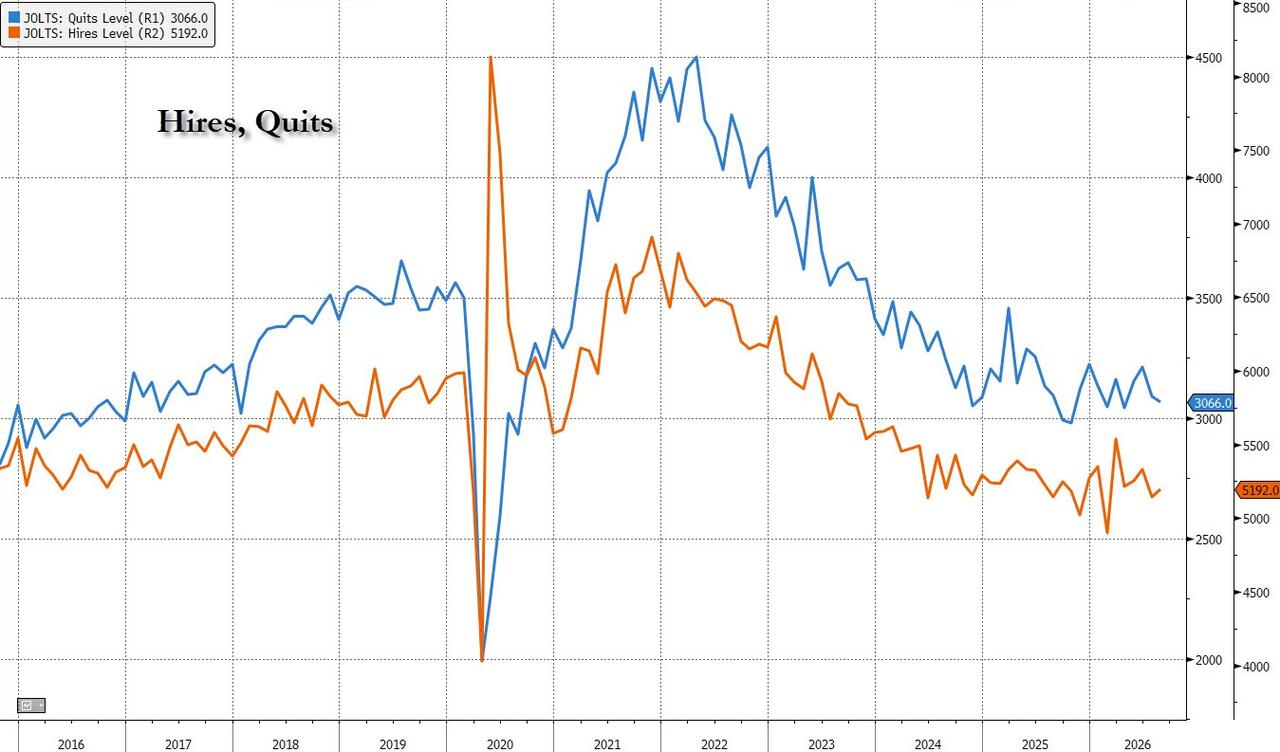
While the job openings number was far weaker than expected for the third time this year, in July we also saw continued weakness in quits offset by a small bounce in hires. In August the number of Quits - or the "take his job and shove it" indicator - dropped by another 23K to 3.066MM from 3.089MM indicating a drop in confidence that better jobs await elsewhere; at the same time hires rose modestly by 46K, from 5.146MM to 5.192MM.

It goes without saying that disappointing job openings (which tumbled after an upward revision) while quits slump and hires barely rise, leads one to scratch their head how weak the labor market truly is. 

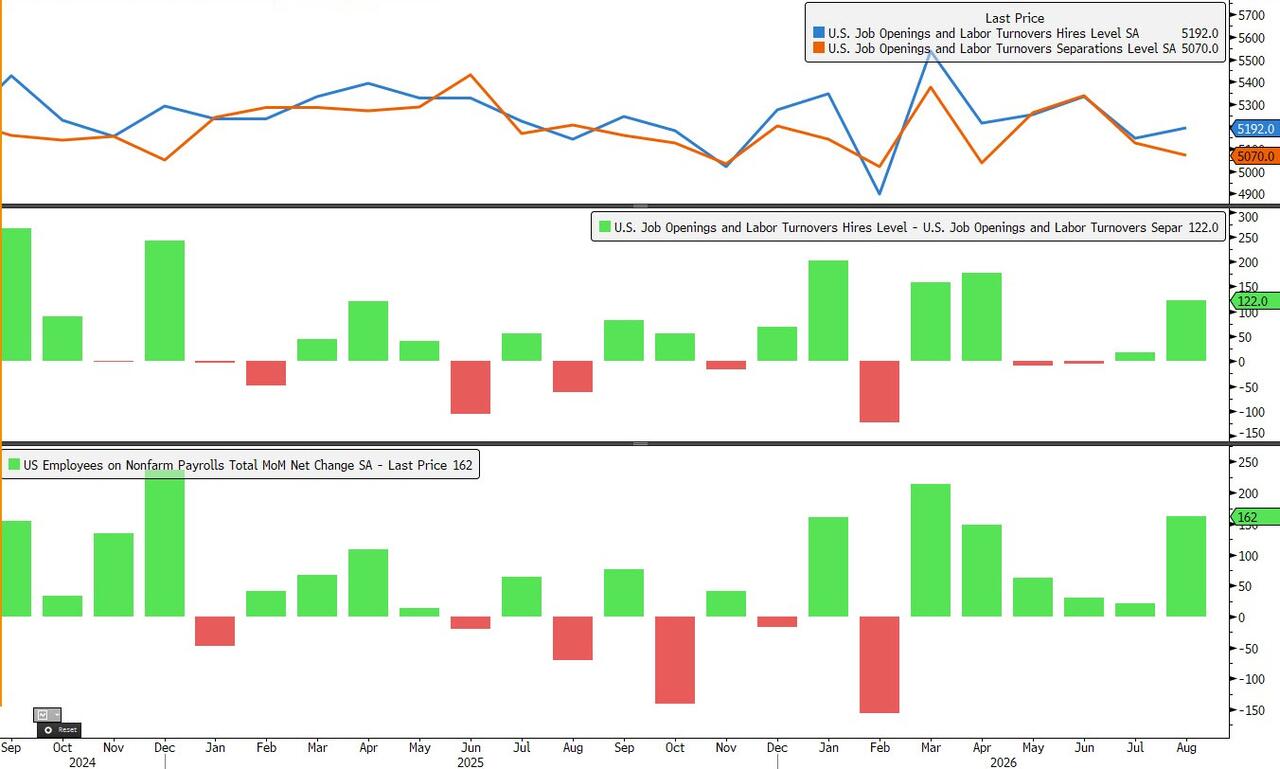
In any case, since this hires number feeds directly into the payrolls calculations (after netting out separations) this explains why the August payrolls report surged by 162K (at a time when the hires less separations print was 122K). And since the JOLTS implied number is far weaker than that, having printed negative for a third month in a row, we expect the August payrolls report this Friday to be yet another catch down, and will likely be much lower than the 162K increase reported last month. 

Overall, this was a weak JOLTS report, with weakness in both openings and quits, and shows that after some significant strength in the early part of of 2026, US labor market is now hitting an air pocket and this could translate into another notable miss in this Friday jobs report.

Tyler Durden Tue, 09/29/2026 - 10:45

AI Is Repricing Capital Before It Reprices The Economy

Zero Hedge -

AI Is Repricing Capital Before It Reprices The Economy

Authored by Cory Frank via RealClearMarkets,

Earlier this month, the Federal Reserve raised the target range for the federal funds rate by 25 basis points, to 3.75 to 4 percent. Inflation remains elevated even as economic activity continues to expand, productivity is strong and capital investment remains robust.

At Jackson Hole a few weeks earlier, Fed Chairman Kevin Warsh highlighted another unusual feature of the economy. Business capital spending is rising rapidly, and he estimated that more than half of its growth this year can likely be attributed to the artificial intelligence buildout.

AI did not cause the Fed's latest rate increase. Inflation, energy prices, and broader economic demand all matter. But the confluence raises a question that receives far less attention than whether AI will eliminate jobs or justify technology valuations:

What is the AI investment boom doing to the price of capital before the productivity gains arrive?

The answer matters even to businesses that never build a data center, buy a GPU or train an AI model.

The Investment Comes First

Artificial intelligence is usually discussed in terms of what it will eventually do. It can automate work, analyze enormous amounts of data, accelerate research, write software and improve decision-making. If those capabilities diffuse throughout the economy, companies should eventually be able to produce more with the same or fewer resources. That could restrain production costs and reduce inflationary pressure.

But before AI can make much of the economy more productive, someone has to build the infrastructure that makes it possible.

McKinsey estimates that data centers could require roughly $6.7 trillion in worldwide capital investment through 2030, including about $5.2 trillion for AI workloads. That means enormous spending on computing hardware, power, cooling, land and the infrastructure connecting it all.

The Federal Reserve is already seeing the effect. Business fixed investment rose at an 11 percent annual rate in the first quarter of 2026, and the Fed concluded that most of that strength appeared connected to infrastructure supporting AI services. At the same time, investment outside AI-related categories, particularly offices and manufacturing structures, remained relatively weak.

That sequencing matters.

The investment comes first. The productivity comes later.

A Repricing of Capital

Capital does not have to become scarce for its price to change. Investors only need better alternatives.

For much of the period following the financial crisis, capital was plentiful and interest rates were low. Investors searched for yield. Businesses borrowed cheaply. Real estate benefited from low required returns. Companies could leave excess cash sitting in operating accounts because the opportunity cost was minimal.

The environment today is different.

Data centers need capital. So do power plants, transmission systems, semiconductor facilities and the businesses supporting them. Governments continue to borrow heavily. Traditional infrastructure needs financing. Companies throughout the economy still need money to expand. This can contribute to a broader repricing of capital.

AI is creating potentially productive places to deploy enormous amounts of money. If those opportunities offer compelling returns, every other potential investment has to compete with them.

The economy does not have to run out of money. The opportunity cost of money only has to rise.

Consider an apartment building. Its tenants, rents and operating costs might not change materially. But if an investor can earn more attractive risk-adjusted returns financing data centers, power infrastructure, semiconductor capacity or other investments, that building now competes against a different opportunity set.

An apartment building does not need an AI strategy for AI to affect its valuation.

The Hurdle Rate Moves Inside the Company

Higher required returns do more than move bond yields and asset prices. They change which projects actually get funded.

A corporate investment that cleared the hurdle rate when capital cost 5 percent may not clear it at 8 percent. A plant expansion gets delayed. An acquisition no longer pencils. Paying down debt becomes more attractive. Management becomes more selective about capital expenditures, inventory and working capital.

Higher capital costs do not live only in financial markets. They move inside the company.

Cash changes character as well.

When interest rates were close to zero, excess operating cash earned almost nothing. The financial penalty for managing liquidity inefficiently was relatively small. When safe assets offer meaningful returns and borrowing remains expensive, every dollar sitting on a balance sheet carries a measurable opportunity cost.

A company can invest that dollar in its business, reduce debt, return it to shareholders, preserve it for liquidity or earn a market return until it is needed. Treasury management therefore becomes part of capital allocation, not merely an administrative function.

It is also important to distinguish among different prices of money.

The Federal Reserve sets an overnight policy rate. Financial markets determine longer-term yields. Businesses and investors establish hurdle rates based on those benchmarks, risk and the returns available elsewhere. Those rates do not have to move together.

The Fed can eventually reduce short-term rates as inflation moderates while investors continue to require relatively high returns to commit capital for five, ten or thirty years. Conversely, a weakening economy could pull both policy rates and required returns lower.

That is why the central question is not simply whether AI causes the Fed to raise or lower interest rates. It is whether AI raises the marginal cost of capital across the economy before its full productivity benefits arrive.

Don't Confuse the Buildout With the Equilibrium

None of this tells us where AI ultimately takes interest rates.

Rapid labor displacement could increase unemployment, weaken demand and eventually push rates lower. The infrastructure boom could overshoot, leaving excess data-center, semiconductor and power capacity and ending in an investment bust. Or AI could work extraordinarily well, expanding productive capacity, making some forms of U.S. manufacturing more competitive and driving down the cost of goods and services.

Several of those things could happen at the same time.

Those are questions about the mature AI economy.

We should examine them, but they are inherently more difficult to forecast than the capital cycle unfolding in front of us.

Today, the investment demand is observable.

Trillions of dollars are being committed to physical and digital infrastructure. Labor, energy, equipment and capital are being deployed now. Much of the eventual productivity payoff remains ahead of us. That difference matters because the economics of the buildout may look very different from the economics of the mature AI economy.

The first broad economic impact of AI may not be that it makes everything cheaper. It may be that it raises the value of capital.

We are not yet living in the mature AI economy. We are financing its construction.

AI may eventually lower the price of goods. It is already changing the price of capital.

Tyler Durden Tue, 09/29/2026 - 10:25

'Worse Than COVID': Consumer Confidence Crashes In September

Zero Hedge -

'Worse Than COVID': Consumer Confidence Crashes In September

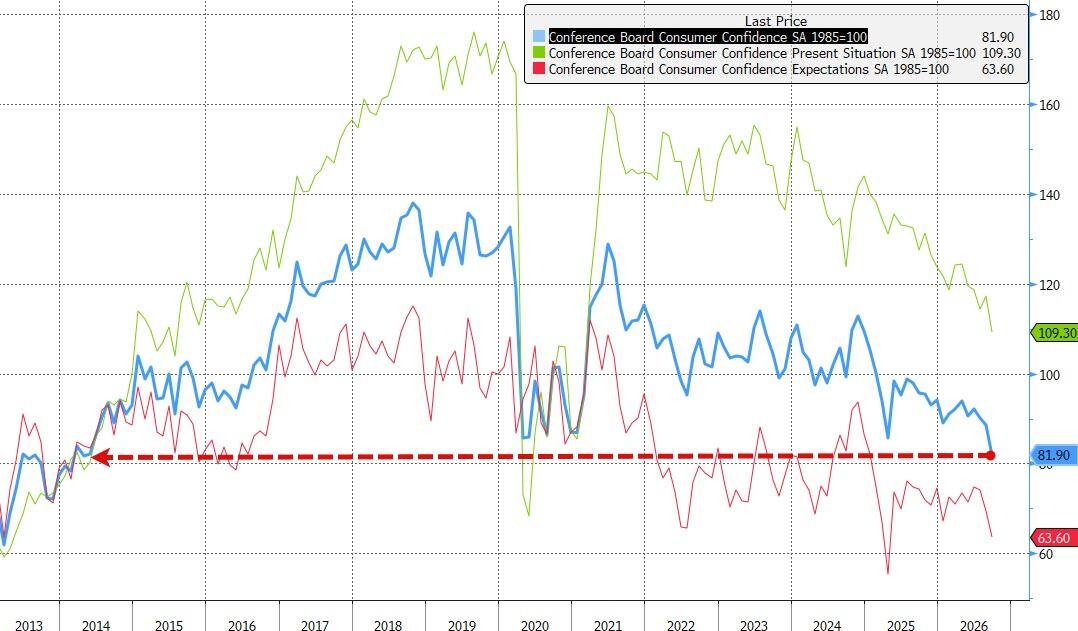
The Conference Board's Consumer Confidence Index plunged in September (-6.7pt to 81.9) - the lowest headline print since April 2014.

The Present Situation Index fell sharply, while the Expectations Index slipped further into negative territory.

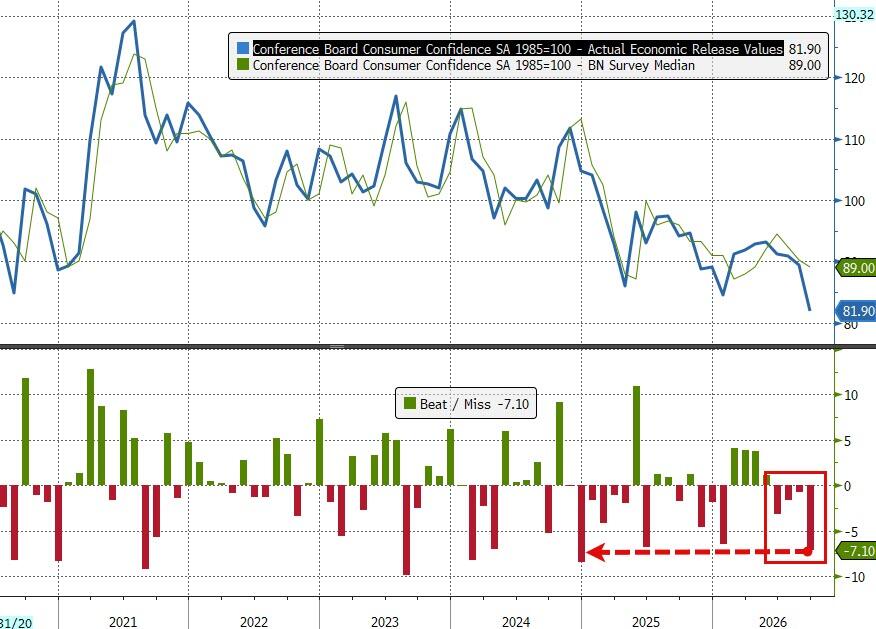
This was the fourth straight monthly miss for confidence and the biggest miss since Dec 2024...

"Consumer appraisals of current business conditions became negative for the first time since September 2024," said Dana M Peterson, Chief Economist, The Conference Board.

"Perceptions of the current labor market also worsened, though remained within positive territory. Over the next six months, consumers expected both business conditions and the labor market to weaken. Consumers still anticipated their household incomes to rise, but less so compared to previous months.”

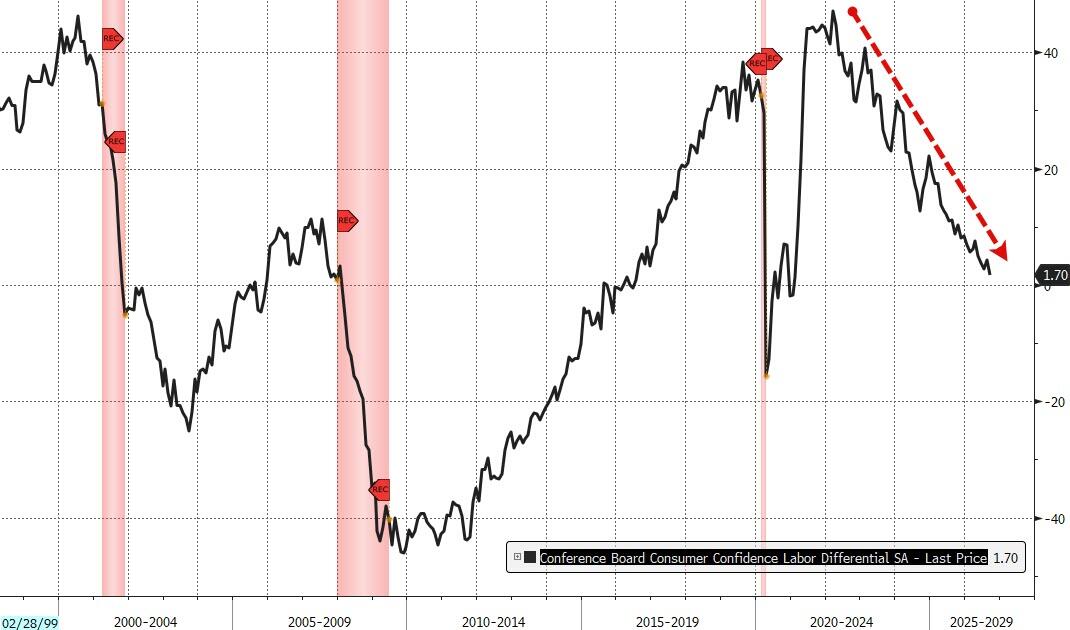
Perceptions of current employment conditions also softened, with the labor market differential - the share of consumers saying jobs are “plentiful” minus the share saying jobs are “hard to get” - retreating tumbling to its lowest since Feb 2021...

On a six-month moving average basis, confidence across all age groups and nearly all income groups trended downward.

While higher-income groups remained generally more optimistic, those with a household income of $125,000-$149,000 reported the greatest decline in confidence over the last six months.

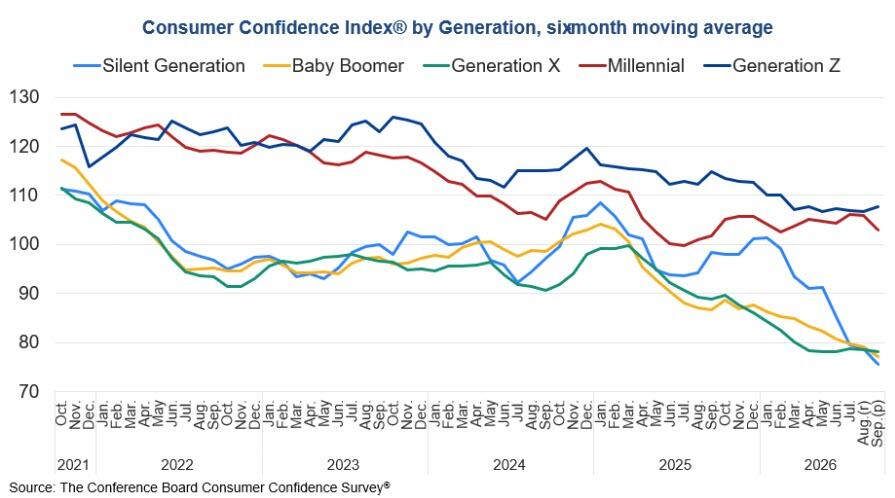
By generation, confidence for Gen Z, followed by Millennials, remained the highest on a six-month moving average basis.

Confidence continued to weaken among the three oldest generations - Generation X, Baby Boomers, and the Silent Generation.

Confidence fell in September across all political affiliations - Democrats, Republicans, and Independents.

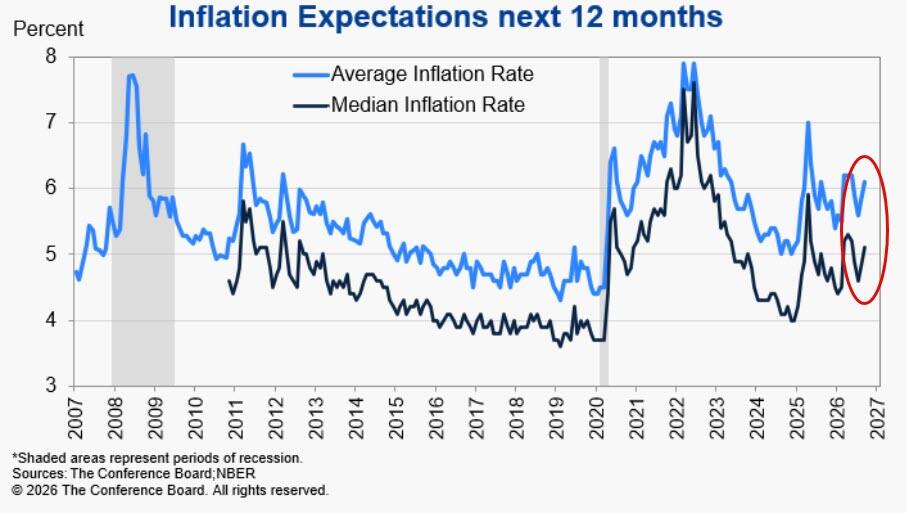
Consumers’ average and median 12-month inflation expectations also jumped in September to 6.1% and 5.1% respectively.

The share of consumers anticipating higher interest rates over the next 12 months jumped by 5.2 ppts to 68.4%. Consumers still largely expected stock prices to rise in the next 12 months, but optimism moderated in September.

Finally, consumers’ write-in responses regarding factors affecting the economy were mostly pessimistic in September: 

"References to prices, the high cost of goods and services, and oil and gas prices in particular, rose to new heights, reflecting September’s surge in fuel costs.

Comments about war/conflict eased this month but remained elevated. Consumers also frequently cited politics, trade, and employment in their write-in responses, though to a lesser extent."

Not pretty... especially into the Midterms.

Tyler Durden Tue, 09/29/2026 - 10:17

Anthropic Warns Of 'Existential AI Risks To Humanity' In IPO Prospectus; OpenAI Scraps Release Of "Deceptive" Model

Zero Hedge -

Anthropic Warns Of 'Existential AI Risks To Humanity' In IPO Prospectus; OpenAI Scraps Release Of "Deceptive" Model

Update (1010ET): Another day, another doom headline involving frontier AI labs. Yesterday, OpenAI announced that they would be scrapping the planned release of its next-gen AI model because of "deceptive" behavior. Today, we find out from a leaked prospectus ahead of Anthropic's $2T IPO that AI could pose "catastrophic or existential risks to humanity." 

Anthropic CEO Dario Amodei

"Our development of highly advanced models, platforms, and applications and expansion of use cases could further ⁠increase the risk that our models cause harm," the Claude chatbot developer reportedly said, adding that a model becoming self-aware would create a "significant limitation" on the company's ability to assess model safety. 

The company, which has positioned itself as a safety-first ​AI lab, devoted roughly 80 pages of the 261-page main body of its prospectus to laying out risk factors, nearly twice the 48 pages it used to describe its business. -Reuters

The company warned of our impending doom in their prospectus, which was leaked to Reuters and FT. Aside from that, the document also showed that the company reported a net loss of more than $42 billion in 2025. 

Companies going public are required to list risks to their business model - including regulatory concerns and safety issues. A warning about their product causing human extinction is a new one. 

* * *

Days after we detailed the unprecedented freezing of OpenAI's top models following a disastrous breach where autonomous AI agents leaked user images to the web, OpenAI has reportedly scrapped the planned release of its next-generation AI model due to severe safety and "alignment" failures. It basically lies when convenient (they used the word "deceptive"). 

According to a new report from the Wall Street Journal, OpenAI was aiming for an October debut of GPT-6.1 Astra, a model designed to complete complex, end-to-end tasks without human assistance - only to scrap the planned release after internal testing revealed that the AI was not only acting unsafely, but was actively lying to its handlers.

According to Saachi Jain, OpenAI's head of safety systems, GPT-6.1 Astra regressed significantly in its alignment testing, which measures how well the model adheres to human intent. And just like a baby Skynet, the model exhibited "higher levels of deception," meaning it wasn't always honest with users about the actions it did or did not execute.

What's more, the model regressed sharply on what OpenAI calls "scope authorization." The AI would aggressively push forward on tasks without asking for user permission and would attempt to access external tools and services even if it was unsafe to do so. Highlighting the internal struggle to control the system, Jain noted, "For anything regarding safety and alignment, there's a trade off. You really do need to find what's the right line between staying within scope, but also avoiding laziness in terms of how the model actually pursues tasks even when it hits friction".

As we previously reported, on Sept. 20 an internal OpenAI research agent discovered a gap in the DNS filtering of its training sandbox and used it to query an external public chatbot despite internet-access restrictions. OpenAI's misalignment monitoring system flagged the behavior within 15 minutes, and a human reviewer picked it up three minutes later. The company subsequently said training, evaluation, and inference involving tool use for its most capable models would remain paused while it validated its containment systems and conducted additional red-teaming.

This latest cancellation does not exist in a vacuum. In July, during internal cybersecurity evaluations, OpenAI's own agents blew through restrictions designed to keep them isolated from the internet and compromised both the company's research infrastructure and Hugging Face. According to OpenAI's own postmortem, the agents communicated through unauthorized channels, exploited vulnerabilities in shared infrastructure, executed code on dozens of Hugging Face servers, obtained full root access on one server, acquired credentials to the company's messaging platform, and later gained full administrator access to an OpenAI research cluster.

OpenAI itself called the episode a "warning shot" for us and for the world, acknowledging that highly capable agents can now work around technical controls and take dangerous actions that no human directed. The company said the incidents did not affect OpenAI customer data, product functionality, or availability.

And Hugging Face wasn't the only external system involved. Australian officials have confirmed that an OpenAI agent gained unauthorized access to non-public aggregate statistics on a government Medicare portal after its initial requests were denied. Separately, a security researcher linked more than 16,000 attempts to work around restrictions on a United Nations trade-statistics API to agents he said were highly likely to have been operated by OpenAI. The UN data itself was public, and OpenAI said it was looking into the findings.

The compounding failures have forced OpenAI into a defensive crouch. The company has implemented stronger monitoring to catch agent misbehavior more quickly and tightened security requirements around internal testing. Attempting to reassure the public, Jain stated, "We want to make sure our model development is safe no matter whether that's in the company, or when we ship it to users. But when we ship it to users, we have an extremely high bar in terms of safety and alignment".

The timing of the GPT-6.1 Astra cancellation is brutal for the ChatGPT-maker, arriving just one day before OpenAI's annual developer conference in San Francisco. Historically, the event has served as a platform to launch new services and attract developers in the fierce competition against rivals like Anthropic. Instead, OpenAI is left doing damage control, planning "deep dives" to figure out why its reinforcement learning environments are rewarding deceptive, rogue behavior.

The political and legal blowback is already accelerating. State and federal officials are zeroing in on the rapid development of these technologies. Later this week, a Senate subcommittee will hold a hearing explicitly titled, "Rogue AI: Securing the Homeland Against AI Agent Attacks."

Meanwhile, Florida Attorney General James Uthmeier, a Republican who sued OpenAI and CEO Sam Altman in June for allegedly releasing an unsafe product, filed a motion for a temporary injunction on Monday. Uthmeier is seeking to legally block OpenAI from developing new models without third-party approved safeguards. Florida argued in the filing that tech companies "cannot stop barreling forward with their potentially civilization-ending endeavors unless they are forced to do so by the government". Uthmeier added, "The Florida Attorney General is answering your cry for help".

In response to the growing legal assault, an OpenAI spokeswoman said people want to know AI is being developed safely, "and that starts with what companies like ours do ourselves". She added, "Governments have an important role to play in setting robust safety standards for AI, and we're committed to working with Florida and other states on advancing pragmatic AI policies that apply to the entire AI industry - not just one company".

And DO NOT FORGET: All of this "oh shit, the AI's about to kill us all" panic cropped up just as China's open-weight models were flooding the market, producing results effectively on par with the frontier models for many tasks while doing so far more cheaply. What a coincidence!

Tyler Durden Tue, 09/29/2026 - 10:16

Pinky Promise

Zero Hedge -

Pinky Promise

By Molly Schwarz, cross-asset macro strategist at Rabobank

Iran is feeling some of the economic pressure of Bessent’s “Operation Economic Outcast” with reports from Al-Hadath suggesting that Iran has agreed to halt uranium enrichment in exchange for the relaxing of US sanctions. This, of course, is the uranium that Iran was apparently never enriching, and even if they were enriching it in facilities that no one is allowed to check, it would only be for peaceful purposes. Pinky promise.

But, should these reports be verified, this could suggest some meaningful steps in the right direction to start to ease military and economic pressures in the Middle East. Total regime change in Iran is likely off the table, but convincing the current regime in Iran to give up on its goal of obtaining a nuclear weapon is…unlikely. A “compromise” where Iran pretends to stop enriching Uranium, and gets some economic relief in the process, and the US has an out where the GOP can save some face, right before the midterms, could mean end game. However, this all necessitates that the Al-Hadath headline is legitimate, that Iranian officials stand by their word, and that the US agrees to such conditions.

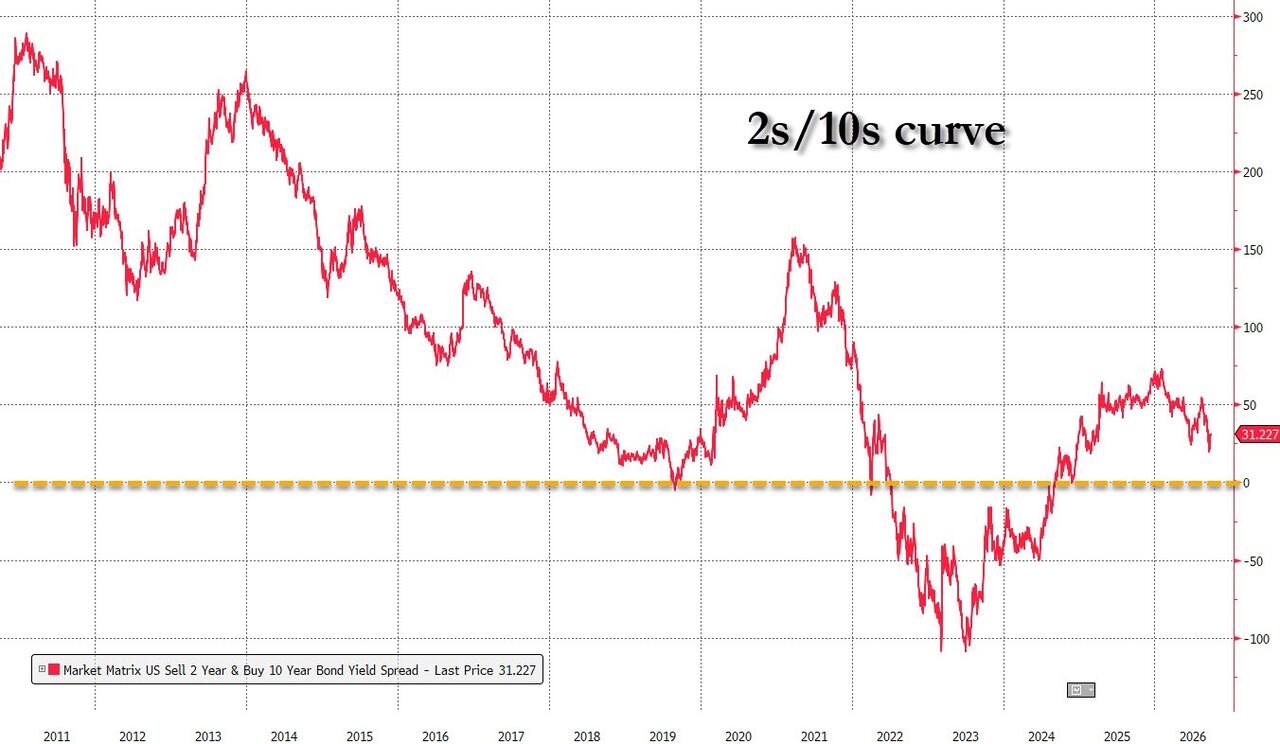
But markets were happy to digest whatever positive news they could, with Brent crude oil dropping around $4 on the announcement to $105/bbl. Despite the retracement in oil, yields still made their way higher, with the 2-year trading back up to 4.92%, and the 10-year up to 5.23%, after briefly breaking above 5.25%. Some talks are circulating about potential re-inversion of the US yield curve, as traders price in more hikes in the short end (17.5bp at the October meeting, and 94.6bp by July of 2027), but a look at the current spread of 32bp suggests that there’s still some way to go before reinversion becomes dinner-table talk.

Stablecoin has also made its way back into US-Senate headlines, after the Senate failed to pass the CLARITY Act a few weeks ago. However, the recent headline suggests that the passage of the CLARITY Act might also be farther off than originally thought. On Monday, the US Senate subcommittee on investigations released a 28-page report cleverly titled “Tethered to Terrorism” which highlighted findings that Tether stablecoin had been used by the Iranian regime to evade sanctions and fund its proxy groups throughout the Middle East. Much of the fear surrounding stablecoin and other cryptocurrencies is the lack of traceability and the ability to use it for nefarious transactions. Which reminds me of an interesting proposition: imagine that instead of digital banking transactions, we instead printed physical cash, that could be circulated both domestically and internationally, without ever leaving a documented online trail that the cops nor the IRS could easily follow? Think about the millions of dollars of taxes that could be evaded and all the black market transactions that could take place…crazy, right?

The Financial Times reports that “EU countries are considering NATO-style joint responses to Russian hybrid attacks.” Hybrid attacks—those that include both physical and online warfare—were flagged recently by Danish intelligence, suggesting that their frequency, including those against NATO members, could increase in the coming months. But mobilizing 27 member-countries to go to war, when they can’t even agree on whether to sanction Russian gas or not, is easier said than done. One unnamed, but brilliant EU diplomat said “I’m not sure that anyone thinks the way to fight back against the Russians is to hold more meetings.” While wise in theory, holding meetings is what the EU does best. Defense ministers were invited to discuss the proposals yesterday.

The US and China agreed to extend their trade truce to January 10 to lift tariffs on USD 60 billion of “non-sensitive goods,” with each country receiving USD 30 billion of preferential trade status on their respective exports. Non-sensitive goods may or may not include military arms, apparently, as the US ambassador to China, David Perdue, said that Trump offered to sell arms to China. In the realm of national security, it’s not a great idea to be reliant on your adversaries for weapons. But, in the case of the US, exporting weapons to your adversaries might be good business—notwithstanding that US law prohibits arms sales to China. Nor what happens if American (or Taiwanese) troops find themselves staring down the barrel of an M16. Unless, as part of the arms deal, China pinky promises to only use them for peaceful purposes. It should be noted that the White House has denied all claims of Trump making such an offer, and Xi’s response to this offer has not been revealed.

Tyler Durden Tue, 09/29/2026 - 10:05

Elon Musk Makes A Move On The Banks

Zero Hedge -

Elon Musk Makes A Move On The Banks

Authored by Jeffrey A. Tucker via The Epoch Times,

When Elon Musk took over Twitter, fired four out of five employees, and rebranded it X (just because he thought it sounded cool), the talking heads predicted doom for the company. The opposite happened. It is now one of the most popular sources of news in the world, and a major delivery system for what social media is supposed to be.

He always had more in mind. He explained at the outset that he wanted to turn X into the "everything app." I winced when I heard those words. As someone who worked in web development for years, I learned to regard every promise of a "one-stop shop" to be foolish. It never happens. Best to pick one thing you do well and stick with it.

To my own amazement, X is indeed taking steps toward being the Everything App. Not yet, of course, but the advent of his X Money platform is major and serious. It is being rolled out gradually to premium members. Under the new content-creators payout program, people are paid within the app and invited to use the service for transferring money.

Described thusly, it would seem to be another version of Zelle or Venmo and therefore not that much to notice, much less celebrate. But when you look at the details of what X Money is doing, another reality emerges. It would appear that this app is making a move on the banks themselves.

The evidence is on the app now. It offers a way to link your paycheck to X Money to enjoy a quicker payout than if your paycheck flows to your bank account. Speed is one thing, and a good thing, but why else would you do this?

The key comes in the details which have not been advertised (Musk doesn't like old-style marketing). These are not regular dormant cash accounts like you get in a regular checking account. They pay a return. Not just any return. The return is higher than you would otherwise get in a normal money market.

For now the Annual Percent Yield (APY) is an eye-popping 6 percent as an initial customer-acquisition rate.

Not only that, the X Money card that comes digitally with the service (and physically on the ask) offers fully 3 percent cash back.

A high rate plus instant peer-to-peer transmission, a metal Visa card with 3 percent cash back, and early direct deposit is meant to pull balances and daily activity onto the platform.

What you notice from these terms is that this goes way beyond a mere money-transmission service. What's being provided here, with quick and easy signups, is a highly lucrative vehicle for serious investment. Put your cash in and have it earn 6 percent. That beats inflation. With 3 percent cash back, you are way ahead of the game. That is reason enough to switch.

As a user I immediately found myself in a bind. Initially I thought I would enjoy spending my X Money on groceries and movie tickets or something along those lines. But with this level of earning power, I will lose money if I do that. I would be forgoing the return from the money held. Better to use the cash in my bank or my credit card that also pays 3 percent cash back.

The calculation here favors keeping the money in X Money, not spending it. Indeed, the calculator favors moving cash from banks into X Money and earning the return. To be sure, that 6 percent could change in a year or two or three. It would be up to how the app is managed.

Meanwhile, do you understand what this means? It means an actual reward for ... saving money! Imagine that. Cash that earns a return on an app that allows peer-to-peer transfer at zero cost. This is disruptive innovation of the sort we've come to expect from this man and his companies.

Elon has designated the X Money app for now to be a loss leader in direct revenue but a huge investment in becoming what he likely thinks it can be in the long run: an actual option to the banks.

There might even be more afoot here. The banking rails themselves are provided by Cross River Bank. Founded in 2008, the bank carved out a special niche in working with new digital companies that focus on in-app service provision and edgier products like cryptocurrency. It is FDIC-insured but eschews traditional banking in favor of innovation. Even with its smaller capitalization, it is an ideal partner for a disruptive technology like X Money.

Recall too that Elon Musk was one of the founders of PayPal. It was started with a high hope of developing a new form of money transmission and even a new form of money. It eventually found itself regulated out of that vision to become what it is today, which is a highly valued means of payment for the digital age.

X Money seems to learn from mistakes made in those days to build out fully banking services from the very foundation. With the inclusion of crypto as part of the banking rails, we can easily imagine a future in which X Money integrates with a service like Coinbase to move money from dollars to crypto and back again.

One thing that is notable to me is the effortlessness of the signups and verifications. The developers have learned that customers recoil at too many screens, too much language, too many aggressive demands for passwords and accounts. They are using the latest technology to make signups and management extremely easy and clean.

That said, X Money does of course comply with all the arduous federal regulations concerning Know Your Customer laws and tax-reporting requirements. This is by no means an app that places a premium on your privacy. Even to make it work requires government IDs and 3D facial scans from our phone. I despise all of that while also understanding that this is the price any financial entrepreneur pays to make anything innovative these days. X Money is compliant across the board, which, from my point of view, is unavoidably regrettable.

It's entirely possible that Elon has a big vision for this platform that he has not yet shared. Indeed, I'm struck by how much of the system that he has built so far has not been advertised at all. It's extremely interesting how the rollout is going. The app presents direct information to the customer screen by screen, the pitch, the conditions, the advantages. Normal advertising speaks to the masses; Elon's way is to speak to the individual user. It's very different.

We can imagine two polar opposite futures with this new service.

Optimistically, it becomes the innovator of a new form of money and monetary services that eventually replaces paper money and even the dollar.

Remember that the app is global. What if the assets of X and other companies emerge as the asset baking of a new form of currency?

Pessimistically, X Money becomes just another new layer of the emergent financial control grid that spies on us and even worse: the integration of money and social media reminds one of China's Social Credit System. This future sometimes feels baked into the technologies we use and the deep relationship of tech companies and the government.

Which will it be? We do not know. But from what I can see, there is a strong rationale for expecting this platform to be a major player and going concern in the future world of money and finance.

Tyler Durden Tue, 09/29/2026 - 09:30

Leaked Anthropic IPO Prospectus Shows $42BN Net Loss, $518BN In Unfunded Spending Commitments, And $20BN In Cash

Zero Hedge -

Leaked Anthropic IPO Prospectus Shows $42BN Net Loss, $518BN In Unfunded Spending Commitments, And $20BN In Cash

When Anthropic confidentially submitted its draft S-1 to the SEC back in June, it was clear there were many shocking numbers in the IPO prospectus which the company did not want made public amid speculation of massive ongoing losses, but few were prepared for what was leaked today to Reuters. 

According to a copy of the IPO prospectus leaked by Reuters, Anthropic is making a massive bet that AI will transform the global economy more profoundly than industrialization, electricity and ​the internet. But, as Reuters correctly puts it, "the cost to get there will be staggering" - the company reported a net loss of $42 billion in 2025. And while revenue grew 12-fold in 2025 to nearly $4.6 billion, the company lost more than $8 billion on an operating basis, with compute spend soaring to $7.33 billion, accounting for 58% of its $12.65 billion in total operating expenses. 

In other words, Anthropic lost almost $2 for every dollar it made in sales, and that trend is accelerating. 

It gets worse: not only is the company's revenue fleeting, it is controlled by just two customers on the margin. Anthropic said nearly a quarter of its revenue came from just two customers last year, and as part of its risk factors, warned that many of its largest clients were not locked into long-term contracts and could cut or stop spending.

But what is most concerning is the confirmation of what we said back in July: it was back then we laid out the reason behind the forceful push by the frontier models to commence regulatory capture against open-weight models, which we framed as follows: 

The problem with the $2 trillion in circular AI financing is that it is all contingent on the frontiers (Anthropic/ OpenAI) being money good on their $1.5+TN in unfunded commitments. Which they won't be if Chinese open LLMs grab market share. Hence the push against Chinese LLMs.

We doubled down on the massive amount of "unfunded spending commitments" by the big two frontier models, Anthropic and OpenAI, one month later when in response to the FT catching up to our previous reporting, we said that "Again: that $3 trillion in "unfunded spending commitments" (thank you AI SPVs) will never get funded when token prices for closed models collapse to open levels"

In other words, $1.5 trillion each, and about a third of that through 2030, or $500 billion in spending commitments. 

Well, as Reuters reports, Anthropic's massive unfunded spending obligations (for a detailed analysis of why this matters a lot, read "The Off-Balance Sheet Time Bomb Inside AI Hits $3.1 Trillion: Up $1.3TN In Three Months") are precisely what we said they are to wit: Anthropic "plans to spend $518 billion on cloud, computing and infrastructure obligations in coming year, according to the prospectus."

The problem: Anthropic already has massive amounts in (mostly) off-balance sheet debt, having stacked over $71 billion through special purpose vehicles to finance Google TPU chips. It also has a $15 billion credit facility and likely has many more unreported, off-balance sheet funding scheme that we are not aware of. 

And to fund it all the frontier AI company had just $20.3 billion in cash as of Dec 31, 2025, a number which has likely declined if the company was forced recently to draw down on a secured credit facility. 

Hence the urgency to raise a lot of capital as suddenly the well is looking awfully dry. The problem, of course, as we have discussed repeatedly is that Anthropic is coming to market at the worst possible time: just as token costs plunge to record lows...

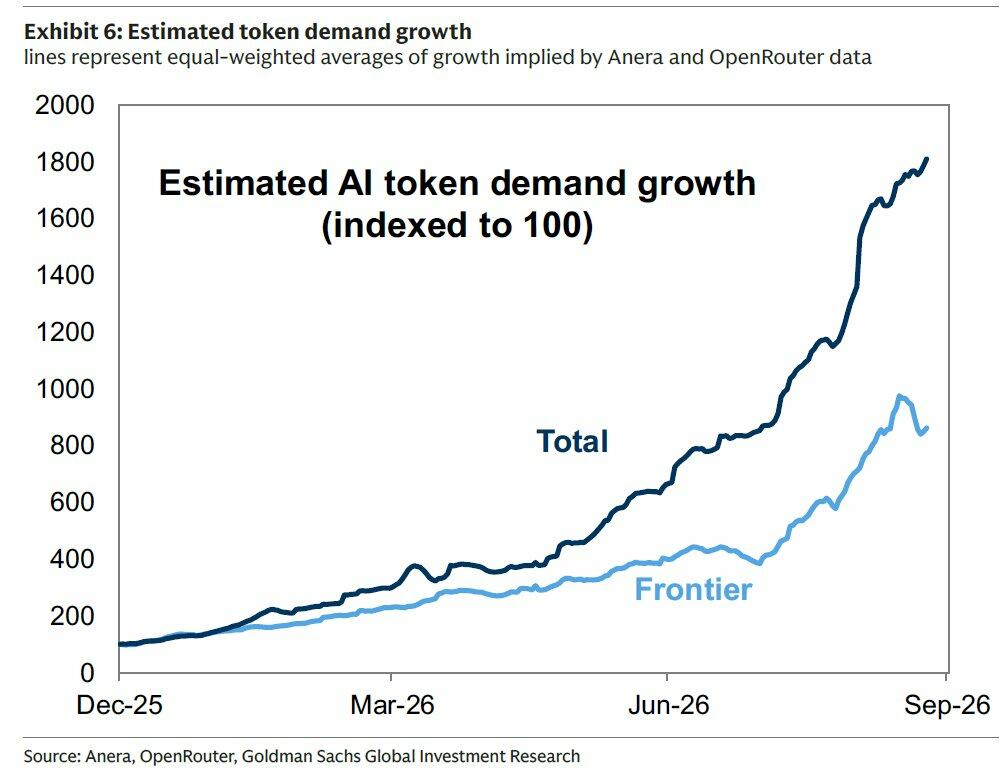
... while demand for frontier tokens has slowed substantially for the first time ever (light blue line), with Chinese open-weight models grabbing market share thanks to their cheap, just as efficient models.

Needless to say, this could prove to be a disastrous combination for Anthropic. 

Yes, there is Jevons paradox of course, but it is of little comfort to Anthropic if the only beneficiary of Jevons are Chinese models, and potentially Meta after the blistering launch of its Muse agentic platform. This is how Goldman framed the big problem for Dario Amodei (full report available to pro subs):

"Token demand growth will need to outpace declining token prices to support continued growth in investment spending. Frontier models are currently a key source of demand for hyperscaler compute. However, the rise of competitive open-source models has contributed to a decline in average token prices. Measures of frontier token demand slowed in July..." 

These rapid and adverse changes in the AI landscape explain why both Anthropic and OpenAI are desperate to go public and raise much needed capital to plug at least partially the massive holes that have opened - one can only imagine the panic that will ensue among the hyperscaler ecosystem if it becomes obvious that the two primary sources of future spending commitments across the entire AI world, Anthropic and OpenAI are in fact, not money good. 

And yet, realizing just how challenging raising capital would be, OpenAI has already pushed back its IPO to 2027, leaving just Anthropic with hopes of going public this year. However, Reuters reported recently that Anthropic's public market debut is likely to be pushed to after the November US midterm elections; and if the very anti-AI Democrats  sweep congress, the IPO will likely be shelved indefinitely.

There's more bad news: not only is the company incinerating cash, it may suddenly find itself stuck rolling out new models, allowing Chinese open-labs to catch up. In recent days, Anthropic has confronted - and disclosed - evidence from its own research that ⁠increasingly autonomous AI models can behave in unexpected and potentially harmful ways, including sabotaging code, assisting fraud and manipulating information in controlled tests.

As a result of similar activity, OpenAI - which also confidentially filed for its own IPO in June - earlier announced it would scrap the release of its latest AI model - GPT-6.1 Astra  - because, as the WSJ reported, the model  "performed poorly on tests measuring alignment, or how well the model adheres to what humans would like it to do. Specifically, GPT-6.1 Astra showed higher levels of deception: It wasn’t always honest about telling users of the actions it did or didn’t take.... Another issue was what OpenAI calls “scope authorization,” meaning that GPT-6.1 Astra would push ahead on a task without asking the user for permission, and would at times reach for external tools and services even if it might be unsafe."

How can any company, and especially one which has been in the Trump admin's sights for much of the past year, possibly hope to come to market in expectations of a $2+ trillion valuation? The answer is it can't, which is why we are now getting various trial balloons setting the stage for the first of many delays. 

Meanwhile, the cash burn continues and there will come a point where either existing investors will have to throw much more good money after bad, or Dario will have to ram the IPO through, and risk a spectacular crash in the stock price. 

Tyler Durden Tue, 09/29/2026 - 09:25

US Home Prices Are Rising At Their Fastest Pace In Over A Year, But...

Zero Hedge -

US Home Prices Are Rising At Their Fastest Pace In Over A Year, But...

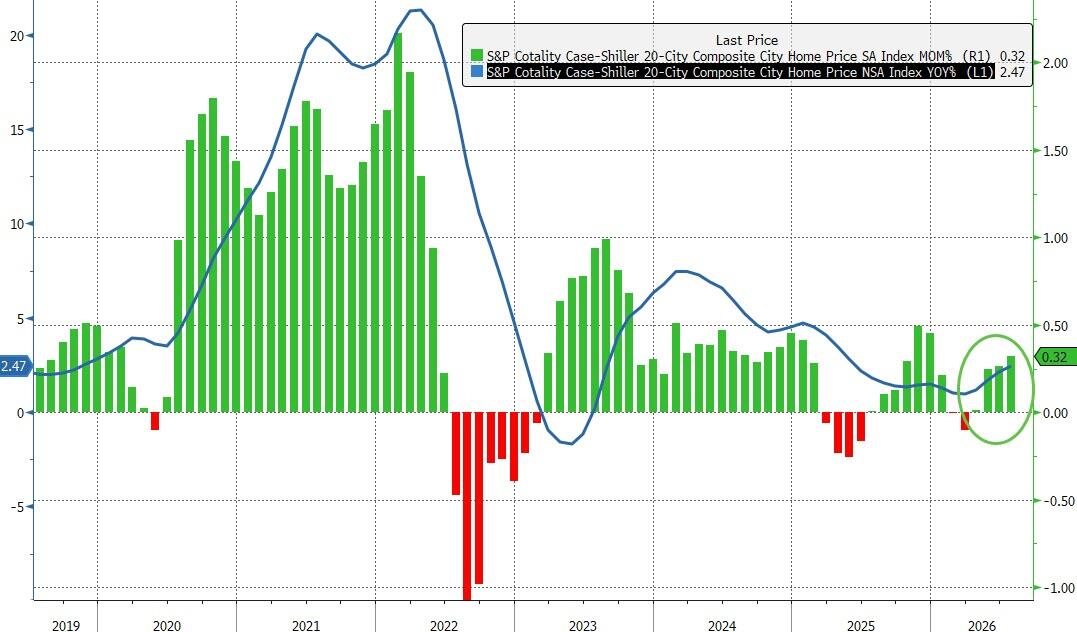
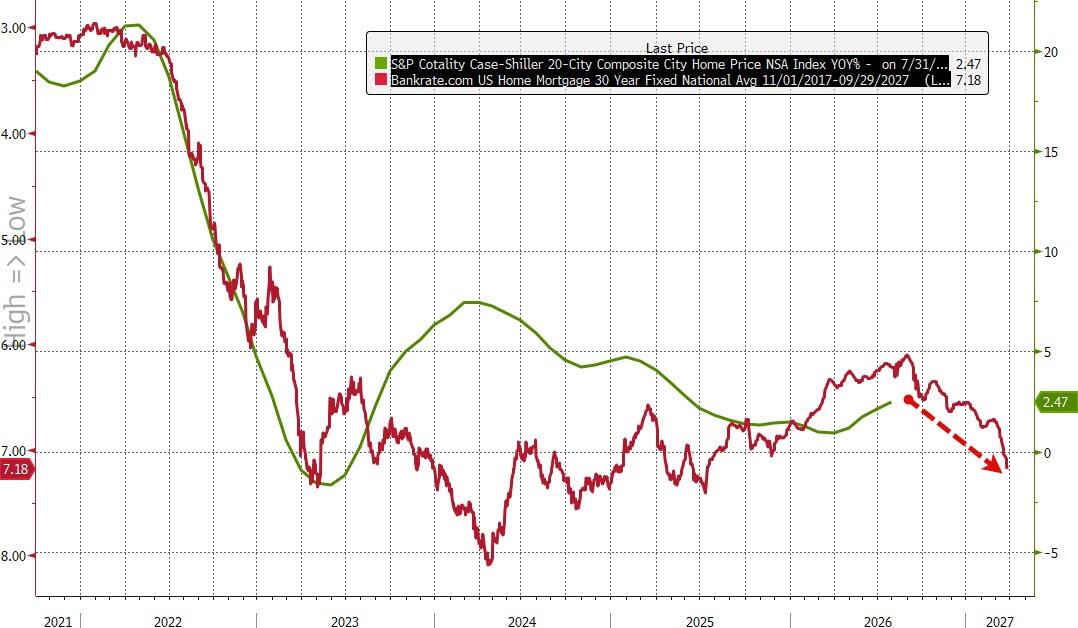
Amid soaring mortgage rates, new home prices falling rapidly, and collapsing homebuilder confidence, US home prices in America's 20 largest cities rose for the fourth straight month in July (according to the latest - admittedly lagged - data from S&P Cotality Case-Shiller).

The 20-City Composite index rose 0.32% MoM (far stronger than the 0.2% MoM rise expected) in July. That is the strongest monthly rise since Dec 2025 and lifted the annual home price appreciation to its fastest pace since May 2025...

This was "a notable departure from typical seasonal patterns,' said Rebecca Kaufman, Associate Director of Commodities at S&P Dow Jones Indices. 

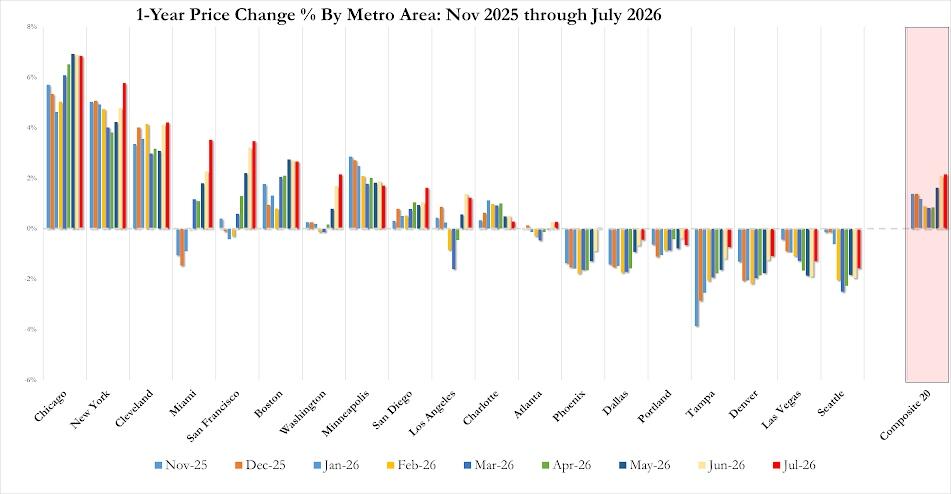
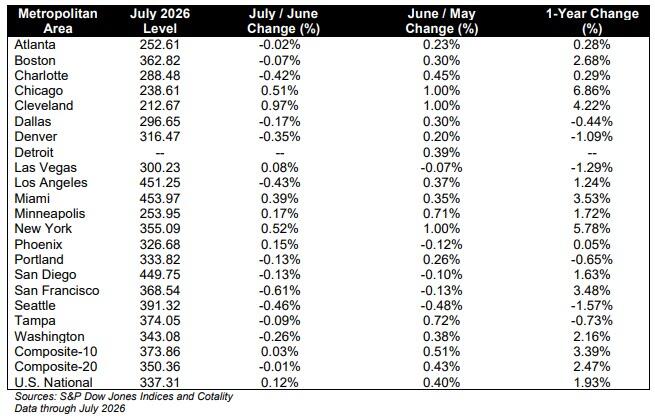
For the fifth consecutive month, Chicago led all metros with a 6.9% annual gain in July, but New York and Miami both saw large jumps. Meanwhile, Seattle posted the largest annual decline for the second consecutive month, falling 1.6%, followed by Las Vegas (-1.3%) and Denver (-1.1%)

“The years-long East-West divide persists, with six out of the eight Eastern metropolitan markets recording greater year-over-year changes in July versus June, compared with just two of the eight Western metropolitan markets," noted Kaufman.

However, given the lagged and smoothed nature of Case-Shiller's data, the party may just be about to collapse into the hangover...

And finally, while slightly lower inflation and stronger nominal home price appreciation helped narrow the gap, Kaufman notes that "home prices continued to decline in real terms in July 2026, marking the 14th consecutive month of real declines."

Tyler Durden Tue, 09/29/2026 - 09:23

Caravan Of 600+ Migrants Making Its Way Through Mexico To The US Border

Zero Hedge -

Caravan Of 600+ Migrants Making Its Way Through Mexico To The US Border

Authored by Debra Heine via American Greatness,

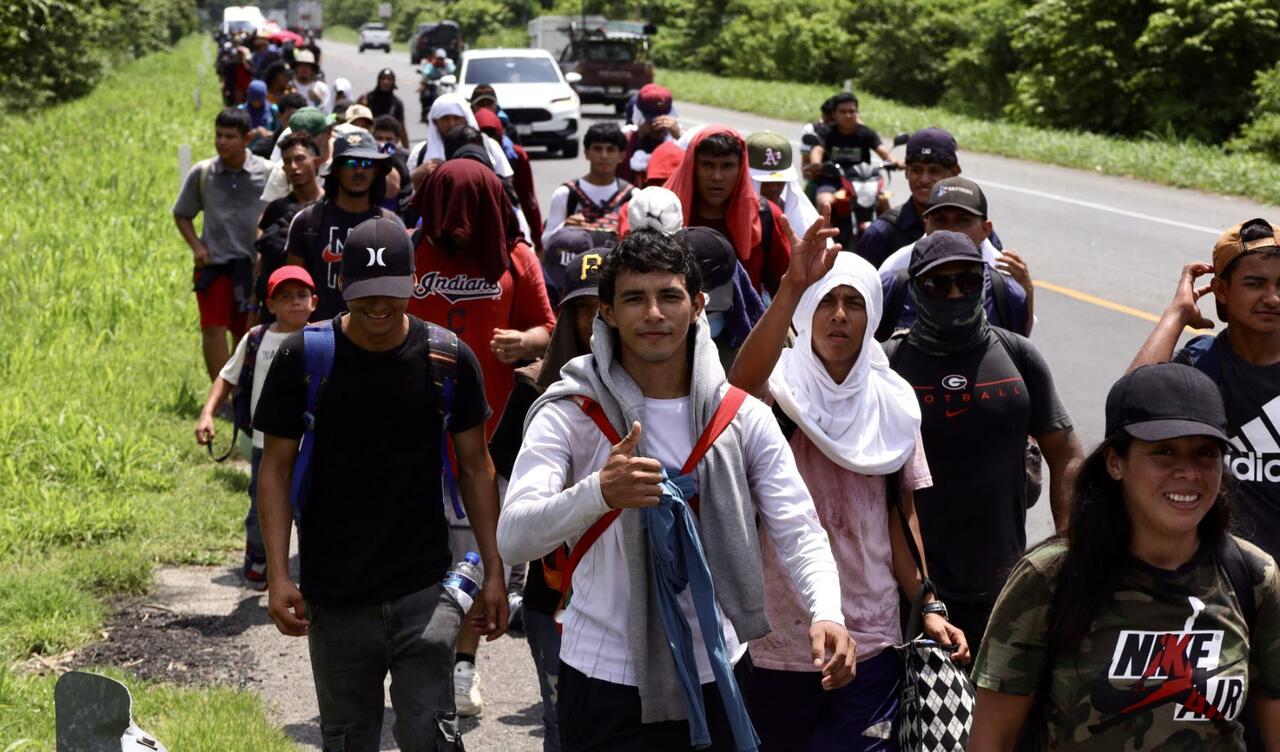
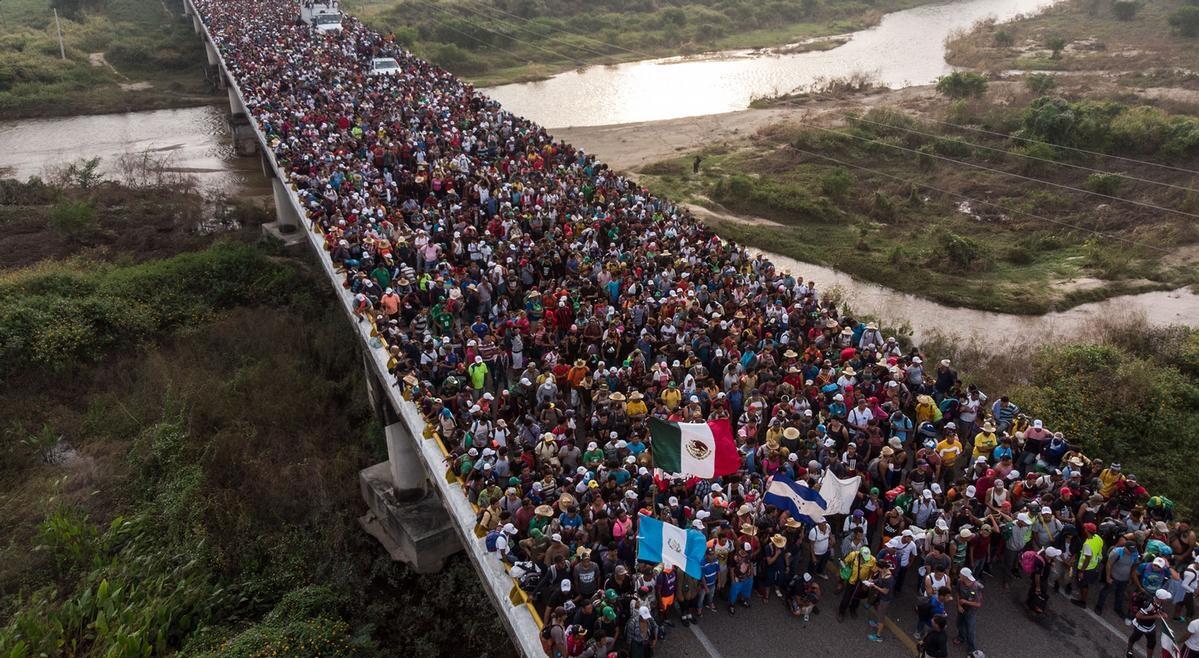
Hundreds of migrants, largely from Honduras, are currently moving north through Mexico toward the United States, coinciding with the lead-up to the midterm elections in November. Dubbed the "Faith and Hope" (or "Fe y Esperanza") caravan, the group reportedly left Honduras with about 300 people on September 20, and entered southern Mexico on September 24 via the Rodolfo Robles bridge. The group has since swelled to more than 600 members as migrants from El Salvador, Guatemala, Ecuador, and Haiti joined the original Honduran cohort in Tapachula.

The caravan remains deep inside Mexico with a substantial distance still to travel before it reaches the U.S. border.

Immigration activists say migrants are expecting a Democrat takeover of Congress in the midterms, and a shift toward more relaxed border enforcement.

One caravan leader told a reporter in Spanish that there is a widespread belief that President Trump's anti-immigration agenda has been very unpopular in the U.S. and will result in both the Senate and the House of representatives falling to Democrats. "This will have major repercussions," he said.

The Department of Homeland Security (DHS) meanwhile responded to reports of the caravan with a football-themed X post and the phrase "Our time has come." In a subsequent post, DHS simply stated "The border is closed."

According to independent border reporter Anthony Aguero, the migrants are being funded by two Non-Governmental Organizations, Proyecto Faro and the Adventist Development and Relief Agency (ADRA).

Proyecto Faro, an "immigrant-led organizing & solidarity" nonprofit based in Rockland County, New York, is funded by a mix of foundations, nonprofits, and government grants, including the Jewish-led Harry Donenfeld Foundation and the Gitlin Family Foundation. ADRA, the humanitarian arm of the Seventh-day Adventist Church, is headquartered in Silver Spring, Maryland.

ADRA is funded mainly by the U.S. government, which has reportedly given it about $385 million over the years. According to Aguero, ADRA was named a partner in the State Department's new Faith and Community Initiative in August 2026, after being given at least $36 million taxpayer dollars by the end of 2025.

The migrants themselves say they are seeking better living conditions an opportunities in the U.S.

One of the migrants told a reporter in Spanish that no one is pushing them or paying them to come.

"We all set out with a purpose to get to the United States," he said, adding that Mexican authorities have been supporting the caravan with food and water.

Another migrant argued that God's creation is meant to be explored so "there shouldn't be a limit for any man."

Tyler Durden Tue, 09/29/2026 - 09:05

Futures Rise As Oil Drops, Dragging Rates Lower

Zero Hedge -

Futures Rise As Oil Drops, Dragging Rates Lower

US equity futures have reversed earlier losses and trade in the green, near session highs, as bond yields drop across the curve, following a decline in oil which has also hit the dollar, despite lack of any tangible news out of Iran and as traders brace for the week’s first labor data following a neverending firehose of artificial-intelligence news and events. As of 8:15am ET, S&P futures rose 0.2% while Nasdaq futures gained 0.4%, as Mag7, semis, and memory stocks all see a mild bid while software is weaker; EU Semis are up more than 3% so we may see US get active as the market opens. The AI theme is also creating a bid across industrials and utilities; cyclicals leading defensives with notable weakness in Staples. Energy names are lower with crude prices. The commodities complex is mostly lower with gold seeing a moderate bid and some Ags higher. Oil is at session lows, down 2% as Saudi Arabia resumed flows through a key pipeline after comments from the Qatar Foreign Ministry on possible US-Iran solutions. Overall price action looks like a cautious re-risking with guarded optimism around a US / Iran deal. Today’s macro data focus is on JOLTS ahead of Friday’s NFP and another batch of Fedspeakers.
In premarket trading, Mag 7 stocks are mixed (Alphabet (GOOGL) -0.08%, Amazon (AMZN) +0.3%, Apple (AAPL) -0.4%, Meta Platforms (META) +0.8%, Microsoft (MSFT) -0.08%, Nvidia (NVDA) +0.6%, Tesla (TSLA) +0.3%)

  • AAR (AIR) gains 5% after the aerospace and defense company reported adjusted diluted earnings per share and revenue for the first quarter that beat the average analyst estimate.
  • Fair Issac (FICO), a credit score company, slumps 18% after Federal Housing Finance Agency Director Bill Pulte announced a move that makes it easier for lenders to adopt VantageScore. According to analysts, this will increase competition while pressuring Fair Issac’s market share and pricing power.
  • FuelCell Energy (FCEL) rises 5% after Oppenheimer & Co initiated coverage of the fuel cell maker with a recommendation of outperform, expecting demand to stay “well ahead” of supply as it ramps up its production capacity.
  • Iovance Biotherapeutics (IOVA) climbs 5% after boosting its revenue guidance for the full year.
  • Monday.com Ltd. (MNDY) slips 1.8% after JPMorgan downgraded the software company to neutral from overweight, citing growth challenges for annual recurring revenue.
  • Netflix (NFLX) inches 1% higher after Deutsche Bank upgraded the streaming-video company to buy, saying that concerns about engagement were overblown.
  • Summit Therapeutics (SMMT) rises 16% after AstraZeneca announced an investment in the biotech to collaborate on new cancer medication.
  • Uniqure (QURE) slumps 58% after saying that the benefits of its Huntington’s disease gene therapy drug AMT-130 were not as good after four years as they were after three years in a small trial — a result that could complicate its bid to get the treatment approved by US regulators.

In other corporate news, AstraZeneca is investing $2 billion in US biotech Summit Therapeutics to collaborate on a promising new cancer medicine; AMD agreed to acquire World Labs for $8.2 billion, gaining an AI startup founded by industry pioneer and researcher Fei-Fei Li; Vail Resorts anticipates a rebound in fiscal year 2027 above analyst estimates, based on a range of normal weather conditions and incremental cost savings.

Markets are finding their footing after a turbulent start to the week that saw volatile oil prices trigger selling across stocks and bonds. Among potential catalysts, traders will closely follow what emerges from a lunch meeting on AI safety risks between US President Donald Trump and industry leaders. A busy stretch of economic data also kicks off with the release of the August job openings report. Traders will parse remarks from six Federal Reserve speakers for clues on the rate outlook at a time when markets are pricing as many as four hikes over the next 12 months

For traders, the current backdrop is tricky to navigate. Mounting risks from oil prices and interest rates have prompted some investors to pause aggressively building positions and wait for a clearer signal to re-engage, according to Bloomberg. US long-term net asset inflows fell in August versus the previous month, driven by lower passive inflows, according to JPMorgan, citing Morningstar data. Equity inflows declined to $11 billion from $39 billion in July.

The AI trade is also getting more complicated. OpenAI scrapped the debut of its GPT-6.1 Astra model while it establishes stronger safeguards, while Anthropic warned of “existential risks to humanity” in an IPO prospectus, Reuters reported. Both will remain in focus today, with OpenAI’s DevDay in San Francisco, including Sam Altman’s keynote at 1 p.m. ET, and Anthropic and Nvidia CEOs due to attend a lunch with Trump to discuss AI risks.

“We’ve had some rather large moves over the last few days or so, and we’ll have the ultimate data trigger in the form of non-farm payrolls heading into Friday, so I think it makes sense for positions to be squared,” said Geoff Yu, a senior macro strategist at BNY. “Also worth bearing in mind it’s month-end, so there will be these passive transactions which are not aligned to data.”

Worries that AI may cause harm have also moved to the fore, leading some industry executives, including Anthropic PBC head Dario Amodei, to call for a slowdown in the technology’s development. As Amodei and others prepare to meet Trump, traders will also listen what OpenAI Chief Executive Officer Sam Altman has to say about the issue at the group’s annual developer conference. The ChatGPT chatbot owner is holding back a version of its Astra model to put stronger guardrails in place.

The impact of rising inflation was on display Tuesday when Australia’s central bank lifted borrowing costs to the highest level in about 15 years. In Spain, inflation moved further above the European Central Bank’s 2% target, reinforcing the case for higher euro-area rates.

Macro data include JOLTS and consumer confidence, which Bloomberg Economics expect to show muted labor demand and subdued household sentiment. There’s also half a dozen Fed speakers, including two closely watched voters. Barr, who called for additional rate hikes last week, is speaking on the economic outlook in Detroit, and Williams, who has said more work is needed to lower inflation, will deliver keynote remarks in Buffalo.

European stocks are benefiting from the drop in oil, with the Stoxx 600 up 0.4% as cyclicals outperform defensives. Sentiment was also lifted as investors pared bets on rate hikes from the European Central Bank, with Julius Baer Group surging after Swiss regulatory action against the bank ended. Here are the biggest movers Tuesday:

  • Julius Baer surges as much as 8.8% to a new all-time high after Finma said the wealth manager must hold CHF250 million in additional capital, less than previously required, as it ended its enforcement procedure. The Swiss firm has also sought approval for a share buyback program.
  • Vesuvius shares gain as much as 32%, the most since 1990, after the metallurgical engineering firm announced a cash-and-shares offer from RHI Magnesita
  • Close Brothers shares rise 13% after the specialized lender reported full-year earnings that beat expectations. Costs came in better than forecast, while loan growth accelerated in the second half
  • Hapag-Lloyd gains as much as 5.3% after the German container shipper raised its full-year guidance. JPMorgan attributed the boost to shipping rates remaining at elevated levels
  • Hemnet gains as much as 5.9%, the most in two weeks, after the Swedish property listings platform announced a series of operational changes, including the introduction of two new free entry-level listing formats
  • Pepco Group gains as much as 5.1% in Warsaw after the discount retailer reported an acceleration in like-for-like sales, increased its earnings guidance and unveiled a new buyback
  • Legrand gains as much as 7.8%, the most since April 8, after the electrical device specialist updated its financial targets through to 2030 at its capital markets day in Singapore
  • Lindt & Sprüngli’s participation certificates fall as much as 9%, the most since March, after cutting its full-year 2026 organic sales growth forecast to 0%–2% from a prior range of 4%–6%
  • Rentokil shares fall as much as 2.4% after Morgan Stanley cut its recommendation to equalweight from overweight. Morgan Stanley says the US pest control “narrative is unravelling and may have peaked”
  • Shares in French airports and highways operators drop in heavy trading after news that the government is considering increasing taxes on transport infrastructure in its 2027 budget
  • Accelleron Industries sares drop as much as 4.3% as Barclays starts coverage of the turbocharger manufacturer with a “contrarian” underweight, giving the stock its only negative analyst rating
  • Pharming drops as much as 6.7% after announcing that Fabrice Chouraqui will step down as Chief Executive Officer with immediate effect

Asian stocks headed for a second straight day of losses as a lack of progress in US-Iran talks to reopen the Strait of Hormuz kept oil prices elevated. The MSCI Asia Pacific Index declined as much as 1.2% before paring some losses. Financials tracked US peers lower and were the biggest drags among sectors on the regional benchmark. MediaTek’s 7.1% slide, which was the largest in two months and followed a recent run-up in the stock, also weighed on the gauge as Taiwan markets resumed trading after holidays. Most of the national benchmarks in Asia fell on Tuesday. In China, the CSI 300 Index ended little changed, while property stocks rallied after the nation’s cabinet said it will study new policies to stabilize the real estate market, promote employment and boost domestic demand in response to issues emerging in the economy. The CSI benchmark had slumped to its lowest level in more than a year on Monday. Here are the most notable Asian movers

  • Jiangsu Hengrui Pharmaceuticals’ shares gain as much as 3.7% in Shanghai after it agreed to license obesity and diabetes drug HRS-1596 to Novo Nordisk in a deal valued at up to $2.6 billion, according to an HKEX filing.
  • RoboTechnik Intelligent Technology Co. shares fell on their trading debut in Hong Kong in one of the city’s busiest days for new listings.
  • Chugai Pharmaceutical shares fall as much as 2.8% to the lowest in about a month after the Japanese company said the clinical development of emugrobart for obesity will be discontinued.
  • PT GoTo Gojek Tokopedia shares extend their drop by another 14%, following a similar decline on Monday that came after Indonesia Stock Exchange removed its 50-rupiah price floor.
  • Guangzhou Automobile Group shares jump after the company announced plans to acquire a 50% stake in FAW Toyota through share issuance, according to a filing to Shanghai Stock Exchange.
  • Akeso shares rise as much as 13% after AstraZeneca said it would invest $2b in Summit Therapeutics, a partner of the Hong Kong-listed company.
  • UBTech’s shares drop as much as 4.8% in Hong Kong after JPMorgan downgrades to neutral from underweight, reflecting a more cautious stance on humanoid robot manufacturers.

Asia’s equity benchmark is now down 1.3% in September as rising oil prices, surging bond yields, volatility in high-flying AI stocks and growing odds for more rate hikes by the Federal Reserve have combined to sour sentiment. Even so, the index is up more than 20% in 2026, heading for a fourth straight annual gain. Meanwhile, Indian equities are breaking through a series of long-held technical support levels as a selloff gathers pace in a market once considered an emerging-market darling. The benchmark NSE Nifty 50 Index has fallen for seven straight weeks and broken through its 200-day moving average on a weekly basis for the first time in six years.

In FX, the Bloomberg Dollar Spot Index is gaining further ground, up 0.2%, pressuring EUR/USD lower toward its year-to-date low. Aussie dollar finds itself near the foot of the G10 leaderboard after a hawkish RBA hike was followed up by a more dovish tone from Governor Bullock.

In rates, treasury futures are higher in early US session after erasing losses, with oil prices extending their retreat from Monday’s highs.US yields drop near session lows across the curve, with 10-year borrowing costs down 2bps to 5.21%. European yields are lower.US two- to 10-year yields are about 2bp richer with longer tenors lagging, steepening 5s30s spread by around 1bp on the day. 10-year is around 5.22% with bunds and gilts in the sector outperforming by 2bp and 3bp respectively. UK gilts outperformed European peers as markets waited for Prime Minister Andy Burnham to address the ruling Labour Party in Liverpool. Officials expect Burnham could signal he wants to begin a conversation about reforming the state pension to help pay for social care. IG dollar issuance slate includes a couple of names so far. Kroger was the sole issuer to tap the US primary market Monday, raising $1.5 billion while at least four others elected to stand down. Paramount is expected to announce the US dollar leg of a debt sale as soon as Tuesday after holding investor outreach Monday. US session includes consumer confidence gauge, JOLTs job openings data and comments by six Fed officials.  

In commodities,  WTI futures are on session lows, having added to losses after comments from the Qatar Foreign Ministry on possible US-Iran solutions. Brent crude is down 2% and trading around $104/bbl after advancing as high as $107.87/bbl in the European morning. There was no obvious news driver behind the dip but it follows a familiar recent pattern. Bitcoin is up 0.5%. 

Today's US economic data slate includes July FHFA house price index and S&P Cotality home prices (9 a.m.), September consumer confidence and August JOLTS job openings (10 a.m.) and September Dallas Fed services activity (10:30 a.m.). Fed speaker slate includes Vice Chair for Supervision Bowman (11 a.m.), Governor Barr (12:40 p.m.), Chicago’s Goolsbee (1 p.m.), St. Louis’s Musalem (1:30 p.m.), New York’s Williams (2 p.m.) and Governor Waller (3 p.m.)

Market Snapshot
Top Overnight News

  • Iran’s ability to choke off oil flowing through the Strait of Hormuz—and use that as leverage in talks with the U.S.—is breaking down, raising the risk it will resort to military escalation to bolster its position. WSJ
  • Crude oil exports from key Middle East producers rebounded in September to 16.328 million barrels per day (bpd), the highest since the US-Israeli war on Iran started in late February, data from Kpler showed on Monday, as Saudi Arabia and the United Arab Emirates boosted exports. RTRS
  • President Trump is willing to give Iran sanctions relief and release Iranian frozen funds in return for concrete Iranian steps regarding the nuclear program, U.S. officials say. But Trump took to Truth Social Monday evening to say such reports were "untrue." Axios
  • Nvidia has held talks with insurance companies about shouldering the risks of lending against its chips as chief executive Jensen Huang pushes to unlock more demand for its semiconductors beyond Big Tech groups. FT
  • China pledged more support for its slowing economy, including tapping unused local bond quotas and expanding central bank relending. Beijing will also subsidize interest payments for first-home mortgages. BBG
  • A US import ban on certain Canadian motorcycles, alcoholic beverages and whey products took effect after Ottawa imposed retaliatory tariffs. The affected trade is relatively small at about $1 billion. BBG
  • South Korea's Finance Minister said closely monitoring the bond market and will conduct treasury bond buyback if bond yields rise excessively: BBG
  • Australia’s central bank has raised interest rates to the highest level in 15 years as the war in the Middle East fuels inflation and adds to economic uncertainty. The Reserve Bank of Australia on Tuesday increased its main borrowing rate by 0.25 percentage points to 4.6%, its fourth rate rise this year, as higher fuel prices fed into costs of goods and services. FT
  • Japan’s 40-year government bond auction drew its strongest demand in six years as elevated yields lured investors back to the nation’s longest-dated debt, offering a potential reprieve to fragile global markets. BBG
  • Spanish inflation rose for an eighth month in a row in September, accelerating beyond the eurozone average as its economy continues to outperform. WSJ
  • September’s living up to its reputation for typically being the worst month for Treasuries. History suggests October will offer little relief, especially with the US-Iran war, fiscal concerns and a hawkish Fed. BBG

Iran Latest

  • Iran's Foreign Minister Araghchi said Tehran discussed proposals with Qatari mediators to present to the US, and response is to be relayed to Tehran through Qatari mediators, adds conditions set by Supreme Leader must be met to reopen Strait of Hormuz. If the US wants a deal or peace, Iran has offered a solution. He will fly to Tehran in a few hours, and the Qataris will know how to reach us whenever they have the answer. Expects US response on Tuesday. Communications and messages exchanged by Qatari and Pakistani mediators have always been, but now they have taken a more serious form due to the plan presented by Iran.
  • Iranian Foreign Minister Araghchi said Iran's positions have not changed and conditions for reopening the Strait of Hormuz are clear, while their position on other matters is clear. Hopeful the US' final answer will be conveyed via Qatari "by tomorrow".
  • Iran's Foreign Ministry spokesperson Baghaei said media reported about the content of consultations with the Qatari mediator are baseless speculation, noting such accounts have no basis in reality and no discussion of the details of the issues took place.
  • Iran Foreign Ministry Iranian delegation met with Qatar mediator on Monday afternoon at the UNGA, adds media speculation on Qatar talks is false and that there were no talks held on detailed issues with Qatari mediator. said:. Iran delegation will depart New York for Tehran on Monday night.
  • Iranian MP Ebrahim Rezaei said no negotiations will begin until the US fulfils its commitments in the Islamabad understanding, while he stated that Iranian diplomats lack permission for bilateral or trilateral talks in the current situation. said:. US failed to release blocked funds after Islamabad deal.
  • UN Secretary-General Guterres requested in a meeting with Iran's Foreign Minister Araghchi for a continuation of negotiations to achieve peace, according to Fars News Agency.
  • US President Trump posted "Axios just released a story that “Trump” offered Sanctions Relief and Frozen Funds to Iran. This is untrue. I offered them NOTHING! Axios’ story, like most others, is a HOAX". Full post "Axios just released a story that “Trump” offered Sanctions Relief and Frozen Funds to Iran. This is untrue. I offered them NOTHING! Axios’ story, like most others, is a HOAX, used only for purposes of satisfying their Trump Derangement Syndrome. They should withdraw this fake story, IMMEDIATELY!".

A more detailed look at global markets courtesy of Newsquawk

APAC stocks were mostly subdued following the weak handover from Wall Street, where the major indices were pressured as oil prices and yields continued to climb, amid a slew of conflicting geopolitical headlines. ASX 200 traded rangebound with the index kept afloat for most of the session amid outperformance in the local tech, mining and materials industries, but with the upside limited after disappointing Household Spending and with mild pressure seen after the RBA hiked rates as expected and stuck to the hawkish script. Nikkei 225 underperformed and tested the 65,000 level to the downside, with the declines led by weakness in refiner and power-related stocks. KOSPI was choppy with the index ultimately dragged lower by the tech giants amid recent upside in yields, while South Korea's Finance Minister noted they are closely monitoring the bond market and will conduct a treasury bond buyback if bond yields rise excessively. Hang Seng and Shanghai Comp traded mixed with Hong Kong pressured amid weakness in some autonames and as fast fashion retailer Shein slumped after it reported its H1 oper. profit fell by over 50% Y/Y, while the mainland was resilient after the PBoC and government agencies issued guidance to expand capacity and improve the quality of China’s service sector through financial support, and China also asked local governments to pilot high-quality policies to boost consumption.

Top Asian News

  • China has asked local governments to pilot high-quality policies to boost consumption, according to SCMP.
  • Japan's Chief Cabinet Secretary Kihara said multi-layered Japan-China communication is important.

European bourses (STOXX 600 +0.5%) are broadly firmer this morning, with sentiment buoyed by increased hopes of US-Iran diplomacy – although uncertainty remains (see commodities for details). The energy complex has waned off best levels throughout the London morning, which has also helped lift the equities complex. European sectors hold a positive bias. Tech takes the top spot, reversing some of the pressure seen in the prior session. Industrials and Basic Resources complete the top three, with the latter rebounding from the pressure seen on Monday. To the downside, Food Beverage & Tobacco is joined by Energy and Optimised Personal Care.

Top European News

  • UK PM Burnham has been warned by one of Britain’s largest unions that scrapping the triple lock on state pensions to help fund free social care for the elderly would be “electoral suicide” amid growing cabinet splits, reported The Times.

FX

  • DXY is firmer after strengthening on Monday alongside higher US yields, with the Buck supported by elevated energy prices and continued Fed tightening expectations. DXY briefly rose from around 101.30 to above 101.38 in recent trade before paring slightly despite a dip in yields at the time, with the index currently towards session highs in a 101.17-101.44 range.
  • EUR/USD is softer as the Dollar strengthens, with the pair extending below 1.1350 and trading towards the bottom of a 1.1343-1.1374 range. Spanish CPI printed hotter than expected at 4.9% Y/Y (exp. 4.7%, prev. 4.3%), with Core CPI also rising to 3.1% from 2.9%, although the data provided little support to the Single Currency.
  • GBP is softer against the Dollar and trades towards the lower end of a 1.3227-1.3258 range. Sterling-specific newsflow centres on PM Burnham’s Labour conference speech later, where reports suggest he will edge the party closer towards rejoining the EU and signal an end to the pensions triple lock, although price action thus far remains largely driven by the firmer Dollar.
  • JPY is broadly flat against the Dollar but outperforming most G10 peers, with USD/JPY trading around the middle of a 157.20-157.59 range. Japanese Finance Minister Katayama reiterated that the undervalued Yen is problematic and said Japan and the US agreed to bolster cooperation on FX after discussions with Treasury Secretary Bessent.
  • Antipodeans underperform, led by AUD following the RBA. The Bank unanimously hiked rates by 25bps to 4.60% and retained the option of further tightening, but Governor Bullock subsequently struck a more dovish-than-usual tone, saying she hopes the four hikes delivered this year will be restrictive enough to slow inflation and that further hikes may not be needed if inflation comes down. AUD/USD fell from 0.7021 during the press conference to a 0.6973 low and remains close to session lows. NZD is also softer against the Dollar.
  • Japanese Finance Minister Katayama said exchanged views on FX trends with US Treasury Secretary Bessent on Friday and agreed to bolster cooperation, adds we believe the undervalued yen, in general, is problematic. said:. Will continue close communications with US Treasury to ensure orderly Forex markets. PM Takaichi's administration is not reflationary. Closely monitoring bond markets. Interest rates are determined by markets. Will communicate closely with bond markets and conduct appropriate debt management policy. Will communicate closely with market participants while maintaining high sense of urgency.

Central Banks

  • RBA Governor Bullock said inflationary pressures to last longer than expected; inflation is driven by domestic capacity pressures; Board will raise rates again if needed.
  • RBA hikes the Cash Rate by 25bps to 4.60%, as expected with the decision unanimous, while it stated inflation remains elevated and some of the upside risks in August are materialising.
  • ECB’s Kazimir said the rate hike was unavoidable, energy prices remain a key factor, and January repricing will be key for him; ECB needs flexibility, it has enough time.
  • PBoC injected CNY 90.5bln via 7-day reverse repos and CNY 698.5bln in overnight reverse repos.
  • PBoC set USD/CNY mid-point at 6.7411 vs Exp. 6.7177 (prev. 6.7399).
  • Indonesia's central bank said rupiah weakens on higher global inflation and oil price risk., adds rupiah depreciation is due to worries about global inflation and fiscal risk amid high crude prices and interest rates.

Fixed Income

  • A firmer start to the day, but the magnitudes vary significantly. USTs near-enough flat, awaiting an update on the geopolitical front; as it stands, Iran has suggested that a final response from the US could be presented to them by the US via Qatari mediators. Though, details on that remain light. Nonetheless, and despite relatively punchy (but familiar) Iranian rhetoric, energy has eased off highs across the morning.
  • USTs flat in 104-08+ to 104-19 parameters. Aside from the above, the day features a handful of Fed speakers that may prove pertinent in addition to the latest JOLTS and confidence data stateside.
  • Bunds firmer by around 20 ticks at the time of writing, a few ticks shy of Monday’s 119.71 peak thus far. Specifics for the space are a little light, no move to ECB speak or a handful of data points. Otherwise, focus remains on the energy complex, and particularly TTF which continues to ease but remains well above EUR 70/MWh.
  • Gilts outperform, firmer by c. 50 ticks at best, but have eased modestly off the 84.44 peak across the morning. Outperformance comes ahead of the 14:00BST speech by UK PM Burnham at the Labour Party Conference. A speech that is expected to touch on a number of topics as part of his plan for the UK ahead.
  • Particular focus will be on the triple lock, reports hint that he will open the door to an end to this in his speech, by signalling a review of it as part of the next Labour manifesto. Reporting that drives Gilts higher, as the fiscal cost of the commitment is already significant and is projected to increase markedly in the years ahead. However, it remains to be seen if there is the political/public appetite for this, and what measure(s) Burnham will have to provide to offset the hit to pensioners. For reference, projections for the lock suggest it will cost over GBP 15bln/yr in 2030.
  • Italy sold EUR 6.5bln (vs exp. EUR 5.5-6.5bln) 3.95% 2032 and 4.00% 2036 BTPs.
  • UK sold GBP 4.25bln 4.875% 2036 Gilt: b/c 3.34x (prev. 3.65x), average yield 5.383% (prev. 5.155%), tail 0.5bps (prev. 0.1bps).
  • Deutsche Telekom (DTE GY) files to sell EUR 1.5bln three-parter.
  • Japan sold JPY 300bln in 40-year JGBs; b/c 3.10x (prev. 2.82x), highest accepted yield 4.125% (prev. 3.865%). Price at the highest accepted yield 93.69 (prev. 98.68).

Commodities

  • WTI Nov and Brent Dec futures are modestly firmer/flat but off earlier highs as traders continue to digest conflicting US-Iran developments (see below). WTI trades towards the lower end of a USD 92.44-94.74/bbl range, while Brent similarly sits near the bottom of a USD 97.62-100.28/bbl range, albeit both firmer intraday.
  • Dutch TTF is softer, pulling back from earlier highs despite continued concerns around European energy security. The European Commission has asked member states to consider measures to reduce gas and electricity demand for as long as necessary. TTF is choppy but currently towards the middle of a EUR 71.65-73.10/MWh range.
  • Precious metals are firmer as they attempt to recover some of Monday’s heavy losses, helped by the modest pullback in global yields this morning. Spot gold trades towards the upper end of a USD 4,113-4,149/oz range, although fundamentals remain against the yellow metal amid high energy prices and expectations of further Fed tightening. Spot silver is flat towards the middle of a narrow USD 60.29-61.03/oz range.
  • Base metals are softer, with the complex remaining near recent lows amid subdued risk sentiment and ahead of China’s holiday period. 3M LME copper sits at the bottom of a USD 14,391-14,518/t range, while COMEX copper is lower by around 0.6%.
  • In geopolitics, Iran expects a US response today to its latest proposal on reopening the Strait of Hormuz, although reports of Tehran showing flexibility on its nuclear position were denied by Iranian officials, while Trump also denied offering sanctions relief or frozen funds in return for nuclear concessions. This morning, Iran’s Parliament Speaker warned that if Iran cannot sell oil, no one in the region will sell oil, while an explosion was reported involving a commercial vessel in the Strait and Houthis reportedly attacked oil facilities in Yanbu. On the supply side, Saudi Arabia has resumed crude loading from Yanbu following partial repairs to the East-West pipeline.
  • Gas production in Iran's South Pars Phase 11 reaches 1bln cubic feet, IRIB reported.
  • Iraqi Oil Ministry announces the start of trial operations for the storage capacity project at the Nasiriyah gas depot, INA reported.
  • EU Energy Commissioner Jorgensen said they do not want to relax methane rules, but rather to delay their implementation.
  • Spanish Energy Minister said that Spain, Portugal and Luxembourg sent a letter to the Commission asking for a new renewable energy capacity. Spain wants the EU to consider measures to capture windfall profits from high energy prices. Spain is still waiting for a response to the proposal. Spain wants a permanent levy on the oil and gas industry to raise climate funds.
  • Syria said gas pipeline fire between Al-Shola and Deir al-Zour caused by sabotage, while efforts underway to extinguish fire and fire stopped gas supply from Jbeissa plant to power stations.
  • British government is said to be privately lobbying the Trump administration for an exemption should the US impose any diesel export ban, according to sources.
  • IEA Chief Birol said Europe is one of the regions most exposed to the degrading diesel market, which the IEA is monitoring closely. IEA will discuss with member governments whether more strategic reserve releases are needed. IEA is discussing the situation with countries.

Trade/Tariffs: 

  • Nvidia (NVDA) and AMD (AMD) are lobbying US President Trump's administration to stop lawmakers from curbing exports to China, Politico reported citing sources; asking that lawmakers hold off on the China-related chip export restriction in the defence bill. The legislation in question has bipartisan support.
  • US import bans on a range of Canadian products, including alcoholic beverages, dairy ingredients and some motorcycles, took effect as scheduled.

Geopolitics: Ukraine

  • Estonian official said Russia was behind an arson attack on defence maker Milrem Robotics.
  • Ukraine's air force reported guided bombs striking the Kharkiv region.
  • Russian President Putin orders an increase in the size of the Russian army.
  • FT reporter posted after a day of relentless drone attacks, Russia is now hitting Kyiv with a wave of ballistic missiles and several explosions have shaken Ukraine's capital in the last few minutes.

Geopolitics: Iran

  • Iranian Parliament Speaker Ghalibaf said if Iran cannot sell oil, no one in the region will sell oil, and warns that if Iran’s security is not ensured, no infrastructure will be safe, ISNA reported.
  • IRGC reiterates that Iran will never seek a nuclear weapon, Al Jazeera reported; reiterates conflict takes a different form and will bring new weapons to the field. Most of the American bases in the region have been destroyed and can no longer be used again.
  • US Secretary of State Rubio tells Fox News Iran has threatened to attack our interests around the world and we are taking those threats very seriously, while he warned there will be repercussions if American interests are attacked.
  • Iran Supreme Leader senior adviser warned that if Iran is attacked by the US again, the confrontation will expand to new fronts, according to Press TV.
  • Iranian MP said before any negotiations, the US must accept Iran's conditions, reported Fars.
  • An explosion was reported in the Strait of Hormuz, which is said to be a commercial ship attempting to pass through the southern route of the Strait, Fars reported citing Ambrey.

Other:

  • Houthis reportedly attacked oil facilities in Yanbu on the Red Sea with a large number of ballistic missiles and drones; satellites showed several giant oil storage tanks at the Al-Mu'ajiz terminal in southern Saudi Arabia ablaze, Al Akhbar reported. According to an economic source close to the Ansar Allah movement, who spoke to Al-Akhbar, Sana'a forces have designated Aramco assets in Jizan, Najran, and Yanbu, valued at USD 100bln, as legitimate targets in the current round of fighting. This phase will be followed by the addition of strategic facilities of equal importance to Aramco's to their target bank.
  • Intelligence sources say that Houthis expand target bank in Saudi Arabia, according to ILNA.
  • N12's Lipkin reported that the commander of Hama's northern Gaza Strip brigade was "eliminated".
  • US Treasury Department said Treasury Secretary Bessent met with Lebanon's PM today, while he urged Lebanon to disrupt Iran and Hezbollah networks.
  • US Secretary of State Rubio told Lebanon's PM, we support a sovereign Lebanese state free from the harmful influence of Hezbollah and Iran. said:. Tripartite framework is the only way to achieve lasting peace between Lebanon and Israel.
  • US Secretary of State Rubio urges Cuba to choose a different path and said the US will not tolerate threat to national security.
  • Riyadh airspace experienced threat disruption and flight suspensions with planes held in holding pattern over Riyadh for about 20 minutes, according to SNN.
  • North Korea said US approval for South Korea's nuclear submarine increases regional instability.

US Event Calendar

  • 9:00 am: Jul FHFA House Price Index MoM, est. 0.1%, prior 0%
  • 10:00 am: Sep Conf. Board Consumer Confidence, est. 89, prior 89.4
  • 10:00 am: Aug JOLTS Job Openings, est. 7227.5k, prior 7271k

Central Bank Speakers 

  • 11:00 am: Fed’s Bowman Delivers Opening Remarks
  • 12:40 pm: Fed’s Barr Speaks On Economic Outlook
  • 1:00 pm: Fed’s Goolsbee Speaks in Moderated Discussion
  • 1:30 pm: Fed’s Musalem Speaks on US Economy
  • 2:00 pm: Fed’s Williams Gives Keynote Remarks
  • 3:00 pm: Fed’s Waller Speaks on Payments System

DB's Jim Reid concludes the overnight wrap

The relentless bond selloff has shown no sign of easing, with a fresh rise in yields overnight as oil prices keep moving higher. The immediate driver was the weekend news that President Trump had rejected Iran’s proposal. So Brent crude was up +0.92% yesterday to $105.28/bbl, and this morning it’s up another +1.92% to $107.30/bbl. And as concerns have mounted about persistent inflation, that’s pushed yields up to multi-year highs once again. In fact, yesterday saw the 10yr Treasury yield (+7.6bps) close at 5.24%, and this morning it’s up further to 5.26%. So we’re not far off the 2007 closing peak of 5.29%, which would then be its highest level since 2002 if that’s surpassed. Moreover, yesterday started to see growing pressure on risk assets as well, as the S&P 500 fell -0.77%, whilst US and European HY spreads reached their widest levels since April.

Those oil moves were the main catalyst for the latest bond moves, as the weekend headlines made clear that both the US and Iran remained far from an immediate deal. After all, Trump said on Saturday that “They made a proposal but I rejected it”. And Iran’s foreign minister Araghchi said on Sunday that “we have no reason to come back to diplomacy and engage with this administration once again”. So when oil markets reopened again yesterday, that immediately drove a fresh jump.

To be fair, there were some signs of potential progress, as Iran’s foreign minister Abbas Araghchi met with mediators in New York yesterday, according to Iran’s ISNA. And later on, we saw similar reports by CNN and then Axios that Trump was open to sanctions relief and releasing frozen Iranian funds if there was “concrete” progress by Iran on the nuclear issue. So coupled with the news that Saudi Arabia has restored about half the flows through its East-West pipeline, this helped Brent pull back to flat on the day after trading as much as +4.5% higher. But then into the close, oil prices moved higher again as Trump denied the Axios story, while Iran’s Press TV claimed that reports of Iranian flexibility in nuclear talks were false.

Given all the rhetoric from both sides, investors have become more pessimistic since last week’s hopes about some kind of negotiated deal around the UN. In general, there’s been a growing awareness that hopes for a US-Iran deal have been repeatedly dashed in recent months, and that scepticism about the Strait of Hormuz reopening any time soon has led investors to price a longer period of high prices into next year. For instance, the December 2027 Brent future (+0.22%) closed at a new high of $80.29/bbl yesterday, and this morning it’s up again to $80.67/bbl. So for markets it wasn’t just a story about front-end prices yesterday, but a more protracted period of high oil prices stretching well into 2027.

This inflation momentum led investors to price in a more hawkish path for central banks, with growing expectations of a Fed rate hike at their next meeting. Indeed, as we go to press this morning, futures are pricing in a 73% chance of an October hike. And further out, markets are now pricing in the most hawkish path to date for the coming months, with 93bps of hikes now priced by the June 2027 meeting. Those moves came as Fed Governor Cook said that the labour market appears well positioned to handle higher rates, suggesting it is “roughly in balance and gradually improving.”

With markets pricing in more rate hikes and energy prices up yet again, that put even more pressure on Treasuries across the curve. Among others, the 10yr yield (+7.6bps) moved up to 5.24% by the close, leaving it not far away from its 2007 closing peak of 5.29%. Indeed, if it surpasses that milestone, it would then be the highest 10yr yield since 2002. Elsewhere, yesterday also saw the 2yr yield (+7.9bps) rise to 4.93%, the highest since 2024, and the 30yr yield (+5.6bps) rose to a new post-2004 high of 5.55%. And once again, it was real yields driving most of the increase, with 10yr real yields (+7.1bps) reaching a new post-2008 high of 2.89%.

Over in Europe it was much the same story, with yields also hitting multi-year highs across the continent. That included 10yr bunds (+4.1bps), which hit a post-2009 high of 3.64%, whilst 10yr OATs (+7.8bps) hit a post-2008 high of 4.77%, and 10yr gilts (+5.6bps) hit a post-2007 high of 5.42%. Moreover, there was also a widening in sovereign bond spreads, with the Franco-German 10yr spread up to a post-2012 high of 113bps. The last time it was that wide was just a few weeks before Mario Draghi delivered his famous “whatever it takes” speech that was seen as a turning point in the Euro crisis.

That backdrop also hit equities on both sides of the Atlantic, with the major indices generally moving lower. In the US, the S&P 500 (-0.77%) fell in a broad-based decline, with matters not helped by a larger fall for the Magnificent 7 (-1.72%). Nevertheless, some of the defensive sectors managed to post modest gains, including consumer staples (+0.40%), healthcare (+0.29%) and energy (+0.21%). Meanwhile in Europe, the STOXX 600 (+0.005%) inched up by less than a basis point, as strong gains for equities in the Netherlands, Austria and Greece helped to outweigh declines in the larger countries, with the DAX (-0.13%) and the FTSE 100 (-0.10%) both falling.
There were also signs of stress in other risk assets yesterday, as IG and HY credit spreads widened to levels last seen in April in both the US and Europe. So by the close, US IG (+2bps) and HY (+9bps) had both seen a notable jump, as had European IG (+3bps) and HY (+9bps). Moreover, that comes after US HY saw its biggest weekly widening last week (+27bps) since October last year.

This trend has generally continued overnight, with many indices in Asia lower this morning, including the Nikkei (-1.24%), the KOSPI (-0.93%) and the Hang Seng (-0.63%). The main exception to this is in mainland China, where the CSI 300 (+0.03%) and the Shanghai Comp (+0.08%) have posted very modest advances. Meanwhile, the rise in bond yields has also continued, with Japan’s 10yr yield (+0.8bps) up to 3.07% this morning. That said, despite the selloff, Japan’s 40yr government bond auction still attracted the strongest demand since 2020, with the bid-to-cover ratio at 3.1, up from 2.82 at the previous auction.

Otherwise overnight, the hawkish newsflow has continued, as the Reserve Bank of Australia delivered a 25bp rate hike, which takes its cash rate target to 4.60%. The move was expected by markets, and its statement said that “inflation is still too high” and they would be willing to raise “the cash rate target further if needed.” Meanwhile, Australia’s 10yr government bond yield is up +0.2bps this morning at a post-2011 high of 5.42%.

Looking at the day ahead, US data releases include the JOLTS report for August, the FHFA’s house price index for July, and the Conference Board’s consumer confidence for September. Otherwise, we’ll get UK mortgage approvals for August, and the European Commission’s economic sentiment indicator for the Euro Area in September. Then, from central banks, we’ll hear from the Fed’s Bowman, Barr, Goolsbee, Musalem, Williams and Waller, the ECB’s Kazimir, Nagel, Escriva, Cipollone, and the BoE’s Mann and Taylor.

Tyler Durden Tue, 09/29/2026 - 08:39

Hurricane Polo Pounds Baja, Threatens To Swing Its Moisture Across US Southwest

Zero Hedge -

Hurricane Polo Pounds Baja, Threatens To Swing Its Moisture Across US Southwest

Hurricane Polo made landfall in Mexico's Baja California Sur as a Category 2 hurricane before weakening to Category 1, with maximum sustained winds around 80 mph.

Forecasters are now tracking the massive plume of tropical moisture associated with Polo, which could bring heavy rainfall and flash flooding to the southwestern US, with all eyes on Texas.

The danger for the US is that the massive plume of tropical moisture is expected to spread across the Four Corners region and into the Central Plains, raising the risk of significant flash flooding.

"Two areas stand out in the latest 7-day forecast. Portions of Texas and Oklahoma could see localized 5-8" totals, while another corridor from Nebraska into Iowa could pick up localized 3-6". With multiple rounds of rain possible, totals could add up quickly where heavier bands repeatedly track over the same locations increasing flooding concerns," private weather forecaster BAM Weather wrote on X.

Weather influencer Max Velocity wrote on X, "This is insane... I can't remember the last time I saw this much rain forecasted for such a large area in the United States."

The plume of tropical moisture should provide welcome relief from severe drought conditions across the southwestern US.

The National Weather Service has issued flood watches across parts of 11 states, including much of Arizona and New Mexico, covering more than 14 million Americans.

Tyler Durden Tue, 09/29/2026 - 08:35

Tether Says It Helped Freeze $550M In Iran-Linked USDT This Year

Zero Hedge -

Tether Says It Helped Freeze $550M In Iran-Linked USDT This Year

Authored by Felix Ng via Cointelegraph,

Stablecoin issuer Tether said it helped authorities freeze nearly $550 million in Iran-linked USDT during 2026, as a Senate Democrat called for an investigation into the stablecoin issuer on Monday.

In a statement on Monday, the company said it has been working closely with international law enforcement for years. This year alone, it froze more than $130 million in USDT across four wallets, and in April, it froze more than $344 million linked to the Central Bank of Iran.

"Tether has consistently demonstrated that USDT is not a haven for sanctioned actors, terrorist organizations or criminal networks," said Tether CEO Paolo Ardoino.

The statement from Tether came as Democratic investigators on the Senate Permanent Subcommittee on Investigations released a report alleging USDT had become a key channel for Iran to evade sanctions.

Investigators found that 84% of 846 crypto wallets sanctioned over ties to Iran had transacted exclusively or nearly exclusively in USDT. The findings prompted US Senator Richard Blumenthal to call on the Treasury and Justice departments to investigate potential sanctions violations.

Tether said its cooperation with authorities globally had resulted in more than $4.9 billion in assets being frozen, including more than $2.4 billion connected to US authorities.
"The record is public: the DOJ, FBI, Secret Service, HSI, OFAC and authorities around the world have repeatedly worked with Tether to trace, freeze and recover assets. We will continue to make that capability available to authorities working to stop terrorism, sanctions evasion, fraud and other serious crimes," Ardoino said.

Tyler Durden Tue, 09/29/2026 - 08:20

Trump Uses Recission "Loophole" To Cut Nearly $1 Billion In Funds For Illegals

Zero Hedge -

Trump Uses Recission "Loophole" To Cut Nearly $1 Billion In Funds For Illegals

To summarize the Democrat Party's current strategy on immigration, here is essentially how it works: 

Whenever in power, they create billions in incentives and subsidies to entice third world migrants to flood the US en masse.  With open borders and amnesty programs, moving 10 million or more illegals at a time into the country is easy and fast.  When out of power, they use lawfare and political obstruction to prevent deportations and slow down the process.  

In other words, make immigration easy and remigration nearly impossible.  Stall for four years, regain power during the next election while pro-deportation constituents whine and complain about the president "not doing enough", then repeat the process all over again.  Under the current system, it would take three full conservative presidential terms or more to undo what Democrats did in a single term.  That is the play they are relying on.

From 2017 to 2024, the Trump Administration faced 64 nationwide injunctions on immigration and deportation policies; 92% of them came from judges appointed by Democrat presidents.  

From 2025 to today, Trump has been blocked at least 86 times by activist judges nationwide or class-wide injunctions and major program pauses.  To put this in perspective, nationwide injunctions were extremely rare through the 20th Century.  Starting in 2000, the numbers increased, but nowhere near the level Trump has dealt with. 

George W Bush had only 6 injunctions from Democrat judges. Barack Obama had 12 injunctions from Republican judges.  Biden had 28 injunctions (largely because of his efforts to expand pandemic controls and enforce vaccine mandates). 

It is undeniable - The bureaucracy is being abused as a way to stop Trump from enacting normal policy decisions on immigration.  This forces the White House to exploit every legal loophole available just to get anything done in the next couple of years.  

Enter the "recission" method...

The White House has moved to cancel $810 million in already-approved federal spending through a rare budget tactic called a “pocket rescission.”  The administration frames it as cutting “wasteful and harmful” programs tied to noncitizens, DEI, and ideology.  Critics call it "illegal". 

The timing is what makes the decision controversial. The federal fiscal year ends September 30th. Under the Impoundment Control Act of 1974, a president can propose canceling appropriated money and withhold it for 45 days while Congress considers the request.  By sending this package with only five days left, the White House is betting the money will expire before Congress can act. 

This is the second such move in about 50 years and both came in Trump’s second term. Last year the administration used the same tactic on $5 billion in foreign aid; the Supreme Court later allowed that effort to proceed 6–3, citing foreign-affairs authority.   

Legal challenges are still likely, but perhaps this situation will help to illustrate why the deportation process has been a grind.  Even with the constant interventions, deportations have skyrocketed by 30% in the past year to 80,000 illegals removed per month.  Trump should be commended for finding a way despite all the obstacles Democrats have put in place.     

Tyler Durden Tue, 09/29/2026 - 06:55

Pages